Share This Page
Drug Sales Trends for SARAFEM
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for SARAFEM (2011)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
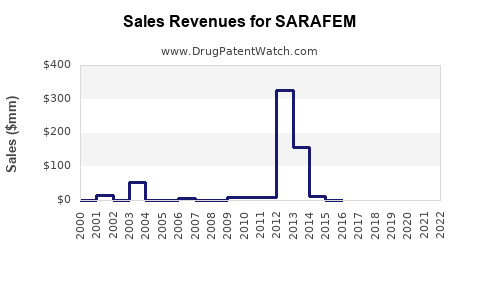
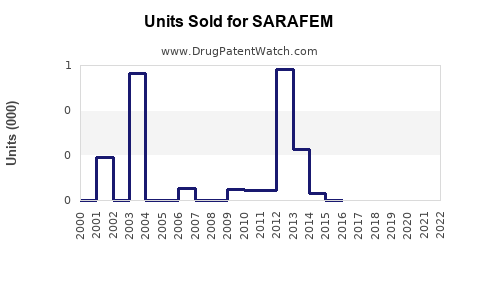
Annual Sales Revenues and Units Sold for SARAFEM
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| SARAFEM | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| SARAFEM | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| SARAFEM | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| SARAFEM | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| SARAFEM | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| SARAFEM | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
SARAFEM Market Analysis, Sales Forecast, Patent Position, and Generic Risk
SARAFEM is the former U.S. brand for fluoxetine hydrochloride approved for premenstrual dysphoric disorder, or PMDD. Its commercial value is now limited because fluoxetine is available from multiple generic manufacturers and the branded product has no meaningful exclusivity position. The relevant market is generic fluoxetine for PMDD, not a growing standalone SARAFEM franchise.
A reasonable U.S. market estimate for fluoxetine used specifically in PMDD is approximately $5 million to $25 million annually at generic retail and payer prices. SARAFEM-branded revenue is likely negligible. Under a base-case model, the PMDD fluoxetine market remains broadly stable through 2030, with unit demand offset by lower generic pricing.
What is SARAFEM and what was it approved to treat?
SARAFEM is fluoxetine hydrochloride, the same active pharmaceutical ingredient used in PROZAC. The FDA approved SARAFEM in 2000 for the treatment of PMDD in women with sufficiently severe symptoms that interfere with work, school, social activities, or relationships [1].
The approved PMDD dosing options are:
| Product characteristic | SARAFEM position |
|---|---|
| Active ingredient | Fluoxetine hydrochloride |
| Drug class | Selective serotonin reuptake inhibitor |
| FDA indication | Premenstrual dysphoric disorder |
| Initial U.S. approval | 2000 |
| Typical PMDD dose | 20 mg daily |
| Dosing approaches | Continuous daily dosing or intermittent luteal-phase dosing |
| Original strengths | 10 mg, 20 mg, and 30 mg capsules |
| Primary competitors | Generic fluoxetine, sertraline, paroxetine, escitalopram |
| Current commercial position | Generic-dominated and low-value branded product |
Fluoxetine remains clinically relevant for PMDD because it has evidence for reducing affective, behavioral, and physical symptoms. The FDA-approved label permits continuous dosing and intermittent dosing beginning approximately 14 days before expected menstruation and continuing until the onset of menses [1].
What is the current FDA status of SARAFEM?
SARAFEM’s FDA approval established the product’s regulatory status, but it did not preserve a commercially meaningful branded market after loss of exclusivity for fluoxetine.
The key regulatory facts are:
- Fluoxetine is an FDA-approved active ingredient for depression and several other psychiatric indications.
- PMDD is an FDA-recognized indication for fluoxetine.
- Generic fluoxetine products are approved under abbreviated new drug applications.
- Generic fluoxetine is available in capsules, tablets, and oral solution, although not every generic strength or dosage form is marketed for PMDD.
- The FDA Orange Book remains the principal source for current listed products, patents, and exclusivity data [2].
The market should be analyzed as a generic SSRI market with a PMDD indication rather than as an active branded SARAFEM market.
When did SARAFEM lose exclusivity?
SARAFEM has no current meaningful market exclusivity. Fluoxetine’s core composition-of-matter protection expired in the United States in the early 2000s, and multiple generic manufacturers subsequently entered the market.
The commercial sequence was:
| Period | Market event | Commercial effect |
|---|---|---|
| 1980s | Fluoxetine developed and approved under the PROZAC brand | Originator antidepressant market established |
| 2000 | SARAFEM approved for PMDD | New branded indication and product positioning |
| Early 2000s | Core fluoxetine exclusivity expired | Generic entry became possible |
| 2000s onward | Generic fluoxetine expanded across indications | Price compression and loss of branded share |
| Current market | Generic fluoxetine is widely available | SARAFEM has limited standalone value |
The PMDD indication did not create a durable barrier to generic competition. Generic manufacturers could market fluoxetine for approved indications once the relevant product and regulatory protections no longer blocked entry.
How large is the SARAFEM and fluoxetine PMDD market?
No public financial reporting isolates SARAFEM sales or fluoxetine prescriptions by PMDD indication. IQVIA, Symphony Health, and payer databases may contain the relevant prescription data, but those datasets are commercial and are not publicly reported at the product-indication level.
A bottom-up market model produces the following range:
| Variable | Low case | Base case | High case |
|---|---|---|---|
| U.S. reproductive-age women | 60 million | 65 million | 70 million |
| PMDD prevalence | 3% | 5% | 8% |
| Women with PMDD | 1.8 million | 3.25 million | 5.6 million |
| Diagnosed | 25% | 35% | 45% |
| Receiving drug therapy | 20% | 30% | 40% |
| Fluoxetine share of treated PMDD | 10% | 20% | 30% |
| Fluoxetine-treated PMDD patients | 9,000 | 68,250 | 302,400 |
| Annual generic drug spend per patient | $30 | $60 | $100 |
| Estimated annual U.S. market | $0.3 million | $4.1 million | $30.2 million |
The resulting range is approximately $1 million to $30 million annually, with a base case near $4 million to $10 million for fluoxetine specifically used for PMDD. Broader estimates can reach $25 million if treatment persistence, higher pharmacy prices, or cash-pay utilization is included.
The total fluoxetine market is much larger because the drug is also prescribed for major depressive disorder, obsessive-compulsive disorder, bulimia nervosa, panic disorder, and other conditions. PMDD likely represents a small portion of total fluoxetine utilization.
What are the sales projections for SARAFEM?
SARAFEM-branded sales are expected to remain immaterial unless a company relaunches the product with a new commercial strategy, reimbursement position, or delivery format. The following projections apply to U.S. fluoxetine use for PMDD, not reported SARAFEM brand revenue.
Base-case U.S. PMDD fluoxetine projection
| Year | Estimated treated patients | Estimated market value | Year-over-year change |
|---|---|---|---|
| 2025 | 60,000-80,000 | $4 million-$8 million | Baseline |
| 2026 | 61,000-82,000 | $4 million-$8 million | 0%-2% |
| 2027 | 62,000-84,000 | $4 million-$8 million | 0%-2% |
| 2028 | 63,000-86,000 | $4 million-$8 million | 0%-2% |
| 2029 | 64,000-88,000 | $4 million-$9 million | 0%-3% |
| 2030 | 65,000-90,000 | $4 million-$9 million | 0%-3% |
The base case assumes modest growth in diagnosis and treatment, offset by generic price erosion. It does not assume a branded SARAFEM relaunch.
Scenario analysis
| Scenario | 2030 PMDD fluoxetine sales | Primary driver |
|---|---|---|
| Low | $2 million-$4 million | Continued generic price compression and low diagnosis |
| Base | $4 million-$9 million | Stable treatment share and gradual diagnosis growth |
| High | $15 million-$30 million | Improved PMDD diagnosis, greater SSRI treatment, higher payer prices |
| Branded relaunch case | $5 million-$20 million brand sales | New marketing, differentiated packaging, or specialty distribution |
A branded relaunch would face a difficult reimbursement environment. Payers generally favor low-cost generic fluoxetine and other SSRIs. A relaunch would require a differentiated product, such as an extended-release formulation, digital adherence support, combination therapy, or a commercially meaningful delivery advantage.
What drugs compete with SARAFEM for PMDD treatment?
SARAFEM competes clinically with other SSRIs and, in some patients, hormonal therapies. The most important pharmaceutical competitors are:
| Drug | Brand examples | PMDD position |
|---|---|---|
| Fluoxetine | SARAFEM, PROZAC, generics | FDA-approved; continuous or intermittent dosing |
| Sertraline | ZOLOFT, generics | FDA-approved for PMDD |
| Paroxetine controlled release | PAXIL CR, generics | FDA-approved for PMDD |
| Escitalopram | LEXAPRO, generics | Used off-label or supported by clinical evidence |
| Other SSRIs | Various generics | Used according to clinical judgment |
| Combined oral contraceptives | YAZ and generics | Used for selected patients |
| GnRH therapies | Various | Reserved for more severe or refractory disease |
Sertraline and paroxetine controlled release are the closest FDA-approved SSRI competitors. Generic availability across this class limits price differentiation.
What patents protect SARAFEM and fluoxetine?
The core fluoxetine composition-of-matter patents are expired. The current commercial risk is therefore not a blocking patent estate but the absence of meaningful patent protection.
Potential historical protection categories included:
- Fluoxetine compound patents.
- Pharmaceutical composition patents.
- Capsule and dosage-form patents.
- Method-of-use patents covering psychiatric disorders or PMDD.
- Regulatory exclusivity linked to the PMDD indication.
Those rights do not provide a current barrier to generic fluoxetine entry. Any remaining formulation or method-of-use patents would need to be evaluated individually in the FDA Orange Book and relevant patent databases. They would not ordinarily prevent generic manufacturers from selling fluoxetine for other approved indications or from entering after applicable protections expire.
Are there Paragraph IV challenges to SARAFEM?
Paragraph IV litigation is not a current commercial issue for SARAFEM’s core product because fluoxetine generics have been marketed for many years. Generic entry occurred after expiration or resolution of the relevant early fluoxetine protections.
The principal legal exposure is therefore not an active SARAFEM Paragraph IV dispute. It is ordinary generic competition, including:
- Multiple ANDA-approved fluoxetine products.
- Price competition among manufacturers.
- Pharmacy substitution.
- Low switching costs for prescribers.
- Limited ability to defend brand share through patent litigation.
Any later reformulation or new PMDD delivery system would create a separate patent and Paragraph IV analysis.
What formulation patents or manufacturing barriers exist?
Fluoxetine is a mature, relatively accessible small molecule. Manufacturing barriers are limited compared with complex biologics, sterile injectables, or modified-release delivery systems.
The main technical barriers are:
- Compliance with active pharmaceutical ingredient specifications.
- Control of capsule content uniformity.
- Stability and impurity control.
- Bioequivalence testing.
- Reliable supply of fluoxetine hydrochloride.
- FDA-compliant manufacturing and quality systems.
Standard immediate-release fluoxetine does not have a strong manufacturing moat. A differentiated formulation could create more defensible intellectual property, but the commercial opportunity would remain constrained by the low price of generic SSRIs.
What is the competitive landscape for PMDD drugs?
The PMDD market is fragmented across SSRIs, hormonal contraceptives, psychotherapy, lifestyle interventions, and specialist care. No single product controls the full treatment pathway.
Competitive factors include:
- Generic SSRI pricing.
- Physician familiarity with sertraline and fluoxetine.
- Patient tolerance and sexual side effects.
- Preference for intermittent versus continuous therapy.
- Insurance coverage for branded products.
- Diagnostic underrecognition of PMDD.
- Patient preference for hormonal versus nonhormonal therapy.
The market has potential for clinical growth because PMDD is underdiagnosed, but commercial growth is likely to accrue to low-cost generics rather than SARAFEM.
What is the generic launch risk for SARAFEM?
Generic launch risk is effectively realized rather than prospective. The product has already lost the main protections that could restrict generic entry.
For an owner considering a SARAFEM relaunch, the risks are:
| Risk | Assessment |
|---|---|
| Patent protection | Weak |
| Regulatory exclusivity | None of material commercial value |
| Generic substitution | Very high |
| Payer resistance | High |
| Clinical differentiation | Limited for standard fluoxetine |
| Manufacturing complexity | Low |
| Brand pricing power | Very low |
| New formulation opportunity | Possible but commercially uncertain |
A relaunch based only on the SARAFEM name and existing fluoxetine formulation would have limited economic rationale.
How strong is the SARAFEM patent estate?
The patent estate is weak for the existing product. The compound is mature, generic competition is established, and the PMDD indication does not by itself create durable exclusivity.
A stronger estate would require one or more of the following:
- A novel fluoxetine formulation.
- A validated extended-release profile.
- A proprietary intermittent-dosing system.
- A combination product.
- A new delivery device.
- A patentable biomarker or patient-selection method.
- Clinical evidence supporting a differentiated safety or tolerability profile.
Even with new patents, enforceability and commercial value would depend on whether the product provided an advantage that payers and prescribers would recognize.
What licensing deals or transactions involve SARAFEM?
Publicly visible commercial interest in SARAFEM has been limited compared with major branded psychiatric products. The product originated within the broader fluoxetine and PROZAC franchise and was subsequently associated with Warner Chilcott and later pharmaceutical-company portfolios.
There is no publicly reported transaction that materially changes the current market outlook. A new licensing deal would likely be commercially justified only if it involved a differentiated PMDD product rather than legacy SARAFEM capsules.
What revenue exposure exists for manufacturers?
For generic manufacturers, exposure to PMDD is small relative to total fluoxetine revenue. The larger opportunity comes from the full fluoxetine market across depression and other psychiatric indications.
For a branded owner:
- Existing SARAFEM revenue exposure is likely negligible.
- Revenue from a standard branded relaunch would be vulnerable to substitution.
- A premium product would require payer-funded differentiation.
- PMDD diagnosis expansion could increase category volume but would not necessarily increase brand share.
The most attractive commercial opportunity is likely a broader PMDD platform rather than a single legacy brand.
Key Takeaways
- SARAFEM is branded fluoxetine hydrochloride approved for PMDD in 2000.
- The product has no meaningful current exclusivity position.
- Generic fluoxetine, sertraline, and paroxetine controlled release are the main pharmaceutical competitors.
- Public data do not isolate SARAFEM sales or fluoxetine sales by PMDD indication.
- Estimated U.S. fluoxetine sales for PMDD are approximately $1 million to $30 million annually, with a base case of $4 million to $9 million.
- SARAFEM-branded revenue is likely negligible without a differentiated relaunch.
- Generic entry risk is already realized and remains high.
- The existing patent and manufacturing position is weak.
- A commercially credible relaunch would require a new formulation, delivery system, combination product, or clinically differentiated PMDD treatment.
FAQs About SARAFEM Market Size and Commercial Outlook
Is SARAFEM still available in the United States?
The active ingredient, fluoxetine, remains widely available from generic manufacturers. The commercial availability of the SARAFEM brand is limited and does not materially change the generic-dominated market.
Is fluoxetine FDA-approved for PMDD?
Yes. Fluoxetine is FDA-approved for PMDD, including continuous daily dosing and intermittent luteal-phase dosing under the approved labeling.
Which generic drugs compete most directly with SARAFEM?
Generic fluoxetine is the direct substitute. Generic sertraline and paroxetine controlled release are the closest FDA-approved SSRI alternatives for PMDD.
Could a company relaunch SARAFEM profitably?
A standard capsule relaunch would face weak pricing power, generic substitution, and payer resistance. Profitability would require a differentiated formulation, delivery system, or commercial program that supports premium reimbursement.
Does SARAFEM have remaining patent protection?
The core fluoxetine protection is expired. Any surviving formulation or method-of-use rights would require product-specific review, but they do not prevent the established generic market from supplying fluoxetine.
References
- U.S. Food and Drug Administration. (2000). Sarafem (fluoxetine hydrochloride) capsules prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- American College of Obstetricians and Gynecologists. (2023). Management of premenstrual disorders: Clinical practice guideline.
- U.S. Food and Drug Administration. (1987). Prozac (fluoxetine hydrochloride) approval and prescribing information.
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database.
More… ↓
