Share This Page
Drug Sales Trends for PROVIGIL
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for PROVIGIL (2011)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
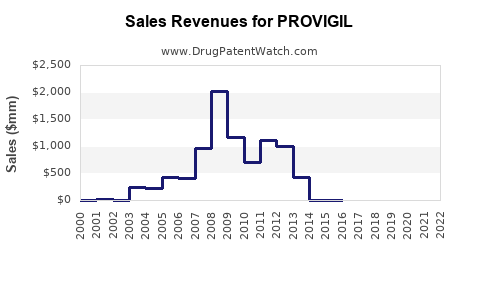
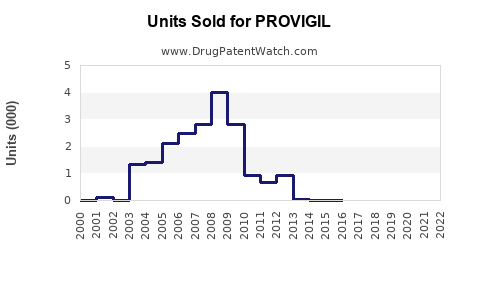
Annual Sales Revenues and Units Sold for PROVIGIL
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| PROVIGIL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| PROVIGIL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| PROVIGIL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Provigil (Modafinil) Market Analysis, Patent Status, and Sales Projections
Provigil is the original brand of modafinil, marketed primarily for narcolepsy, obstructive sleep apnea-related excessive sleepiness, and shift-work sleep disorder. Its U.S. brand exclusivity ended after generic modafinil entered in 2012. The commercial market is now generic-led, with limited branded Provigil revenue and low barriers to additional generic supply. Historical peak sales exceeded $1 billion annually, but current market value is a fraction of that level.
What is the current market status of Provigil?
Provigil is no longer a growth-stage branded product. It is a mature, off-patent prescription stimulant-like wakefulness agent sold mainly as generic modafinil.
| Attribute | Provigil market status |
|---|---|
| Active ingredient | Modafinil |
| Original U.S. sponsor | Cephalon |
| Current brand ownership | Teva Pharmaceuticals through its Cephalon business |
| U.S. approval | 1998 |
| Primary indications | Narcolepsy, obstructive sleep apnea-related sleepiness, shift-work sleep disorder |
| Dosage forms | 100 mg and 200 mg tablets |
| U.S. legal status | Schedule IV controlled substance |
| U.S. generic entry | 2012 |
| Current commercial position | Generic-dominated, mature market |
| Biosimilar risk | Not applicable; modafinil is a small molecule |
| Main competitive risks | Generic price erosion, payer substitution, off-label use restrictions, competing wakefulness drugs |
The FDA-approved label does not establish Provigil as a treatment for fatigue unrelated to the approved sleep disorders. Its commercial market therefore depends on diagnosis, reimbursement, specialist prescribing, and continued use in sleep medicine rather than on the larger and less controlled market for general fatigue or cognitive enhancement (U.S. Food and Drug Administration [FDA], 2015).
How large were Provigil’s historical sales?
Provigil reached blockbuster status before generic competition. Cephalon reported annual Provigil sales of approximately $988 million in 2007. Sales remained above $1 billion in the period immediately before generic entry, supported by chronic use, broad physician awareness, and limited branded competition (Cephalon, 2010; Teva Pharmaceutical Industries Ltd., 2012).
The product’s historical revenue profile was:
| Period | Commercial position | Approximate revenue interpretation |
|---|---|---|
| 1998-2002 | Initial launch and primary brand period | Rapid prescription growth |
| 2003-2007 | Established sleep-disorder franchise | Sales approached $1 billion |
| 2008-2011 | Mature blockbuster | Annual sales reached roughly $1 billion or more |
| 2012 | Generic entry | Rapid brand erosion |
| 2013 onward | Generic market | Brand revenue became commercially limited |
Provigil was one of Cephalon’s principal assets and a major factor in Teva’s 2011 acquisition of Cephalon. Teva paid approximately $6.8 billion for Cephalon, which had reported strong revenue from Provigil, Nuvigil, and other specialty products (Teva Pharmaceutical Industries Ltd., 2011).
When did Provigil lose exclusivity?
Provigil lost practical U.S. market exclusivity when generic modafinil launched in 2012. The original compound patent protection did not prevent long-term generic entry, and later formulation-related patents were resolved through patent litigation and settlement arrangements.
Key U.S. exclusivity events
| Date | Event |
|---|---|
| 1998 | FDA approved Provigil |
| 2002 | Core compound patent protection began to expire |
| 2005-2006 | Cephalon entered settlements with several generic applicants |
| 2007 | FTC challenged certain reverse-payment settlement arrangements |
| 2011 | Teva acquired Cephalon |
| April 2012 | Authorized and/or independent generic modafinil entry began |
| 2012 onward | Brand prescriptions and price declined sharply |
Cephalon’s litigation strategy focused on patents covering modafinil formulations and particle-size characteristics rather than relying only on the original compound patent. Generic manufacturers challenged the relevant patents through Paragraph IV certifications. The settlements delayed broader entry but did not preserve the brand’s market after 2012 (Federal Trade Commission, 2008).
What patents protected Provigil?
Provigil’s original patent estate included compound and formulation protection. The most commercially significant later patent was U.S. Patent No. 5,618,845, which covered pharmaceutical compositions containing modafinil and was listed in connection with the product’s formulation protection.
| Patent or protection category | Relevance to Provigil | Commercial outcome |
|---|---|---|
| U.S. Patent No. 4,927,855 | Core benzhydryl sulfinyl compound protection | Expired before modern generic entry |
| U.S. Patent No. 5,618,845 | Modafinil pharmaceutical composition and formulation protection | Challenged by generic applicants |
| Pediatric exclusivity | Extended certain FDA-listed protection by six months where applicable | Did not create durable post-2012 exclusivity |
| Method-of-use claims | Covered approved wakefulness indications and related use concepts | Less effective against prescriptions outside labeled use |
| Manufacturing and solid-state claims | Could raise process or formulation barriers | Did not prevent generic market formation |
The patent estate was commercially effective at delaying generic entry, but it was not durable after the 2012 launch window. The market has no meaningful remaining U.S. composition-of-matter barrier for ordinary modafinil tablets.
What was the Paragraph IV litigation involving Provigil?
Multiple generic applicants challenged Provigil patents under the Abbreviated New Drug Application process. The key legal issue was whether generic modafinil infringed Cephalon’s listed formulation patents and whether those patents were valid.
The Federal Trade Commission alleged that Cephalon paid or otherwise compensated generic manufacturers to delay entry. The FTC’s case focused on agreements involving companies including Teva, Ranbaxy, Mylan, and Barr Pharmaceuticals. These arrangements became a major antitrust reference point for pharmaceutical reverse-payment litigation (Federal Trade Commission, 2008).
The litigation produced several business outcomes:
- Generic companies received negotiated entry rights.
- Cephalon extended brand revenue beyond the earliest compound-patent expiry.
- Teva inherited the litigation and settlement structure after acquiring Cephalon.
- Generic entry eventually occurred in 2012.
- The legal strategy did not preserve a profitable branded market after generic launch.
What is the Orange Book status of Provigil?
Provigil was listed in the FDA’s Orange Book with patents associated with its approved tablet formulation. The practical significance of the listings declined after generic approvals and the expiration or resolution of the relevant patent claims.
The Orange Book remains relevant for historical patent analysis, but it does not indicate that Provigil retains an active, commercially meaningful exclusivity position today. Generic modafinil products have been approved under ANDAs and are therapeutically substitutable subject to state substitution laws and prescriber or payer controls (FDA, 2024).
How does Provigil compare with Nuvigil and other wakefulness drugs?
Provigil competed most directly with Nuvigil, the brand name for armodafinil. Nuvigil was developed as the R-enantiomer of modafinil and received U.S. approval in 2007. Its market strategy emphasized longer-lasting exposure and a newer patent estate.
| Product | Active ingredient | Brand status | Generic competition | Market position |
|---|---|---|---|---|
| Provigil | Modafinil | Mature legacy brand | Established | Lowest-cost standard option |
| Nuvigil | Armodafinil | Mature legacy brand | Established | Differentiated but largely generic |
| Sunosi | Solriamfetol | Branded | Patent-protected during launch period | Alternative for excessive daytime sleepiness |
| Wakix | Pitolisant | Branded | Limited or absent U.S. generic competition during protection period | Non-stimulant wakefulness alternative |
| Xyrem/Xywav | Sodium oxybate formulations | Branded | Complex formulation and distribution barriers | Narcolepsy-focused, higher-value specialty market |
Provigil’s price advantage is its primary competitive strength. Nuvigil and newer agents can command higher prices but face formulary controls, prior authorization, and specialty-pharmacy requirements. Provigil’s generic status makes it more attractive for cost-sensitive payers and patients who respond adequately to modafinil.
What is the current competitive landscape for modafinil?
The competitive landscape has four layers:
Generic modafinil
Generic modafinil is the principal competitor to branded Provigil. Multiple manufacturers have historically supplied 100 mg and 200 mg tablets. Competition is based on acquisition cost, wholesaler availability, supply continuity, and pharmacy substitution.
Armodafinil
Armodafinil competes on pharmacokinetic differentiation. It may be selected when a prescriber seeks a longer duration or a different response profile, but generic armodafinil has weakened its branded commercial position.
Newer wakefulness products
Pitolisant and solriamfetol compete for patients with excessive daytime sleepiness. Their commercial value is higher because of newer clinical positioning and stronger patent estates, but they typically carry higher payer friction.
Off-label and nonmedical demand
Modafinil has longstanding off-label interest for fatigue, cognition, and alertness. This demand does not translate directly into reimbursed prescription revenue and is constrained by controlled-substance rules, prescriber policy, and online pharmacy enforcement.
What are realistic Provigil sales projections?
A credible projection must separate branded Provigil revenue from the total modafinil market. Branded Provigil is not expected to return to historical blockbuster levels without a new formulation, indication, or commercial relaunch.
Base-case U.S. market projection
The following model estimates the U.S. prescription market for all modafinil products, not Teva’s branded Provigil revenue. It assumes stable diagnosis volumes, modest prescription growth, continued generic substitution, and sustained price pressure.
| Year | Estimated U.S. modafinil market revenue | Expected market condition |
|---|---|---|
| 2024 | $120 million-$180 million | Mature generic market |
| 2025 | $115 million-$175 million | Low-single-digit unit growth, price erosion |
| 2026 | $110 million-$170 million | Continued generic substitution |
| 2027 | $105 million-$165 million | Stable demand, lower average selling price |
| 2028 | $100 million-$160 million | Mature, low-growth market |
| 2029 | $95 million-$155 million | Further price compression |
| 2030 | $90 million-$150 million | Long-term generic equilibrium |
These are market-model estimates rather than reported company sales. The range reflects uncertainty in prescription volume, channel mix, wholesaler inventories, and the number of active generic suppliers.
Brand Provigil projection
| Period | Expected branded Provigil revenue outlook |
|---|---|
| 2025-2026 | De minimis relative to historical sales |
| 2027-2028 | No structural recovery expected |
| 2029-2030 | Continued erosion unless a new commercial strategy changes product positioning |
A reasonable base case assigns branded Provigil less than 5% of the total U.S. modafinil market. Under that assumption, annual U.S. branded revenue would remain below approximately $5 million-$9 million in the 2025-2030 period. This is a residual-brand estimate, not a reported Teva forecast.
What generic launch scenarios exist for Provigil?
Base case: stable generic competition
Generic modafinil remains widely available. Prices decline gradually, and the market grows mainly through diagnosis and prescription volume. This is the most probable scenario.
Downside case: accelerated price erosion
Additional suppliers, wholesaler consolidation, or payer contracting could reduce average selling prices faster than prescription volume grows. Under this scenario, market revenue could fall below $100 million annually by 2030.
Upside case: volume expansion
Growth in diagnosed narcolepsy and sleep apnea-related excessive sleepiness could lift prescription volume. Even in this scenario, revenue growth would be limited because generic prices are low and brand substitution remains extensive.
Supply disruption case
A manufacturing interruption at one or more suppliers could increase short-term pricing and shift market share. Such an event would likely benefit replacement generic suppliers rather than restore Provigil’s branded franchise.
What manufacturing and intellectual-property barriers remain?
The primary barriers are operational rather than patent-based.
| Barrier | Impact |
|---|---|
| Controlled-substance compliance | Requires Schedule IV handling and prescription controls |
| FDA manufacturing compliance | Can affect supply continuity and product availability |
| Active pharmaceutical ingredient sourcing | May create temporary shortages or price movements |
| Bioequivalence requirements | Required for ANDA approval but no longer a major strategic barrier |
| Formulation differentiation | Limited for standard immediate-release tablets |
| Distribution controls | Moderate impact through wholesalers and pharmacies |
| Patent protection | Low for standard modafinil tablets |
No biosimilar pathway applies because modafinil is a chemically synthesized small molecule. Generic manufacturers do not need to reproduce a biologic reference product; they must demonstrate pharmaceutical equivalence and bioequivalence under the ANDA pathway.
What is the revenue exposure for Teva and competitors?
Provigil no longer represents material franchise exposure comparable to the period before generic entry. Teva’s commercial exposure is concentrated in generic modafinil supply and any remaining brand sales, while the principal risk is product-level margin compression rather than loss of a large protected revenue stream.
The highest-value competitive opportunities are in adjacent products:
- Pitolisant for narcolepsy and excessive daytime sleepiness.
- Solriamfetol for obstructive sleep apnea and narcolepsy-related sleepiness.
- Sodium oxybate products for narcolepsy and cataplexy.
- Specialty formulations with restricted distribution or differentiated dosing.
Provigil’s residual value is strongest where a company can manufacture at low cost, maintain reliable supply, and secure pharmacy and payer coverage. Its value is weak as a stand-alone branded asset.
Key Takeaways
- Provigil is a mature, genericized modafinil product with no credible path back to historical blockbuster sales under its current formulation.
- Historical annual sales reached approximately $1 billion or more before generic entry.
- U.S. generic modafinil launched in 2012 after extensive Paragraph IV litigation and settlement activity.
- The current market is driven by generic volume, manufacturing reliability, and price rather than brand differentiation.
- A reasonable 2025-2030 U.S. market estimate for all modafinil products is approximately $90 million-$175 million annually.
- Branded Provigil revenue is likely to remain below 5% of the total U.S. modafinil market.
- Biosimilar risk is irrelevant; the key competitive threat is generic price erosion.
- Newer products such as Wakix and Sunosi offer stronger branded commercial economics but face higher pricing and reimbursement barriers.
- Any investment thesis should focus on generic supply, manufacturing cost, market access, and adjacent wakefulness products rather than Provigil brand growth.
FAQs
Is Provigil still sold in the United States?
Yes. Provigil may remain available as a branded product, but most U.S. prescriptions are expected to be filled with generic modafinil.
Is modafinil still profitable for pharmaceutical manufacturers?
It can be profitable for efficient generic manufacturers with reliable supply and low production costs. Profitability is materially lower than during the branded Provigil period.
Can a new company launch another modafinil generic?
A company can seek FDA approval through the ANDA pathway if it meets pharmaceutical-equivalence, bioequivalence, manufacturing, labeling, and controlled-substance requirements.
Does Provigil have biosimilar competition?
No. Modafinil is a small-molecule drug. Its competition comes from generic equivalents, not biosimilars.
Could Provigil sales increase through a new indication?
A new indication could expand demand, but it would require clinical development, FDA approval, labeling protection, and a commercial strategy capable of overcoming established generic substitution.
References
Cephalon, Inc. (2010). Annual report pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934. U.S. Securities and Exchange Commission.
Federal Trade Commission. (2008). FTC charges Cephalon with illegal anticompetitive conduct to prevent generic competition to Provigil. https://www.ftc.gov
Teva Pharmaceutical Industries Ltd. (2011). Teva to acquire Cephalon for approximately $6.8 billion. Company announcement.
Teva Pharmaceutical Industries Ltd. (2012). Annual report. Company filing.
U.S. Food and Drug Administration. (2015). Provigil (modafinil) prescribing information. FDA.
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
More… ↓
