Share This Page
Drug Sales Trends for METFORMIN
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for METFORMIN (2010)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
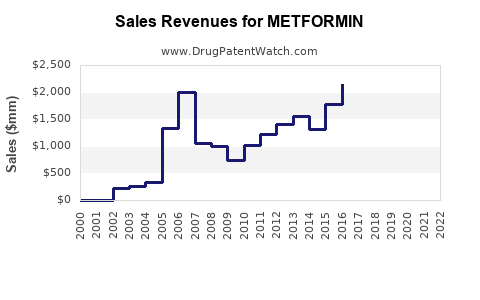
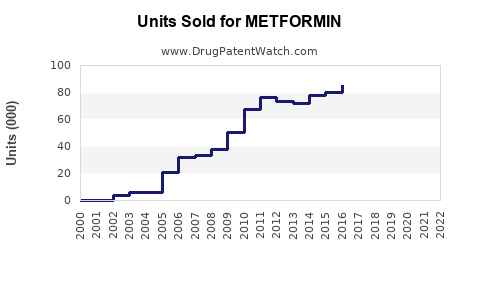
Annual Sales Revenues and Units Sold for METFORMIN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| METFORMIN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| METFORMIN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| METFORMIN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| METFORMIN | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| METFORMIN | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Metformin Market Analysis and Sales Projections Through 2030
Metformin is a mature, high-volume generic medicine with durable demand but limited pricing power. Global product sales are estimated at approximately $1.5 billion to $2.8 billion in 2024, with a base-case forecast of about $2.4 billion by 2030. Growth will come primarily from expanding diabetes prevalence, broader diagnosis and treatment, and continued use in combination regimens. Unit demand should grow faster than revenue because generic prices remain low and competition is intense.
What is the current global market size for metformin?
The 2024 global metformin market is estimated at $2.0 billion in the base case, including immediate-release tablets, extended-release tablets, oral solutions, branded generics, and hospital or institutional supply.
Public companies generally do not report metformin revenue separately. The estimate therefore combines diabetes-treatment prevalence, prescription volume, dosage demand, generic pricing, and branded-product disclosures.
| Metric | 2024 estimate | 2030 base-case estimate |
|---|---|---|
| Global metformin product revenue | $2.0 billion | $2.4 billion |
| Reasonable market range | $1.5-$2.8 billion | $1.8-$3.5 billion |
| Revenue CAGR | - | Approximately 3.0% |
| Volume growth | Approximately 3%-5% annually | Continued growth |
| Price trend | Flat to declining | Low single-digit decline |
| Primary demand driver | Type 2 diabetes treatment | Diabetes prevalence and diagnosis |
| Primary commercial risk | Generic price erosion | Substitution and procurement pressure |
These figures exclude the broader diabetes-drug market, including insulin, GLP-1 receptor agonists, DPP-4 inhibitors, SGLT2 inhibitors, and combination products where metformin revenue is not separately identifiable.
Why is metformin demand expected to grow?
Metformin remains a standard first-line treatment for many patients with type 2 diabetes because of its low cost, long clinical history, broad availability, and generally favorable safety profile when appropriately prescribed. The American Diabetes Association continues to recognize metformin as a commonly used glucose-lowering therapy, although treatment selection is increasingly influenced by cardiovascular, kidney, weight-management, and heart-failure considerations (American Diabetes Association Professional Practice Committee, 2024).
The International Diabetes Federation estimated that 537 million adults aged 20 to 79 were living with diabetes in 2021. That figure is projected to reach 643 million by 2030 and 783 million by 2045 (International Diabetes Federation, 2021). Metformin will not capture all incremental treatment demand, but it is likely to retain a substantial role in initial therapy and combination treatment.
Demand is supported by five structural factors:
- Rising global diabetes prevalence.
- Expanded screening in emerging markets.
- Longer treatment duration as survival improves.
- Continued use with insulin, SGLT2 inhibitors, GLP-1 receptor agonists, and other agents.
- Low cost in markets where newer therapies are unaffordable or unavailable.
Demand is constrained by renal contraindications, gastrointestinal tolerability, treatment discontinuation, and displacement in some patients by newer drugs with weight-loss or cardiovascular benefits.
What are the sales projections for metformin through 2030?
The base case assumes global revenue growth of approximately 3% annually. Volume is expected to grow faster than revenue because average selling prices will continue to decline in competitive generic markets.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $1.5 billion | $2.0 billion | $2.8 billion |
| 2025 | $1.5 billion | $2.1 billion | $2.9 billion |
| 2026 | $1.6 billion | $2.1 billion | $3.1 billion |
| 2027 | $1.6 billion | $2.2 billion | $3.2 billion |
| 2028 | $1.7 billion | $2.3 billion | $3.3 billion |
| 2029 | $1.7 billion | $2.3 billion | $3.4 billion |
| 2030 | $1.8 billion | $2.4 billion | $3.5 billion |
| 2024-2030 CAGR | 3.0% | 3.0% | 3.8% |
The bear case reflects faster generic-price erosion, weaker metformin use in high-income markets, and greater substitution by GLP-1 and SGLT2 therapies. The bull case assumes faster diabetes diagnosis in Asia, Latin America, the Middle East, and Africa, with metformin remaining the lowest-cost foundation therapy.
The revenue outlook is less attractive than the volume outlook. Metformin tablets can experience unit growth while producing flat or declining manufacturer revenue. This pattern is common in mature generic markets where pharmacy benefit managers, public tenders, wholesalers, and hospital systems negotiate aggressively.
Which geographic markets will drive metformin growth?
North America
The United States is a high-volume but highly competitive market. Metformin is available as an inexpensive generic in immediate-release and extended-release forms. Retail prescription volume is substantial, but net prices are low and fragmented across manufacturers, pharmacies, wholesalers, Medicaid, Medicare, and commercial insurers.
The United States should produce low-single-digit unit growth through 2030, while revenue may remain flat. Extended-release formulations, oral solutions, and contract-manufactured private-label products have better pricing potential than standard immediate-release tablets, although the opportunity is limited.
Europe
European demand is supported by aging populations, national diabetes programs, and broad generic substitution. Revenue growth is constrained by centralized procurement, reference pricing, and reimbursement controls. The United Kingdom, Germany, France, Italy, and Spain are important volume markets, but product-level revenue is generally lower than in less regulated markets.
Asia-Pacific
Asia-Pacific is the strongest regional growth opportunity. China and India have large diabetes populations, high generic utilization, and significant domestic manufacturing capacity. Growth will be driven by diagnosis, urbanization, longer treatment duration, and access to primary care.
China and India are also major sources of metformin active pharmaceutical ingredient and finished-dose manufacturing. This creates supply opportunities but limits pricing power because local competition is extensive.
Latin America, the Middle East, and Africa
These markets offer the highest unmet-demand potential but have greater risks involving reimbursement, tender concentration, distribution, currency, and regulatory execution. Metformin’s low price supports broad access, making it one of the more commercially viable diabetes drugs in lower-income markets.
How does metformin compare with newer diabetes drugs?
Metformin has the largest treatment base by patient count but a much lower revenue value per patient than newer branded therapies.
| Drug class | Commercial position | Revenue per patient | Growth outlook |
|---|---|---|---|
| Metformin | First-line and combination therapy | Low | Volume growth, limited revenue growth |
| SGLT2 inhibitors | Cardiovascular and kidney benefits | High | Strong |
| GLP-1 receptor agonists | Glucose control and weight reduction | Very high | Very strong |
| DPP-4 inhibitors | Oral, generally well tolerated | Medium to high | Mature or declining |
| Insulin | Essential for many patients | Medium | Stable to moderate |
GLP-1 receptor agonists and SGLT2 inhibitors may replace metformin in selected patients, especially those with obesity, cardiovascular disease, chronic kidney disease, or a need for substantial weight loss. They are unlikely to eliminate metformin as a low-cost background therapy across the global diabetes population.
The commercial effect is therefore a mix of substitution and combination use. A patient may discontinue metformin after starting a newer therapy, but many patients continue metformin alongside a second or third agent.
What is the FDA regulatory status of metformin?
Metformin hydrochloride is FDA-approved for the management of type 2 diabetes, generally as an adjunct to diet and exercise. U.S. products include immediate-release tablets, extended-release tablets, and oral solutions. The drug is also marketed under numerous generic labels and branded or authorized-generic names.
The FDA has issued safety communications concerning nitrosamine contamination in certain extended-release metformin products. Recalls affected specific manufacturers and lots rather than the entire metformin market. These events increased quality-control requirements for manufacturers and distributors (U.S. Food and Drug Administration, 2020).
Important regulatory characteristics include:
- No remaining new-drug exclusivity that materially protects the core metformin molecule.
- Multiple abbreviated new drug applications for immediate-release and extended-release products.
- Established FDA pathways for generic tablets and oral solutions.
- Ongoing manufacturing obligations involving nitrosamine testing, impurity control, process validation, and supply-chain oversight.
- Potential product-specific regulatory risk for companies that fail to meet dissolution, stability, labeling, or manufacturing requirements.
What patents protect metformin products?
The original metformin composition and basic therapeutic use are no longer commercially protected by enforceable U.S. exclusivity. Generic competition has existed for many years.
| Protection category | Current commercial position |
|---|---|
| Metformin hydrochloride molecule | Long expired |
| Original immediate-release formulation | Long expired |
| Basic type 2 diabetes indication | Long expired |
| Extended-release formulation | Relevant historical patents largely expired or commercially nonblocking |
| Oral solution formulations | Product-specific patents may have existed, but no broad molecule-level barrier remains |
| Manufacturing processes | May be protected in individual jurisdictions but are usually design-around candidates |
| Combination products | May have separate patents tied to the partner drug or formulation |
The FDA Orange Book remains the primary source for current listed patents and exclusivity associated with approved products. For standard generic metformin, the Orange Book does not create a broad patent barrier comparable to those surrounding newer branded diabetes medicines (U.S. Food and Drug Administration, 2024a).
When did metformin lose exclusivity?
Metformin lost meaningful U.S. market exclusivity decades ago. The original branded product, Glucophage, was commercialized by Bristol-Myers Squibb, and generic metformin products entered the U.S. market in the early 2000s. Core compound protection is no longer a factor in launch timing.
Paragraph IV challenges are therefore not a central market event for conventional metformin. A Paragraph IV filing may still arise for a newly approved formulation, delivery system, or combination product, but a generic applicant does not need to defeat a live compound patent to enter the ordinary immediate-release metformin market.
What formulation patents and manufacturing barriers remain?
The main technical barriers relate to product quality rather than molecule ownership.
Extended-release tablets
Extended-release metformin requires controlled dissolution and consistent release over time. Manufacturers must manage polymer selection, granulation, compression, coating, stability, and dissolution specifications. Formulation patents can cover release mechanisms, excipient combinations, tablet architecture, or manufacturing processes, but commercial relevance depends on whether claims remain enforceable and whether an alternative formulation can obtain FDA approval.
Oral solutions
Liquid metformin products can target patients who have difficulty swallowing tablets. They require attention to taste masking, stability, preservative systems, packaging, and dose uniformity. These products have a smaller market than tablets but may command a higher price per treatment course.
Active pharmaceutical ingredient
API production is technically mature, but suppliers must meet current good manufacturing practice, impurity, elemental impurity, and nitrosamine requirements. Supply concentration in China and India creates procurement and geopolitical exposure. API shortages or plant inspections can affect finished-dose availability even when no patent issue exists.
Which companies compete in the metformin market?
The competitive field includes global generic companies, regional manufacturers, contract development and manufacturing organizations, and private-label suppliers.
Commonly associated manufacturers and suppliers include:
- Viatris
- Teva Pharmaceutical Industries
- Sandoz
- Sun Pharmaceutical Industries
- Lupin
- Dr. Reddy’s Laboratories
- Zydus Lifesciences
- Torrent Pharmaceuticals
- Hikma Pharmaceuticals
- Cipla
- Endo and its former Par Pharmaceutical operations
- Regional and private-label manufacturers
Commercial leadership varies by country and channel. A manufacturer can have a meaningful U.S. prescription position without reporting material company-level revenue because metformin represents a small portion of a diversified generic portfolio.
The strongest competitive advantages are usually:
- Reliable API sourcing.
- High manufacturing compliance.
- Low-cost tablet production.
- Strong wholesaler and pharmacy access.
- Multi-country regulatory approvals.
- Ability to supply tenders without quality failures.
- Availability of immediate-release, extended-release, and liquid presentations.
What generic launch risks exist for metformin?
Conventional metformin has low launch risk from an intellectual-property perspective and high execution risk from a commercial perspective.
| Risk | Assessment |
|---|---|
| Compound patent barrier | Very low |
| Orange Book litigation | Low for standard products |
| Regulatory approval | Routine but quality-sensitive |
| Price erosion | High |
| API supply risk | Moderate |
| Recall or impurity risk | Moderate |
| Market access | Competitive |
| Differentiation potential | Limited |
| Margin durability | Weak for standard tablets |
A new entrant may obtain regulatory approval yet struggle to generate attractive returns. The market is crowded, switching costs are low, and buyers often prioritize price and supply reliability. A differentiated extended-release product, oral solution, combination product, or co-pack may offer a better commercial position than another immediate-release tablet.
What is the revenue exposure for branded diabetes companies?
Metformin is strategically important but rarely a major revenue driver for large branded pharmaceutical companies. Its primary economic role is as a high-volume generic base therapy. The largest financial exposure lies with generic manufacturers, API suppliers, wholesalers, and contract manufacturers rather than originator companies.
For diabetes-focused companies, metformin can affect the addressable market for newer therapies. A patient beginning treatment with metformin may later receive an SGLT2 inhibitor, GLP-1 receptor agonist, insulin, or combination therapy. The number of metformin-treated patients is therefore a leading indicator of the broader diabetes-treatment pool, but metformin revenue itself is not a reliable proxy for branded diabetes revenue.
What is the outlook for metformin sales and investment?
Metformin should remain a durable, low-growth pharmaceutical market through 2030. The most likely outcome is rising global volume, stable or modestly increasing nominal revenue, and continuing pressure on manufacturer margins.
The most attractive opportunities are not in the basic molecule. They are in:
- Reliable low-cost API production.
- Emerging-market distribution.
- Extended-release and liquid dosage forms.
- Combination products with newer diabetes agents.
- Contract manufacturing.
- Supply agreements with public health systems.
- Quality systems that reduce recall and shortage risk.
The least attractive opportunity is an undifferentiated immediate-release tablet launch in a saturated market where multiple suppliers already compete on price.
Key Takeaways
- Global metformin product revenue is estimated at about $2.0 billion in 2024.
- Base-case revenue is projected to reach approximately $2.4 billion by 2030.
- Volume growth should exceed revenue growth because generic prices remain under pressure.
- Asia-Pacific is the strongest regional growth market.
- The United States and Europe offer high volume but limited pricing power.
- Compound patents and core exclusivity have expired.
- Paragraph IV litigation is not a material barrier for standard metformin products.
- Formulation, manufacturing, quality, and supply reliability are more important than molecule-level intellectual property.
- GLP-1 and SGLT2 therapies will displace metformin in selected patients but are also likely to be used alongside it.
- Investment returns are more likely in manufacturing efficiency, supply assurance, and differentiated formulations than in basic metformin tablets.
FAQs About the Metformin Market
How much does generic metformin cost?
Generic metformin is among the lowest-cost prescription medicines in major markets. Actual prices vary by strength, formulation, country, payer, pharmacy channel, and procurement contract. Extended-release and liquid formulations generally command higher prices than immediate-release tablets.
Is metformin still the most widely used diabetes drug?
Metformin remains one of the most widely used medicines for type 2 diabetes by patient count. Insulin is essential for many patients, while newer agents may generate substantially higher revenue per patient.
Can a company obtain a patent on a new metformin product?
A company may seek patents for a new formulation, delivery system, combination, manufacturing process, or use. A new patent would not restore exclusivity over the metformin molecule itself.
Will GLP-1 drugs eliminate the metformin market?
No. GLP-1 drugs will replace metformin for some patients, particularly where weight reduction or cardiometabolic benefits are priorities. Low cost and combination use will preserve a substantial metformin market.
What is the biggest commercial threat to metformin manufacturers?
The principal threat is price erosion combined with manufacturing and supply failures. Product quality problems, nitrosamine findings, recalls, and inability to meet tenders can cause more immediate commercial damage than patent litigation.
References
American Diabetes Association Professional Practice Committee. (2024). 9. Pharmacologic approaches to glycemic treatment: Standards of care in diabetes-2024. Diabetes Care, 47(Supplement 1), S158-S178. https://doi.org/10.2337/dc24-S009
International Diabetes Federation. (2021). IDF diabetes atlas (10th ed.). International Diabetes Federation. https://diabetesatlas.org/
U.S. Food and Drug Administration. (2020). FDA updates and press announcements on NDMA in metformin. https://www.fda.gov/
U.S. Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.accessdata.fda.gov/scripts/cder/ob/
U.S. Food and Drug Administration. (2024b). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
World Health Organization. (2023). Global report on diabetes. World Health Organization. https://www.who.int/health-topics/diabetes
More… ↓
