Drug Sales Trends for AZOR
Payment Methods and Pharmacy Types for AZOR (2010)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
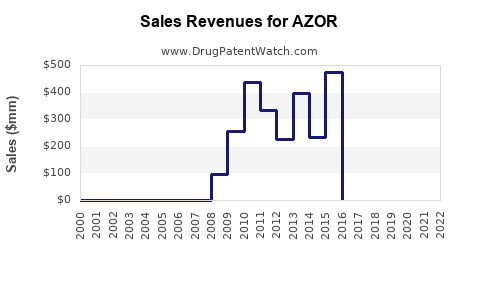
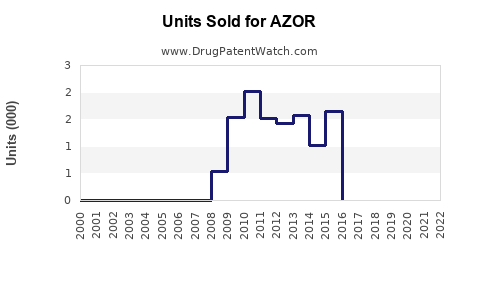
Annual Sales Revenues and Units Sold for AZOR
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| AZOR | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| AZOR | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| AZOR | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
AZOR Market Analysis, Sales Projections, Patent Status, and Generic Competition
AZOR, the fixed-dose combination of amlodipine besylate and olmesartan medoxomil, is a mature antihypertensive product with limited branded commercial value. U.S. revenue is now primarily exposed to generic competition, while the market remains supported by chronic hypertension prevalence and continued use of combination therapy. Daiichi Sankyo does not separately report current AZOR revenue, so a defensible standalone dollar forecast is unavailable from public company filings. The most likely commercial outcome is a low-value, declining branded market and a stable-to-declining generic market through 2029.
What is AZOR and how large is its addressable market?
AZOR is an oral, once-daily fixed-dose combination for hypertension. It combines:
- Amlodipine, a dihydropyridine calcium-channel blocker
- Olmesartan medoxomil, an angiotensin II receptor blocker, or ARB
The product was approved by the U.S. Food and Drug Administration in 2007. Available strengths include 5/20 mg, 5/40 mg, and 10/40 mg of amlodipine/olmesartan, according to the FDA prescribing information.[1]
AZOR competes with separate-pill therapy and other fixed-dose antihypertensive combinations, including:
- Exforge, amlodipine/valsartan
- Lotrel, amlodipine/benazepril
- Tribenzor, olmesartan/amlodipine/hydrochlorothiazide
- Exforge HCT, amlodipine/valsartan/hydrochlorothiazide
- Generic amlodipine, olmesartan, losartan, valsartan, and combination products
The addressable market is broad because hypertension is a chronic condition requiring long-term treatment. The commercial opportunity for AZOR is narrower because physicians can prescribe the two components separately at lower cost and because generic alternatives are widely available.
What are the main demand drivers?
Demand is supported by several factors:
- Persistent hypertension prevalence in the United States and other developed markets.
- Clinical preference for combination therapy when a single agent does not achieve blood-pressure targets.
- Adherence benefits from once-daily fixed-dose combinations.
- Generic availability of both active ingredients.
- Continued use in patients already stabilized on amlodipine and olmesartan.
The main constraints are price erosion, therapeutic substitution, formulary restrictions, and the availability of separate generic tablets. AZOR has no meaningful differentiation in mechanism, dosing convenience, or delivery technology that would support premium pricing after generic entry.
What are AZOR sales and revenue projections?
Daiichi Sankyo has historically reported sales for its Benicar franchise and related products, but public filings have not consistently isolated AZOR revenue from Benicar, Benicar HCT, and other U.S. antihypertensive products.[2] As a result, historical AZOR revenue cannot be reconstructed reliably from company-reported figures alone.
The commercially relevant forecast is therefore an indexed market projection rather than a precise dollar estimate.
AZOR U.S. market projection
| Year | Branded AZOR sales outlook | Generic amlodipine/olmesartan market index | Primary market condition |
|---|---|---|---|
| 2024 | Negligible | 100 | Mature generic market |
| 2025 | Negligible | 98-101 | Stable demand, price pressure |
| 2026 | Near zero | 96-100 | Additional formulary substitution |
| 2027 | Near zero | 94-99 | Unit demand stable; price erosion continues |
| 2028 | Near zero | 92-98 | Low-cost generic dominance |
| 2029 | Near zero | 90-97 | Mature, commoditized market |
The index represents estimated generic market value, with 2024 set at 100. It is not a reported IQVIA or company-sales figure. The range reflects the difference between relatively stable prescription volume and declining average selling prices.
What is the likely branded sales scenario?
The base case is that U.S. branded AZOR revenue remains immaterial through 2029. The product lacks the characteristics that typically sustain a branded premium after loss of exclusivity:
- No biologic manufacturing complexity
- No specialty distribution requirement
- No orphan-drug market
- No clinically distinct delivery system
- No meaningful switching barrier
- No protected patient population large enough to offset generic substitution
A residual branded market could persist through cash-pay demand, legacy prescribing, limited formulary coverage, or patients who remain on the branded product. That market should be measured in a small fraction of the historical franchise rather than as a growth business.
What are the key revenue sensitivities?
The forecast is most sensitive to:
- Generic reimbursement rates
- Medicaid and Medicare formulary decisions
- Wholesale acquisition cost reductions
- Generic manufacturer exits or shortages
- Physician adoption of single-pill combinations
- Relative pricing between generic AZOR and separate generic components
Volume could remain stable while value declines. This distinction is important because hypertension treatment demand is durable, but branded revenue is not.
When did AZOR lose exclusivity?
AZOR lost the practical protection associated with its brand franchise when generic versions of the amlodipine/olmesartan combination entered the market. The core active ingredients were already individually available as generics, which reduced the commercial value of any remaining combination-product protection.
The relevant exclusivity framework is:
| Protection category | AZOR relevance | Commercial effect |
|---|---|---|
| New chemical entity exclusivity | Not available for the fixed-dose combination in the current market | No durable protection |
| Five-year chemical-entity exclusivity | Applies to qualifying new active ingredients, not an established combination in this context | Not a current barrier |
| Three-year clinical-investigation exclusivity | Could apply to qualifying supplemental approvals | Limited and time-limited |
| Patent protection | Potentially covered formulation or combination claims | No current branded moat of material value |
| Pediatric exclusivity | Could extend listed protection by six months if granted | Historical only where applicable |
| Regulatory exclusivity | No current meaningful exclusivity barrier | Generic competition permitted |
The FDA approved generic amlodipine and olmesartan combination products through the abbreviated new drug application pathway. Current prescribing information and generic availability are reflected in FDA and DailyMed records.[1,3]
What patents protect AZOR?
AZOR was protected primarily through patents covering the composition and pharmaceutical combination rather than through a complex formulation platform. The relevant patent estate historically included patents associated with olmesartan medoxomil and fixed-dose combinations with amlodipine.
A practical patent review must distinguish three layers:
Olmesartan compound patents
The underlying olmesartan medoxomil compound patents protected the active ingredient used in Benicar and related products. Those patents were central to the broader Daiichi Sankyo antihypertensive franchise but did not provide a durable post-generic barrier for AZOR.
Combination-product patents
Combination patents could cover the use or composition of olmesartan with amlodipine. Their commercial value depended on claim scope, expiration, pediatric extensions, and whether ANDA applicants faced enforceable Orange Book-listed claims.
Method-of-use patents
Method-of-use claims could cover treating hypertension with the combination or particular patient populations. Such claims are generally narrower than composition claims and can be challenged through a Paragraph IV certification or carved out through a Section viii statement, depending on the listed indication and patent language.
No current patent protection appears capable of restoring meaningful branded exclusivity for AZOR in the U.S. market. The product’s commercial position is consistent with a mature, genericized small-molecule combination.
What is the Orange Book status of AZOR?
The FDA Orange Book identifies approved drug products, patent listings, and relevant exclusivity information. AZOR’s current commercial status should be assessed through the Orange Book entry for the specific brand and strength, together with the approved ANDA products for amlodipine besylate and olmesartan medoxomil.[4]
The relevant regulatory points are:
- AZOR is an NDA-approved fixed-dose combination.
- Generic equivalents may be approved under ANDA procedures.
- Orange Book patent listings do not create indefinite protection.
- Listed patents can be challenged through Paragraph IV certifications.
- A generic applicant may omit a patented method of use through a Section viii statement where permitted.
- FDA approval does not itself guarantee commercial launch if litigation, settlement, or other legal restrictions remain.
Because AZOR is a small-molecule product, biosimilar rules do not apply. The applicable competitive pathway is generic substitution, not the abbreviated pathway used for biosimilars.
Which companies are challenging or competing with AZOR?
Competition comes from generic manufacturers rather than from a single branded challenger. Potential suppliers of generic amlodipine/olmesartan products include large ANDA companies and contract manufacturers active in cardiovascular medicines. Market participation can change as manufacturers enter or exit based on pricing and manufacturing economics.
The principal competitive groups are:
| Competitive group | Products | Strategic effect |
|---|---|---|
| Generic combination suppliers | Amlodipine/olmesartan tablets | Direct substitution for AZOR |
| Generic component suppliers | Amlodipine and olmesartan tablets | Lower-cost separate-pill therapy |
| Branded ARB combinations | Exforge, Lotrel, related products | Therapeutic substitution |
| Triple combinations | Tribenzor and generic alternatives | Escalation for patients needing three agents |
| Retail and mail-order pharmacies | Generic substitution programs | Accelerated brand erosion |
| Health plans and PBMs | Formulary-preferred generics | Pricing pressure |
The competitive threat is not dependent on a single Paragraph IV challenger. Multiple generic suppliers and therapeutic alternatives make coordinated price protection difficult.
What AZOR litigation and settlement risks exist?
AZOR-related litigation risk historically centered on ANDA applicants certifying that listed patents were invalid, unenforceable, or not infringed. Paragraph IV litigation can delay approval or launch, but that risk diminishes sharply after relevant patents expire or become commercially irrelevant.
For a mature product, the main legal questions are:
- Whether any Orange Book-listed patent remains unexpired
- Whether an ANDA applicant filed a Paragraph IV certification
- Whether the patent holder sued within the statutory period
- Whether the parties entered a launch-date settlement
- Whether any settlement was submitted for Federal Trade Commission review
- Whether authorized generic supply arrangements affect market entry
No publicly established settlement structure should be assumed to support a material current AZOR revenue stream. Historical settlements, if any, would have had value only during the period before broad generic substitution.
How strong is the AZOR patent estate?
AZOR has a weak current patent estate from a commercial perspective.
| Patent-strength factor | Assessment |
|---|---|
| Active-ingredient protection | Expired or no longer commercially decisive |
| Combination protection | Limited by maturity and generic approval |
| Formulation differentiation | Low |
| Manufacturing complexity | Low to moderate |
| Method-of-use protection | Narrow and potentially carve-out susceptible |
| Biosimilar barrier | Not applicable |
| Switching costs | Low |
| Generic substitution risk | High |
| Litigation leverage | Low after loss of enforceable market exclusivity |
The remaining barriers are operational rather than legal. They include manufacturing approvals, quality-system compliance, supply reliability, FDA inspection outcomes, and the ability to maintain acceptable margins.
What manufacturing and intellectual-property barriers affect AZOR?
AZOR does not require biologic production, sterile manufacturing, or a specialized delivery device. The manufacturing process involves conventional oral solid-dose production, including active-ingredient sourcing, blending, compression, coating where applicable, dissolution testing, and stability control.
Potential barriers include:
- Reliable supply of olmesartan medoxomil
- Control of impurity profiles
- Bioequivalence testing
- Consistent dissolution performance
- Stability across the approved shelf life
- Compliance with current good manufacturing practices
- FDA inspection and remediation requirements
These barriers can produce temporary shortages or supplier exits, but they do not create durable pricing power. Generic manufacturers with established cardiovascular portfolios are positioned to manage them more efficiently.
How does AZOR compare with competing antihypertensive products?
| Product or therapy | Active ingredients | Commercial position |
|---|---|---|
| AZOR | Amlodipine/olmesartan | Mature, genericized fixed-dose combination |
| Exforge | Amlodipine/valsartan | Branded legacy product with generic competition |
| Lotrel | Amlodipine/benazepril | Genericized ACE inhibitor combination |
| Tribenzor | Amlodipine/olmesartan/hydrochlorothiazide | More complex triple therapy |
| Separate generics | Amlodipine plus olmesartan | Main low-cost substitute |
| Single-agent ARBs | Losartan, valsartan, olmesartan | Broad therapeutic substitutes |
AZOR’s advantage is pill burden reduction. Its disadvantage is the lack of meaningful economic or clinical differentiation after generic entry.
What generic launch scenarios exist for AZOR?
Base case
Generic products remain available from several suppliers. Prescription volume is stable or modestly lower, while net prices decline. Branded AZOR sales remain negligible.
Upside case
Combination-pill adherence improves and payers favor generic fixed-dose combinations over separate tablets. Unit demand increases, but the benefit accrues primarily to generic manufacturers and pharmacies rather than the brand owner.
Downside case
Manufacturing disruptions, supplier exits, or quality-related recalls reduce availability. Temporary shortages could raise generic prices, but the effect would likely be short-lived because other generic suppliers and separate component products can substitute.
Key Takeaways
- AZOR is a mature fixed-dose combination of amlodipine besylate and olmesartan medoxomil.
- The U.S. branded market has little remaining commercial value.
- Daiichi Sankyo does not separately disclose current AZOR revenue, preventing a reliable standalone dollar forecast.
- Generic competition is the dominant market force through 2029.
- Generic market value is likely to decline modestly even if prescription volume remains relatively stable.
- The patent estate is commercially weak after loss of effective exclusivity.
- Paragraph IV litigation and settlement risk are limited compared with the product’s earlier lifecycle.
- AZOR has no biosimilar risk because it is a small-molecule drug.
- Manufacturing and supply reliability, not intellectual-property strength, are the principal remaining barriers.
- The most likely launch scenario is continued generic substitution with negligible branded revenue.
FAQs About AZOR Sales, Patents, and Market Competition
Is AZOR still sold in the United States?
AZOR may remain listed or available through residual channels, but its commercial importance is limited because generic amlodipine/olmesartan products and separate generic components are available.
Does AZOR have biosimilar competition?
No. AZOR is a small-molecule oral drug. Its competitors are generic products approved through the ANDA pathway.
What is the main commercial risk for AZOR?
The main risk is generic price erosion. Even stable hypertension demand does not protect brand revenue once payers and pharmacies substitute lower-cost equivalents.
Can AZOR regain premium pricing through a new formulation?
A new formulation could support separate intellectual-property protection only if it delivered a clinically meaningful and non-obvious technical improvement. The existing product has no evident formulation attribute that supports such a strategy.
Is AZOR attractive for licensing or acquisition?
The product is unlikely to support a high-value brand acquisition. A transaction could make sense for a low-cost generic manufacturer with existing manufacturing capacity, a regional supply gap, or a portfolio strategy focused on cardiovascular fixed-dose combinations.
References
- U.S. Food and Drug Administration. (2007). AZOR prescribing information: Amlodipine besylate and olmesartan medoxomil tablets. FDA.
- Daiichi Sankyo Co., Ltd. (Various years). Annual reports and securities reports. Daiichi Sankyo.
- National Library of Medicine. (n.d.). DailyMed: Amlodipine besylate and olmesartan medoxomil tablets. U.S. National Library of Medicine.
- U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations, Orange Book. FDA.
More… ↓
