Share This Page
Drug Sales Trends for RELPAX
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for RELPAX (2009)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
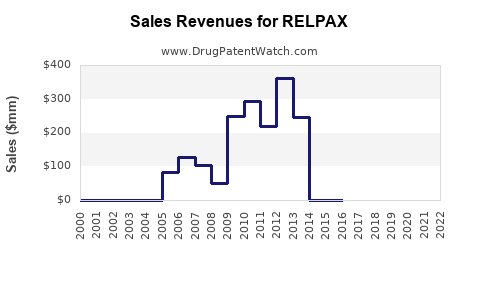
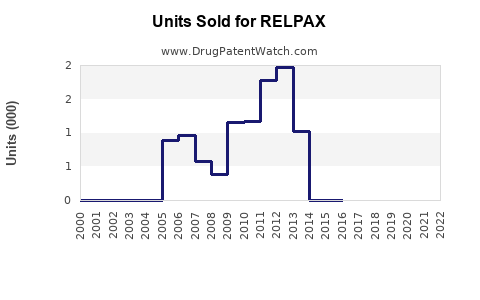
Annual Sales Revenues and Units Sold for RELPAX
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| RELPAX | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| RELPAX | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| RELPAX | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Relpax Market Analysis and Sales Projections: Eletriptan Revenue, Generic Competition, and Patent Risk
Relpax is Pfizer’s brand of eletriptan hydrobromide, an oral 5-HT1B/1D agonist approved for the acute treatment of migraine with or without aura. Its commercial value is now limited by generic eletriptan, mature triptan competition, and the absence of meaningful remaining U.S. exclusivity. Relpax should be analyzed as a declining legacy brand rather than a growth product.
Public Pfizer filings do not separately disclose current Relpax revenue. The most defensible forecast is a low-single-digit-million-dollar annual U.S. brand opportunity, with the broader eletriptan market remaining larger but heavily genericized.
What is Relpax and how large is its addressable market?
Relpax contains eletriptan hydrobromide and is supplied in 20 mg and 40 mg tablets. The FDA approved Relpax in December 2002 for acute migraine treatment in adults. The product is not indicated for migraine prevention or for the treatment of cluster headache.[1]
Eletriptan competes with:
- Sumatriptan, including tablets, nasal spray and injection
- Rizatriptan, marketed as Maxalt and available generically
- Zolmitriptan
- Naratriptan
- Frovatriptan
- Dihydroergotamine products
- CGRP antagonists, including Ubrelvy, Nurtec ODT and Zavzpret
- Preventive CGRP antibodies and oral preventive therapies
The addressable market has two separate layers:
- The total acute migraine prescription market, which includes triptans and newer gepants.
- The eletriptan-specific market, which is substantially smaller and primarily generic.
The branded migraine market has shifted toward CGRP therapies because these products can be used in patients who do not respond adequately to triptans or who have triptan-related tolerability and cardiovascular limitations. Relpax remains relevant for patients who respond to eletriptan, but physician switching and payer substitution favor low-cost generic triptans.
What is the FDA regulatory status of Relpax?
Relpax remains an FDA-approved prescription product for acute migraine. The approved dosage strengths are 20 mg and 40 mg tablets.[1]
| Regulatory attribute | Relpax status |
|---|---|
| Active ingredient | Eletriptan hydrobromide |
| Dosage form | Oral tablet |
| Strengths | 20 mg and 40 mg |
| FDA approval | December 2002 |
| Indication | Acute treatment of migraine with or without aura |
| Prevention indication | No |
| Controlled substance | No |
| Biologic | No |
| Reference-listed drug | Yes |
| Generic pathway | ANDA, Section 505(j) |
| Biosimilar exposure | None |
Relpax is a conventional small-molecule drug. Biosimilar risk does not apply. Competition enters through abbreviated new drug applications rather than the 351(k) biosimilar pathway.
What patents protect Relpax and when did exclusivity end?
Relpax’s primary protection was based on small-molecule composition and related pharmaceutical claims. The core U.S. patent estate is no longer an effective commercial barrier to generic entry.
The relevant exclusivity profile is:
| Protection type | Commercial status |
|---|---|
| New chemical entity exclusivity | Expired |
| Original product patent protection | Expired or no longer commercially blocking |
| Pediatric exclusivity | Historical, if applicable |
| Formulation protection | No known current barrier capable of sustaining branded exclusivity |
| Method-of-use protection | No material current barrier for the approved acute-migraine use |
| Regulatory exclusivity | Expired |
| Current U.S. generic blocking position | None apparent from the mature generic market |
FDA’s Orange Book identifies patents and exclusivity associated with approved reference products, but an Orange Book listing does not itself prevent a generic applicant from filing a Paragraph IV certification. Relpax’s commercial position reflects the practical consequence of expired core protection: multiple generic manufacturers can compete on price and formulary access.[2]
No current patent strategy appears capable of restoring broad exclusivity for the original Relpax product. A new dosage form, delivery system or narrowly defined use could theoretically create separate protection, but no material relaunch strategy of that type is publicly established.
How many generic companies challenge or compete with Relpax?
Generic eletriptan has been available in the U.S. market for several years. The competitive field includes manufacturers that have received FDA approval for eletriptan hydrobromide tablets or have supplied the product through abbreviated approval pathways.
The market structure is typical of an off-patent oral tablet:
- The reference brand retains limited prescription visibility.
- Generic substitution is routine where state law and payer policy permit it.
- Wholesale acquisition price is materially below branded pricing.
- Pharmacy benefit managers have little reason to prefer Relpax unless the manufacturer offers a substantial rebate.
- Supply can consolidate among a small number of active manufacturers despite broader approval counts.
Paragraph IV litigation was relevant during the historical patent-challenge period, before generic market entry. It is no longer the principal commercial issue. The present risk is generic substitution, contracting pressure and pharmacy-level switching rather than an unresolved patent case.
What is the Orange Book status of Relpax?
Relpax is a reference-listed drug in the FDA’s Orange Book framework. The Orange Book is relevant for three reasons:
- It identifies the reference product and approved strengths.
- It records listed patents and exclusivity information.
- It establishes the regulatory reference for ANDA applicants.
For current commercial analysis, the key Orange Book conclusion is that Relpax no longer has effective regulatory exclusivity. Generic eletriptan applicants do not face the type of active exclusivity barrier that protects a recently approved small molecule.
A historical patent listing should not be treated as evidence of current market protection. Patent expiration, terminal disclaimers, pediatric extensions and litigation outcomes determine whether a listed patent remains commercially relevant.
How strong is the Relpax patent estate?
The current patent estate is weak from a revenue-protection perspective.
Composition protection
Composition patents drove the early value of eletriptan. Those rights have expired for the U.S. market, eliminating the principal barrier to generic tablets.
Formulation patents
Relpax is an immediate-release oral tablet. The dosage form is technically straightforward compared with extended-release systems, injectors, inhaled products or complex drug-device combinations. No major formulation feature appears to create a durable barrier to generic substitution.
Method-of-use patents
The approved use, acute migraine treatment, is broad and mature. Method-of-use claims covering this indication have limited ability to exclude generic sales when generic labeling is appropriately structured and the relevant claims are expired or not enforceable.
Manufacturing and chemistry barriers
Eletriptan does not appear to have a manufacturing profile that creates a major commercial barrier comparable with biologics, antibody-drug conjugates, sterile injectables or complex peptide products. Active pharmaceutical ingredient production, tablet manufacture and quality control are commercially manageable for experienced generic suppliers.
Overall patent strength:
| Category | Current strength |
|---|---|
| Core composition protection | Low |
| Formulation protection | Low |
| Method-of-use protection | Low |
| Manufacturing complexity | Low to moderate |
| Generic substitution resistance | Low |
| Ability to support premium pricing | Low |
What sales did Relpax generate and why are current sales difficult to measure?
Pfizer historically reported Relpax as part of its prescription pharmaceutical portfolio, but recent public filings do not provide a reliable standalone revenue series for the product. Pfizer’s reporting has focused on major brands and products with material current revenue contributions. Relpax is not generally presented as a significant separately reported growth asset in recent filings.[3]
The lack of current standalone disclosure has four implications:
- Historical peak sales cannot be extrapolated directly.
- Brand and generic eletriptan revenue are not interchangeable.
- U.S. pharmacy claims data would be needed for a precise prescription and market-share estimate.
- Published third-party market figures may represent gross sales, net sales, manufacturer revenue or pharmacy spending, which are not comparable.
Relpax’s historical commercial decline reflects three forces:
- Loss of exclusivity and generic entry.
- Mature competition from lower-cost triptans.
- Migration of some patients and physicians to CGRP-targeted acute treatments.
What are the Relpax sales projections for 2025 through 2029?
The following forecast is a scenario model for U.S. brand sales, not Pfizer guidance. It assumes no major relaunch, no new indication, no new delivery system and no material pricing strategy that reverses generic substitution.
U.S. branded Relpax revenue forecast
| Year | Bear case | Base case | Upside case |
|---|---|---|---|
| 2025 | $0.5 million | $2.0 million | $5.0 million |
| 2026 | $0.3 million | $1.5 million | $4.0 million |
| 2027 | $0.2 million | $1.1 million | $3.2 million |
| 2028 | $0.1 million | $0.8 million | $2.6 million |
| 2029 | Less than $0.1 million | $0.6 million | $2.0 million |
The base case implies a compound annual decline of approximately 25% from 2025 to 2029. The upside case requires persistent prescriber loyalty, limited generic availability in certain channels, or a targeted commercial program. It does not represent a likely return to branded growth.
Broader U.S. eletriptan market
The total U.S. market for eletriptan, including generic products, should remain materially larger than Relpax brand revenue. A reasonable planning range is:
| Year | Estimated total eletriptan market |
|---|---|
| 2025 | $15 million-$40 million |
| 2026 | $14 million-$38 million |
| 2027 | $13 million-$36 million |
| 2028 | $12 million-$34 million |
| 2029 | $11 million-$32 million |
These ranges represent commercial planning estimates rather than reported industry totals. They reflect generic pricing, declining triptan utilization in some segments and continued persistence of eletriptan among established responders.
The market’s value will be concentrated in generic volume, not branded price. Manufacturer revenue will depend on supply contracts, wholesaler discounts, manufacturing cost and the number of active suppliers.
Which companies are challenging Relpax commercially?
The most significant challengers are not competing originator brands. They are generic eletriptan suppliers and alternative migraine therapies.
Generic competitors
Generic manufacturers can compete through:
- Lower acquisition cost
- Pharmacy benefit manager formulary placement
- National wholesaler distribution
- Retail substitution
- Supply reliability
- Authorized or private-label arrangements
The identity and market share of active suppliers can change over time as manufacturers enter, exit or suspend production. Approval alone does not establish meaningful commercial share.
Therapeutic competitors
The most relevant branded alternatives include:
- Ubrelvy, from AbbVie
- Nurtec ODT, from Pfizer following the Biohaven transaction
- Zavzpret, from Pfizer
- Maxalt and generic rizatriptan
- Imitrex and generic sumatriptan
- Qulipta for prevention, although it is not a direct acute-treatment substitute
CGRP antagonists can command substantially higher prices than generic eletriptan, but their commercial adoption depends on payer coverage, prior authorization and patient response. Relpax retains an economic advantage when a low-cost triptan provides adequate control.
What licensing deals affect Relpax?
Relpax is a Pfizer-originated product and is not associated with a major current licensing transaction that materially changes its market outlook. Pfizer’s broader migraine portfolio has changed through acquisitions, including its acquisition of Biohaven, but that transaction relates primarily to Nurtec ODT and related CGRP assets rather than an expansion of Relpax exclusivity.[4]
No publicly established licensing arrangement appears likely to create a new commercial platform for Relpax. Any value from the product is therefore tied to residual brand demand, legacy prescriber use and possible portfolio rationalization.
What litigation and settlement risks affect Relpax?
The primary litigation risk was historical ANDA patent litigation connected with generic entry. That risk has largely converted into ordinary generic competition.
Current commercial risk is more likely to arise from:
- Product liability claims
- Manufacturing or supply disputes
- Labeling or pharmacovigilance matters
- Contract disputes with distributors or licensees
- Patent disputes involving a new formulation or delivery technology
No active, high-value patent dispute is central to the current Relpax investment case through June 2024. Historical settlement agreements, if any, should be evaluated against actual generic launch dates rather than settlement language alone.
What generic launch scenarios exist for Relpax?
Base scenario
Generic eletriptan remains widely available. Relpax becomes a low-volume legacy brand with annual U.S. sales below $2 million by the end of the forecast period.
Downside scenario
Pfizer reduces commercial support or discontinues branded distribution. Pharmacies substitute generic eletriptan almost universally, driving brand revenue toward immaterial levels.
Upside scenario
One or more generic suppliers experience shortages, or a subset of neurologists continues prescribing Relpax for patients with favorable response histories. Brand revenue remains measurable but does not exceed low-single-digit millions annually.
Strategic relaunch scenario
A reformulated product, orally disintegrating tablet, combination product or differentiated delivery system obtains protection and payer support. This would be a new product strategy rather than a continuation of the existing Relpax business. No such strategy is publicly established.
How does Relpax compare with newer migraine drugs?
| Product class | Representative products | Patent position | Price profile | Competitive effect on Relpax |
|---|---|---|---|---|
| Generic triptans | Eletriptan, sumatriptan, rizatriptan | Expired | Low | Direct price competition |
| Relpax brand | Eletriptan | Expired | High relative to generic | Residual brand loyalty only |
| Acute gepants | Ubrelvy, Nurtec ODT, Zavzpret | Active branded estates | High | Clinical substitution |
| Preventive CGRP products | Qulipta, Aimovig, Emgality, Ajovy | Active branded estates | High | Reduces attack frequency and acute-treatment demand |
| Dihydroergotamine | Trudhesa and other products | Product-specific | Moderate to high | Niche alternative |
Relpax’s advantage is low expected treatment cost when generic. Its disadvantages are an aging clinical profile, generic substitution and limited differentiation from other triptans.
Key Takeaways
- Relpax is the branded eletriptan product originally developed and marketed by Pfizer.
- FDA approval covers 20 mg and 40 mg tablets for acute migraine treatment.
- Core U.S. patent and regulatory exclusivity have expired.
- Generic eletriptan is the principal commercial competitor.
- Biosimilar risk is irrelevant because eletriptan is a small molecule.
- Current branded Relpax sales are not separately disclosed and are likely immaterial relative to Pfizer’s overall revenue.
- Base-case U.S. brand revenue declines from about $2 million in 2025 to less than $1 million by 2029.
- The broader eletriptan market may remain in the $11 million-$40 million annual range, depending on generic volume and pricing.
- CGRP antagonists create the main clinical and commercial substitution risk.
- The product has low current patent strength and limited potential to support premium pricing without a new formulation or delivery strategy.
FAQs About Relpax Market Size and Exclusivity
Is Relpax still sold in the United States?
Relpax remains an FDA-approved product, but commercial availability and pharmacy stocking may vary. Generic eletriptan is the dominant lower-cost alternative.
Is eletriptan a profitable generic drug?
It can generate profitable revenue for efficient suppliers, but profitability depends on manufacturing cost, active supplier count, contract pricing and supply reliability. It is not a high-margin branded opportunity.
Does Relpax have patent protection in Europe?
Patent status is jurisdiction-specific. Core protection for an old small molecule such as eletriptan is generally expired or substantially weakened in major European markets, but national registers control the legal position in each country.
Can Pfizer launch a new Relpax formulation?
A new formulation could receive separate patent protection if it meets novelty and non-obviousness requirements. The new product would need its own regulatory, clinical, manufacturing and reimbursement strategy.
Are CGRP drugs likely to eliminate eletriptan sales?
No. Generic triptans remain economically attractive and clinically effective for many patients. CGRP products will continue to take share in patients with inadequate response, contraindications, tolerability problems or a preference for newer therapies.
References
-
U.S. Food and Drug Administration. (2002). Relpax (eletriptan hydrobromide) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
Pfizer Inc. (2024). Annual report for the fiscal year ended December 31, 2023. Pfizer Inc.
-
Pfizer Inc. (2022). Pfizer completes acquisition of Biohaven Pharmaceuticals. Pfizer Inc.
More… ↓
