Share This Page
Drug Sales Trends for fenofibrate
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for fenofibrate (2008)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
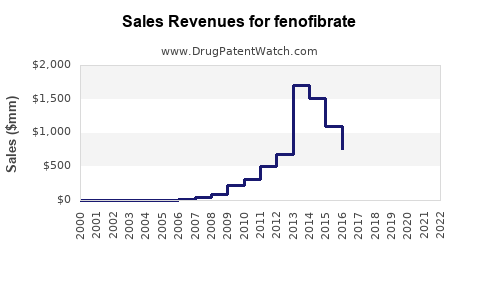
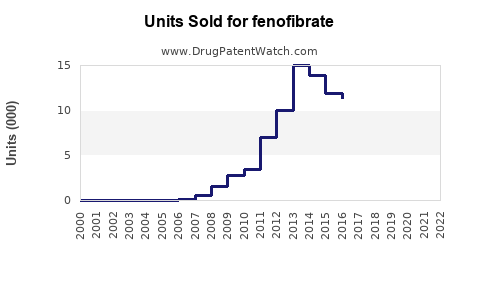
Annual Sales Revenues and Units Sold for fenofibrate
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| FENOFIBRATE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| FENOFIBRATE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| FENOFIBRATE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| FENOFIBRATE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| FENOFIBRATE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Fenofibrate Market Analysis, Sales Projections, Patent Expiry, and Generic Competition
Fenofibrate is a mature, largely generic lipid-lowering drug with stable prescription demand but limited pricing power. The market is driven by chronic treatment of hypertriglyceridemia and mixed dyslipidemia, while competition from statins, prescription omega-3 products, PCSK9 inhibitors, and newer cardiometabolic therapies limits growth. The base-case outlook is declining low-single-digit annual sales through 2029 as generic prices fall and branded volume continues to migrate to low-cost suppliers.
What is the current market position of fenofibrate?
Fenofibrate is a peroxisome proliferator-activated receptor alpha, or PPAR-alpha, agonist. It lowers triglycerides and can increase high-density lipoprotein cholesterol. The drug is available in multiple oral formulations, including capsules and tablets, with several strengths and release technologies.
The leading historical brands include:
- Tricor, marketed by Abbott and later AbbVie
- Trilipix, a fenofibric acid product associated with Abbott
- Antara
- Lipofen
- Triglide
- Generic fenofibrate tablets and capsules
The commercial market is now dominated by generic fenofibrate. Brand products retain limited value in some channels through legacy prescribing, payer formulary positioning, or manufacturer contracting.
Fenofibrate demand remains linked to:
- Severe hypertriglyceridemia and pancreatitis-risk management.
- Mixed dyslipidemia when triglycerides remain elevated.
- Patients who are intolerant of, or inadequately controlled by, statin therapy.
- Combination treatment with statins in selected patients.
The American College of Cardiology and American Heart Association treatment framework places statins and lifestyle intervention at the center of atherosclerotic cardiovascular disease risk reduction. Fenofibrate is used more selectively, particularly when triglycerides are substantially elevated. The FDA label states that fenofibrate has not been shown to reduce coronary heart disease morbidity and mortality in large clinical outcomes studies [1].
How large is the fenofibrate market?
No single public source reports consolidated global revenue for all fenofibrate formulations, manufacturers, countries, hospital channels, and private-label suppliers. A practical market estimate therefore requires a prescription-volume and net-price model.
Modeled 2024 market range
| Market | Estimated annual prescriptions or treatment equivalents | Modeled net revenue |
|---|---|---|
| United States | 20 million to 28 million 30-day equivalents | $180 million to $420 million |
| Europe | 20 million to 35 million treatment equivalents | $180 million to $400 million |
| Japan and other developed markets | 15 million to 25 million treatment equivalents | $150 million to $350 million |
| Emerging markets | 35 million to 70 million treatment equivalents | $250 million to $600 million |
| Global total | 90 million to 158 million treatment equivalents | $760 million to $1.77 billion |
These values are analytical market ranges rather than reported manufacturer revenue. The broad range reflects differences in generic pricing, tender procurement, reimbursement systems, dose strength, formulation, and whether sales are measured at manufacturer, wholesaler, pharmacy, or patient-pay level.
The United States has substantial prescription volume but relatively low generic prices. Emerging markets can generate higher unit volume but lower average selling prices. Branded fenofibrate contributes only a small portion of global molecule sales.
What are the fenofibrate sales projections through 2029?
The base case assumes declining US and European prices, stable-to-slightly declining treatment volume, modest growth in emerging markets, and continued substitution toward low-cost generic suppliers.
Global fenofibrate sales projection
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $760 million | $1.10 billion | $1.77 billion |
| 2025 | $710 million | $1.06 billion | $1.79 billion |
| 2026 | $660 million | $1.02 billion | $1.80 billion |
| 2027 | $610 million | $990 million | $1.82 billion |
| 2028 | $565 million | $960 million | $1.84 billion |
| 2029 | $525 million | $930 million | $1.86 billion |
| 2024-2029 CAGR | -6.9% | -3.3% | 1.0% |
The base case implies that global fenofibrate sales decline by about 15% from 2024 to 2029. The decline is mainly a price effect. Prescription demand should remain comparatively resilient because hypertriglyceridemia is chronic and fenofibrate remains inexpensive.
United States sales projection
| Year | Base-case US market |
|---|---|
| 2024 | $300 million |
| 2025 | $292 million |
| 2026 | $283 million |
| 2027 | $275 million |
| 2028 | $267 million |
| 2029 | $259 million |
The US base case assumes a prescription volume decline of approximately 0.5% to 1.5% annually and a net-price decline of approximately 2% to 4% annually. A faster decline would occur if additional manufacturers enter low-volume dosage forms or if payers consolidate purchasing through larger generic contracts.
Which factors will drive fenofibrate demand?
Persistent use in severe hypertriglyceridemia
Fenofibrate retains a clear clinical role in patients with very high triglycerides, particularly when the treatment objective includes reducing pancreatitis risk. This population is smaller than the broader statin market but creates recurring demand.
Generic affordability
Low price supports continued use in primary care and endocrinology. Fenofibrate is substantially less expensive than PCSK9 antibodies and many newer lipid-lowering therapies. That cost advantage supports demand in markets with strict reimbursement controls.
Combination use with statins
Fenofibrate may be used alongside statins in selected patients with high triglycerides and low HDL cholesterol. The overall cardiovascular benefit of routine combination therapy is limited. In the ACCORD Lipid trial, fenofibrate added to simvastatin did not significantly reduce major cardiovascular events in the overall study population [2].
Diabetes and metabolic disease prevalence
Type 2 diabetes, obesity, metabolic syndrome, and chronic kidney disease are associated with abnormal triglyceride profiles. Growth in these conditions supports the underlying patient pool. The commercial impact is moderated by increasing use of statins and newer diabetes medicines that may improve lipid profiles indirectly.
Clinical guideline selectivity
Guidelines generally prioritize lifestyle intervention, statins, and prescription omega-3 therapy when clinically appropriate. Fenofibrate use is therefore concentrated in defined subgroups rather than broad preventive prescribing [3].
How does fenofibrate compare with competing lipid-lowering drugs?
| Drug class | Primary lipid effect | Typical market position | Commercial implication for fenofibrate |
|---|---|---|---|
| Statins | LDL cholesterol reduction | First-line therapy | Limits fenofibrate use in routine dyslipidemia |
| Fenofibrate | Triglyceride reduction, HDL increase | Severe triglycerides and mixed dyslipidemia | Retains low-cost niche |
| Icosapent ethyl | Triglyceride reduction and cardiovascular risk reduction in selected patients | Premium adjunct therapy | Competes for high-risk patients |
| Other prescription omega-3 products | Triglyceride reduction | Severe hypertriglyceridemia | Competes where triglyceride lowering is the priority |
| PCSK9 inhibitors | Large LDL reduction | High-risk or familial hypercholesterolemia | Limited direct overlap, but captures intensive lipid-management budgets |
| Bempedoic acid | LDL reduction | Statin-intolerant patients | Expands alternatives for LDL management |
| Ezetimibe | LDL reduction | Low-cost add-on therapy | Competes when LDL, rather than triglycerides, is the treatment target |
Fenofibrate is unlikely to displace statins or PCSK9 therapies. Its strongest commercial position is as a low-cost triglyceride-lowering option where LDL cholesterol is not the primary unresolved risk.
What patents protect fenofibrate products?
The core fenofibrate compound is an old small molecule, and its foundational patent protection has expired. The original commercial opportunity depended on formulation, dosage, bioavailability, and salt or ester technologies rather than ongoing compound exclusivity.
Historical formulation and product protection
| Product or technology | Protection type | Current commercial significance |
|---|---|---|
| Tricor | Formulation and bioavailability claims | Historical protection; generic competition established |
| Triglide | Formulation and particle-size technology | Historical protection; no meaningful compound exclusivity |
| Antara | Micronized or modified formulation | Historical product differentiation |
| Lipofen | Formulation and release characteristics | Historical protection |
| Trilipix | Fenofibric acid active moiety and formulation | Separate product lineage from standard fenofibrate |
Fenofibrate formulation patents historically addressed micronization, dissolution, particle size, food-effect reduction, and delivery of poorly water-soluble drug material. These patents delayed generic substitution for some products but did not create durable protection after the main patents expired.
When does fenofibrate lose exclusivity?
Fenofibrate has already lost primary market exclusivity in the United States and major international markets. The molecule is not protected by an active new chemical entity exclusivity period.
Relevant FDA milestones include:
- Original fenofibrate products were approved decades ago.
- Generic versions were approved through the abbreviated new drug application pathway.
- Multiple dosage forms and strengths are listed in FDA product and Orange Book records.
- Brand-specific formulation patents have expired or no longer prevent broad generic substitution.
Because fenofibrate is a generic small molecule, biosimilar risk does not apply. The relevant competitive threat is ANDA-based generic entry, formulation substitution, private-label supply, and price competition.
What is the Orange Book status of fenofibrate?
The FDA Orange Book lists approved prescription drug products, therapeutic equivalence information, and patent or exclusivity information where applicable [4]. Fenofibrate products are generally classified as mature generic products with multiple approved suppliers.
Commercial diligence should distinguish among:
- Fenofibrate tablets.
- Fenofibrate capsules.
- Micronized fenofibrate formulations.
- Fenofibric acid products.
- Immediate-release and modified-release products.
- Different strengths that may not have identical substitution patterns.
A generic supplier can have an approved product without achieving automatic substitution across every branded formulation. Therapeutic equivalence depends on the specific reference-listed drug, dosage form, strength, and FDA rating.
Are Paragraph IV challenges still relevant to fenofibrate?
Paragraph IV challenges were commercially important when branded fenofibrate formulations still had active Orange Book patents. The main litigation opportunity involved asserting that listed formulation patents were invalid, unenforceable, or not infringed.
For the current market, Paragraph IV risk is less important than:
- Approval of additional ANDAs.
- Competition among established generic suppliers.
- Active pharmaceutical ingredient sourcing.
- Manufacturing reliability.
- Wholesale contracting.
- State substitution rules.
- Product-specific therapeutic-equivalence ratings.
Any new litigation would likely involve a specific formulation, dosage strength, manufacturing process, or newly developed delivery system rather than the basic fenofibrate molecule.
What generic entry risks exist for fenofibrate manufacturers?
Generic entry risk is high because the active ingredient is mature and multiple suppliers can manufacture it. The main risks are commercial rather than patent-based.
Price erosion
Generic competition can reduce prices rapidly when several suppliers enter the same strength and dosage form. The largest price declines generally occur in products with:
- High prescription volume.
- Simple manufacturing requirements.
- Multiple API suppliers.
- Limited differentiation.
- Broad pharmacy substitution.
Customer concentration
Large wholesalers, pharmacy benefit managers, government programs, and hospital purchasing groups can pressure suppliers for lower prices. A manufacturer with a small portfolio may face significant revenue volatility if it loses one contract.
API and supply-chain risk
Fenofibrate is a synthetic small molecule, and manufacturing barriers are lower than those for complex biologics. Supply risk is more likely to arise from:
- API plant inspections.
- Quality-control findings.
- Single-site dependence.
- Solvent or raw-material disruptions.
- Capacity reallocation by contract manufacturers.
Dosage-form fragmentation
The market is divided across strengths and formulations. A manufacturer with only one capsule strength may not achieve meaningful scale. A broader portfolio can support pharmacy and wholesaler contracting but increases inventory and regulatory complexity.
What formulations are protected by fenofibrate patents?
Historical formulation protection focused on the drug's low aqueous solubility and variable absorption. Key technical approaches included:
- Micronized active pharmaceutical ingredient.
- Nanoparticle or reduced-particle-size material.
- Improved dissolution profiles.
- Reduced dependence on food for absorption.
- Modified-release delivery.
- Tablet and capsule compositions.
- Specific excipient combinations.
- Fenofibric acid formulations.
The most commercially important formulation claims have generally expired or been overtaken by approved generic products. A new entrant would need meaningful differentiation, such as improved adherence, lower dosing frequency, pediatric use, or a clinically validated combination product, to justify new patent expenditure.
What FDA regulatory issues affect fenofibrate sales?
Fenofibrate labeling contains important safety and use limitations. The FDA label identifies risks involving:
- Liver toxicity.
- Renal impairment.
- Gallbladder disease.
- Myopathy and rhabdomyolysis, particularly with statin coadministration.
- Serum creatinine changes.
- Drug interactions, including warfarin and certain statins [1].
Renal dosing is commercially relevant because the target population often includes older adults and patients with chronic kidney disease. Product positioning can be affected by differences in labeling, strength availability, and prescriber familiarity.
Fenofibrate does not have biosimilar competition. It also does not benefit from current biologic exclusivity mechanisms or orphan-drug exclusivity in its principal indications.
Which companies compete in the fenofibrate market?
The market includes branded originators, generic pharmaceutical companies, contract manufacturers, and regional suppliers. Major competitive categories include:
US generic manufacturers
Companies such as Teva, Amneal, Dr. Reddy's, Lupin, Torrent, and other approved ANDA holders have participated in the US generic lipid-lowering market. Supplier participation varies by dosage form and strength.
Branded and specialty suppliers
Historical brand owners include Abbott and AbbVie through the Tricor and related product franchises. Current commercial activity is more fragmented, with limited brand differentiation and generic substitution.
International manufacturers
European, Indian, Chinese, and regional pharmaceutical companies supply fenofibrate products under local brands and tender contracts. The competitive structure varies materially by country because many markets use hospital tenders or national reimbursement pricing.
How strong is the fenofibrate patent estate?
The fenofibrate patent estate is weak from an originator-exclusivity perspective and moderate only for narrowly defined formulation or process claims.
| Patent estate dimension | Assessment |
|---|---|
| Core compound patent | Expired |
| New chemical entity exclusivity | Expired |
| Basic oral dosage forms | Broad generic competition |
| Historical micronization claims | Largely expired or commercially overcome |
| Specific formulation claims | Potentially relevant only to defined products |
| Manufacturing-process claims | Limited blocking value unless difficult to design around |
| Method-of-use claims | Limited value because treatment indications are established |
| Biosimilar barrier | Not applicable |
| Generic substitution risk | High |
| Sustainable pricing power | Low |
A company seeking to enter the market should focus on manufacturing cost, reliable supply, a complete strength portfolio, and regulatory execution rather than relying on broad patent protection.
What is the revenue exposure for fenofibrate manufacturers?
Fenofibrate is most valuable to manufacturers with an established generic platform. As a standalone product, it is unlikely to support premium pricing. Revenue quality depends on volume, supply reliability, and portfolio placement.
Revenue scenarios for a generic supplier
| Supplier position | Annual net sales potential | Commercial profile |
|---|---|---|
| Small regional supplier | $1 million to $10 million | Limited strengths or local distribution |
| Established multi-country generic supplier | $10 million to $50 million | Several strengths and stable contracts |
| Large portfolio supplier | $50 million to $150 million | Broad geographic coverage and channel access |
| Branded differentiated product | Variable, generally declining | Requires formulation, adherence, or combination value |
These ranges are indicative product-level scenarios, not audited company forecasts. The most attractive opportunity is usually portfolio aggregation, where fenofibrate supports a broader cardiovascular or diabetes franchise.
What generic launch scenarios are likely?
Base-case scenario
Generic suppliers maintain current availability, prices decline gradually, and prescription volume remains stable. US sales fall about 2% to 4% annually. Global sales decline more slowly because emerging-market volume partly offsets developed-market price erosion.
Downside scenario
Several additional suppliers enter, a major payer changes its preferred generic supplier, or an established manufacturer resumes full capacity. US prices fall sharply, with molecule sales declining 6% to 9% annually.
Upside scenario
Demand increases in severe hypertriglyceridemia, emerging markets expand access, or a differentiated formulation secures reimbursement. Global revenue is broadly stable, but a conventional generic product still has limited pricing power.
What licensing deals affect fenofibrate?
Fenofibrate has had historical commercial licensing, co-promotion, and distribution arrangements around products such as Tricor and related formulations. The principal licensing value was tied to branded formulation rights, regulatory approvals, and geographic commercialization.
The current generic market is more likely to use:
- Contract manufacturing agreements.
- API supply agreements.
- Distribution partnerships.
- Private-label arrangements.
- Authorized-generic supply contracts.
- Regional marketing rights.
New licensing value would be strongest for a combination product, modified-release formulation, or product with evidence supporting a defined high-risk population. A license covering conventional immediate-release fenofibrate would have limited negotiating power because multiple generic alternatives are available.
What litigation and settlement issues affect fenofibrate?
The historical litigation pattern involved originator patents covering branded formulations and generic companies seeking earlier market entry through Paragraph IV certifications. Those disputes were commercially important before the market became broadly generic.
The current litigation risk is lower at the molecule level. Potential disputes could still involve:
- Formulation patents.
- Patent listing disputes.
- ANDA infringement allegations.
- Manufacturing-process claims.
- Trade dress and trademark issues.
- Product liability and labeling claims.
- Antitrust allegations related to generic contracting.
Settlement agreements would have limited present market impact unless they concern a newly patented formulation with meaningful clinical or commercial differentiation.
How does fenofibrate compare with fenofibric acid products?
Fenofibric acid products were developed partly to offer a different active moiety and formulation strategy. Trilipix was positioned for use alone or with statins in mixed dyslipidemia.
Fenofibric acid may have formulation and dosing distinctions, but the products compete for a similar clinical population. The commercial advantage is limited when payers and prescribers can substitute lower-cost fenofibrate products. The key diligence question is whether a specific product has automatic substitution, preferred formulary status, or a clinically meaningful dosing advantage.
Key Takeaways
- Fenofibrate is a mature generic small molecule with expired core compound protection.
- Generic competition is the dominant commercial force.
- The base-case global market is modeled at approximately $1.10 billion in 2024, declining to about $930 million by 2029.
- The US market is modeled at approximately $300 million in 2024, declining to about $259 million by 2029.
- Severe hypertriglyceridemia remains the most durable demand segment.
- Routine cardiovascular prevention is a weak growth driver because clinical-outcomes evidence for broad statin combination use is limited.
- Biosimilar risk does not apply.
- Paragraph IV risk is historically important but currently secondary to generic price and supply competition.
- Formulation patents created the main historical barrier, but broad formulation protection has largely expired or been commercially overcome.
- The best commercial strategy is portfolio-based generic supply, not premium pricing for conventional fenofibrate.
- New product value would require differentiated delivery, combination therapy, or a defined clinical benefit.
FAQs About Fenofibrate Market Size and Commercial Outlook
Is fenofibrate still a profitable generic drug?
Yes, but profitability depends on manufacturing scale, contract access, and supply reliability. Conventional fenofibrate generally has low unit margins and limited pricing power.
Does fenofibrate have patent protection in the United States?
The original compound patent and primary exclusivity periods have expired. Narrow formulation or process patents may exist for specific products, but they do not create broad protection for conventional fenofibrate.
Is fenofibrate subject to biosimilar competition?
No. Fenofibrate is a small-molecule drug regulated through the generic ANDA pathway, not the biosimilar pathway.
What drug most directly competes with fenofibrate?
Prescription omega-3 products and other triglyceride-lowering therapies are the closest pharmacologic competitors. Statins are the primary broader lipid-management competitor but mainly target LDL cholesterol.
Will fenofibrate sales increase through 2030?
A sustained global increase is unlikely in the base case. Volume may remain stable or rise in emerging markets, but generic price erosion in the United States and Europe is expected to produce flat-to-declining total revenue.
References
-
U.S. Food and Drug Administration. (2023). Fenofibrate tablets prescribing information. FDA-approved labeling.
-
ACCORD Study Group. (2010). Effects of combination lipid therapy in type 2 diabetes mellitus. New England Journal of Medicine, 362(17), 1563-1574.
-
Grundy, S. M., Stone, N. J., Bailey, A. L., et al. (2019). 2018 AHA/ACC/AACVPR/AAPA/ABC/ACPM/ADA/AGS/APhA/ASPC/NLA/PCNA guideline on the management of blood cholesterol. Circulation, 139(25), e1082-e1143.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
American College of Cardiology. (2021). Expert consensus decision pathway on the management of persistent hypertriglyceridemia. Journal of the American College of Cardiology, 78(9), 960-993.
More… ↓
