Share This Page
Drug Sales Trends for ZYLOPRIM
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ZYLOPRIM (2007)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
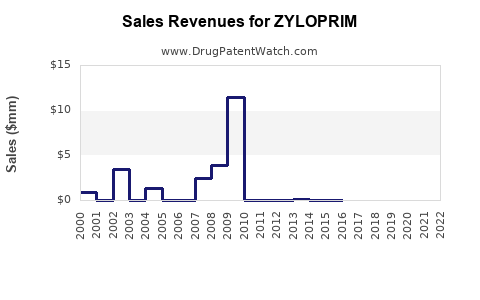
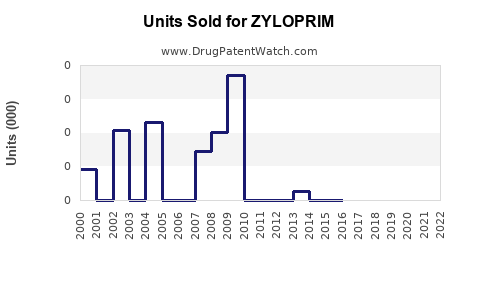
Annual Sales Revenues and Units Sold for ZYLOPRIM
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ZYLOPRIM | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ZYLOPRIM | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ZYLOPRIM | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ZYLOPRIM | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ZYLOPRIM | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ZYLOPRIM | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| ZYLOPRIM | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Zyloprim Market Analysis and Sales Projections: Allopurinol Revenue, Competition, Patents, and Generic Risk
Zyloprim is the branded formulation of allopurinol, a low-cost oral xanthine oxidase inhibitor used primarily for chronic gout, hyperuricemia associated with cancer treatment, and selected uric-acid kidney stone conditions. Its commercial market is mature and dominated by generic allopurinol. The brand has limited pricing power, no meaningful regulatory exclusivity, and low public revenue visibility.
The base-case outlook is for stable or modestly growing allopurinol demand, driven by rising gout prevalence and broader urate-lowering treatment. Zyloprim brand sales are likely to decline gradually or remain commercially marginal as generic substitution persists. A reasonable modeled range for U.S. Zyloprim net sales is approximately $2 million to $10 million annually, with a base case of $4 million to $6 million. These are analytical estimates, not company-reported sales.
What is Zyloprim and what is it used for?
Zyloprim contains allopurinol, a purine analog that inhibits xanthine oxidase and reduces the production of uric acid. The U.S. product is an oral tablet approved for chronic urate-lowering treatment rather than acute relief of a gout attack.
| Attribute | Zyloprim |
|---|---|
| Active ingredient | Allopurinol |
| Drug class | Xanthine oxidase inhibitor |
| Dosage form | Oral tablets |
| Common strengths | 100 mg and 300 mg |
| Main indications | Gout, hyperuricemia, tumor-lysis-related uric acid elevation, selected calcium oxalate stone disease |
| U.S. regulatory status | Approved prescription drug |
| Therapeutic category | Rheumatology, nephrology, oncology supportive care |
| Primary competitors | Generic allopurinol, febuxostat, pegloticase, rasburicase |
| Commercial position | Legacy branded product in a genericized market |
The product is primarily used for long-term prevention. Its value proposition is clinical familiarity, low acquisition cost relative to newer agents, and extensive physician experience.
How large is the allopurinol and Zyloprim market?
The allopurinol market is substantially larger than the Zyloprim brand market. U.S. allopurinol prescriptions are measured in the tens of millions annually, while branded Zyloprim represents a small fraction of dispensed treatment because multiple generic manufacturers supply the same active ingredient.
The principal demand drivers are:
- Increasing prevalence of gout and hyperuricemia.
- Longer treatment duration among diagnosed gout patients.
- Greater use of treat-to-target urate management.
- Growth in obesity, chronic kidney disease, hypertension, and metabolic disease.
- Increased oncology use of urate-lowering prophylaxis, although rasburicase is preferred in high-risk tumor lysis syndrome.
- Greater diagnosis and treatment of recurrent gout in older adults.
The principal market constraints are generic price compression, treatment discontinuation, dose-titration challenges, renal impairment concerns, and the availability of febuxostat for patients who cannot tolerate allopurinol.
Modeled U.S. market size
Public sources do not separately disclose audited Zyloprim sales. The following market model uses prescription volume, generic pricing, and brand-share assumptions.
| Metric | Low case | Base case | High case |
|---|---|---|---|
| Annual U.S. allopurinol prescriptions | 20 million | 27 million | 35 million |
| Average net value per prescription | $5 | $10 | $18 |
| Estimated U.S. allopurinol market value | $100 million | $270 million | $630 million |
| Estimated Zyloprim brand share | 0.5% | 1.5% | 3.0% |
| Implied Zyloprim U.S. net sales | $0.5 million | $4.1 million | $18.9 million |
The base case places Zyloprim in the low-single-digit-million-dollar range in U.S. annual net sales. A higher figure is possible if the brand retains institutional, specialty-pharmacy, or patient-specific demand, but the competitive economics do not support a large branded franchise.
What are the Zyloprim sales projections for 2025 through 2029?
The base case assumes stable prescription volume growth of 1% to 3% annually for allopurinol, continued generic price erosion of 1% to 3%, and gradual brand-share loss. Under those assumptions, total market value grows slowly while Zyloprim revenue declines.
| Year | Low-case Zyloprim sales | Base-case Zyloprim sales | High-case Zyloprim sales |
|---|---|---|---|
| 2025 | $2.0 million | $5.0 million | $12.0 million |
| 2026 | $1.8 million | $4.7 million | $11.8 million |
| 2027 | $1.6 million | $4.4 million | $11.6 million |
| 2028 | $1.4 million | $4.1 million | $11.4 million |
| 2029 | $1.2 million | $3.8 million | $11.2 million |
| 2025-2029 CAGR | -11.9% | -6.6% | -1.7% |
What could change the forecast?
Upside would require a specific commercial strategy, such as a price-insensitive institutional customer base, supply disruptions affecting generic competitors, or a branded adherence program. A material increase in Zyloprim revenue from underlying disease growth alone is unlikely.
Downside risks include:
- New generic suppliers entering or expanding production.
- Pharmacy benefit managers imposing mandatory generic substitution.
- Lower wholesale acquisition prices for generic allopurinol.
- Manufacturer discontinuation or supply rationalization.
- Increased use of febuxostat in selected allopurinol-intolerant patients.
- Greater use of combination products or alternative urate-lowering strategies.
What is the competitive landscape for Zyloprim?
Generic allopurinol is the dominant competitive product. The drug is manufactured by multiple suppliers in 100 mg and 300 mg tablets, creating a highly fragmented and price-sensitive market.
| Competitor | Ingredient or modality | Position against Zyloprim |
|---|---|---|
| Generic allopurinol | Allopurinol | Primary substitute; lowest-cost option |
| Uloric and generic febuxostat | Febuxostat | Alternative xanthine oxidase inhibitor |
| Krystexxa | Pegloticase | Intravenous option for uncontrolled or refractory chronic gout |
| Elitek | Rasburicase | Acute oncology use; not a routine chronic gout substitute |
| Colchicine | Anti-inflammatory | Treats flares; does not replace chronic urate lowering |
| Probenecid | Uricosuric | Alternative in selected patients with adequate renal function |
Febuxostat competes on pharmacology and use in some patients with renal impairment or allopurinol intolerance. Its historical cardiovascular safety concerns and branded-to-generic transition have limited its ability to displace allopurinol broadly. Pegloticase is clinically differentiated but is reserved for severe refractory disease because of administration burden and cost.
What patents protect Zyloprim?
Zyloprim has no commercially important remaining composition-of-matter exclusivity. Allopurinol was discovered and commercialized decades ago, and the relevant patent term has expired.
The practical intellectual-property position is:
| IP category | Current commercial relevance |
|---|---|
| Allopurinol composition patent | Expired |
| Original Zyloprim product protection | Expired |
| Tablet formulation patents | No known commercially decisive active protection |
| Method-of-use patents | No meaningful barrier to routine generic substitution |
| Manufacturing patents | Potentially relevant to individual suppliers, but not a barrier to generic tablets |
| Orange Book patent exclusivity | No material protection expected for routine Zyloprim tablets |
The U.S. product is associated with an established FDA new drug application, but the product’s age means generic applicants have long been able to rely on abbreviated new drug application pathways. The absence of an active patent barrier materially reduces Zyloprim’s strategic value as a protected asset.
How strong is the Zyloprim patent estate?
The patent estate is weak from a lifecycle-management perspective. There is no apparent active patent position capable of delaying generic competition or supporting a Paragraph IV litigation strategy for the core 100 mg and 300 mg tablets.
Potentially protectable areas, such as excipient selection, tablet processing, packaging, or manufacturing controls, would have limited commercial impact unless they produced a clinically meaningful or regulatory differentiation. Those features would not normally prevent approval of a therapeutically equivalent generic tablet.
What is the Orange Book status of Zyloprim?
Zyloprim is an approved small-molecule prescription product, but its commercial protection does not depend on current regulatory exclusivity. Any original new chemical entity exclusivity and historical patent protection expired long ago.
Generic allopurinol products are approved through the FDA ANDA pathway. The presence of multiple approved generic products means the core product is exposed to automatic substitution under state pharmacy laws and payer formularies, subject to local requirements.
There is no biosimilar pathway for Zyloprim because allopurinol is a synthetic small molecule rather than a biologic. Biosimilar risk is therefore not applicable. The relevant competitive risk is generic substitution.
When did Zyloprim lose exclusivity?
Zyloprim lost practical exclusivity many years ago. Allopurinol’s original patent and regulatory protection expired before the modern generic market became the principal supply channel. Generic manufacturers have supplied allopurinol tablets for decades.
The commercial consequence is more important than the historical expiration date: Zyloprim cannot rely on exclusivity to sustain premium pricing, prevent generic entry, or control distribution.
Which companies are challenging Zyloprim?
The relevant challengers are generic manufacturers rather than named Paragraph IV litigants. Multiple companies have historically marketed allopurinol tablets through ANDAs, including large and specialty generic suppliers. Competition is based primarily on manufacturing cost, supply reliability, wholesaler access, and formulary contracting.
A current Paragraph IV challenge is unlikely to be commercially material because there is no meaningful remaining patent barrier around the core product. Any litigation involving an individual generic formulation or manufacturing process would have limited effect on the broader allopurinol market.
What FDA regulatory factors affect Zyloprim sales?
Zyloprim’s FDA-approved labeling supports treatment of chronic gout and other hyperuricemia-related conditions. The most important regulatory and clinical issues are safety management and appropriate patient selection.
Key labeling considerations include:
- Hypersensitivity reactions, including severe cutaneous adverse reactions.
- Dose adjustment in renal impairment.
- The HLA-B*58:01 genetic risk marker in certain higher-risk populations.
- Interaction with azathioprine and mercaptopurine.
- The need to initiate treatment at low doses and titrate.
- The distinction between chronic urate lowering and acute flare treatment.
These factors can increase physician preference for established labeling and known clinical experience, but they do not create meaningful market exclusivity.
What generic entry risks exist for Zyloprim?
Generic entry is already complete. The principal risk is not initial launch but continued erosion of branded share and pricing.
| Risk | Probability | Commercial effect |
|---|---|---|
| Further generic price compression | High | Reduces total market value |
| Mandatory generic substitution | High | Reduces Zyloprim volume |
| Generic supply disruption | Low to medium | Temporary brand opportunity |
| New formulation patent | Low | Limited unless clinically differentiated |
| Increased febuxostat use | Medium | Selective erosion in allopurinol-intolerant patients |
| Clinical safety-driven restriction | Low to medium | Could reduce use in selected populations |
| Rising gout prevalence | High | Supports total prescription volume |
Brand retention is most plausible where physicians or patients prioritize a specific manufacturer, where supply continuity matters, or where institutional contracts preserve branded dispensing. Those channels are unlikely to produce sustained high growth.
How does Zyloprim compare with febuxostat?
Zyloprim has the cost advantage and the largest installed base. Febuxostat has a more targeted role in patients who cannot use allopurinol or who do not achieve adequate urate control.
| Factor | Zyloprim | Febuxostat |
|---|---|---|
| Drug class | Xanthine oxidase inhibitor | Xanthine oxidase inhibitor |
| Market maturity | Very mature | Mature, but less entrenched |
| Generic availability | Extensive | Increasing |
| Cost | Very low | Generally higher |
| Primary commercial advantage | Price and familiarity | Alternative mechanism and dosing profile |
| Main limitation | Hypersensitivity and titration concerns | Cardiovascular safety considerations and cost |
| Patent strength | Expired | Largely eroded for standard products |
Zyloprim is likely to retain the majority of routine first-line urate-lowering use because treatment guidelines and payer economics favor allopurinol in many patients.
What licensing deals affect Zyloprim?
No major recent licensing transaction is central to the Zyloprim market thesis. The product is a legacy small-molecule brand rather than a high-growth platform asset. Commercial value is more likely to arise from a product acquisition, authorized-generic arrangement, or portfolio transaction than from a technology license.
A buyer would evaluate:
- Net sales by channel.
- Manufacturer and wholesaler contracts.
- Supply continuity.
- Product liability exposure.
- FDA manufacturing history.
- Brand-to-generic substitution rates.
- Working-capital requirements.
- Any remaining distribution rights.
Without a protected indication or differentiated dosage form, an acquisition would likely be valued on cash flow, supply reliability, and portfolio fit rather than patent life.
What patent litigation affects Zyloprim?
No material active patent litigation is expected to affect standard Zyloprim tablets. Any dispute involving allopurinol would more likely concern manufacturing, product quality, labeling, antitrust, or commercial contracting than exclusivity over the active ingredient.
The litigation risk profile is therefore low for patent infringement but not zero for product liability or regulatory compliance. Severe hypersensitivity warnings and renal dosing issues create greater operational exposure than patent enforcement.
What are the key commercial risks and opportunities?
Commercial risks
The main risks are generic substitution, low unit pricing, limited brand differentiation, and the absence of exclusivity. Even if the treated patient population expands, the benefit will accrue primarily to generic manufacturers and pharmacies rather than the Zyloprim brand.
Commercial opportunities
Potential opportunities include:
- Maintaining a reliable supply during generic shortages.
- Targeting specialist prescribers who prefer the branded product.
- Developing patient-support tools around titration and adherence.
- Securing institutional contracts where supply continuity has value.
- Exploring authorized-generic economics.
- Using the product as part of a broader rheumatology or nephrology portfolio.
These strategies could stabilize revenue but are unlikely to create a high-growth branded franchise without a differentiated formulation or delivery system.
Key Takeaways
- Zyloprim is the legacy brand of allopurinol, a widely used oral xanthine oxidase inhibitor.
- The active ingredient, core product protection, and practical exclusivity have expired.
- Generic allopurinol dominates the U.S. market and determines pricing.
- Estimated U.S. Zyloprim net sales are likely in the low-single-digit millions annually, with a modeled 2025 base case of about $5 million.
- Base-case brand sales decline approximately 6% to 7% annually through 2029.
- Total allopurinol demand should remain stable or grow modestly because gout prevalence and long-term treatment are increasing.
- Paragraph IV, biosimilar, and active Orange Book patent risks are not central to the product.
- The principal risks are generic substitution, price compression, supply rationalization, and limited brand differentiation.
- Commercial value depends on distribution, supply reliability, and portfolio strategy rather than patent life.
FAQs About Zyloprim Market Size and Sales
Is Zyloprim still sold in the United States?
Yes. Zyloprim remains an approved branded allopurinol product, although generic allopurinol is the dominant supply channel.
Is Zyloprim more effective than generic allopurinol?
No clinically meaningful therapeutic superiority has been established for the branded product when the generic contains equivalent allopurinol and meets FDA requirements for therapeutic equivalence.
Does Zyloprim have patent protection in 2025?
The original product and active-ingredient protections have expired. No meaningful patent barrier is expected to protect routine Zyloprim tablets from generic competition.
What is the expected global growth rate for allopurinol?
A reasonable planning assumption is low-single-digit annual prescription growth, offset partly by generic price erosion. Revenue growth is therefore likely to be lower than volume growth.
Could Zyloprim sales increase if gout prevalence rises?
Higher gout prevalence would increase the underlying treatment pool, but most incremental revenue would likely flow to generic allopurinol. Zyloprim would need stronger brand retention, supply differentiation, or commercial contracting to capture that growth.
References
-
U.S. Food and Drug Administration. (n.d.). Zyloprim (allopurinol) tablets prescribing information. FDA.
-
U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (n.d.). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
FitzGerald, J. D., Dalbeth, N., Mikuls, T., Brignardello-Petersen, R., Guyatt, G., Abeles, A. M., Andrade, Q., et al. (2020). 2020 American College of Rheumatology guideline for the management of gout. Arthritis Care & Research, 72(6), 744-760.
-
U.S. Food and Drug Administration. (2018). FDA recommends screening for HLA-B58:01 before starting allopurinol in selected patients*. FDA.
-
National Institute of Diabetes and Digestive and Kidney Diseases. (n.d.). Gout and hyperuricemia. National Institutes of Health.
More… ↓
