Share This Page
Drug Sales Trends for LAMISIL
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for LAMISIL (2007)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
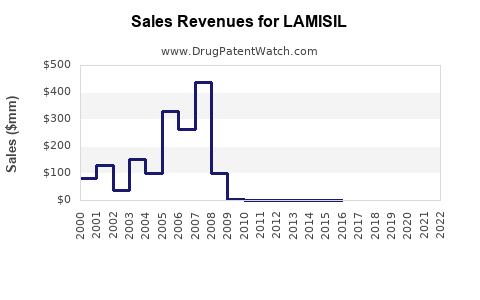
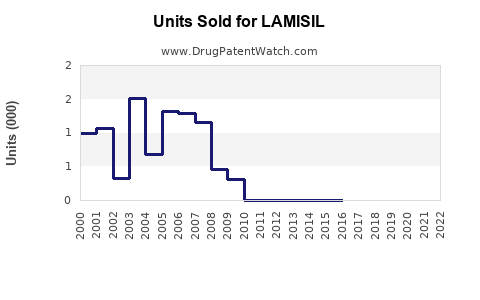
Annual Sales Revenues and Units Sold for LAMISIL
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| LAMISIL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| LAMISIL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| LAMISIL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| LAMISIL | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| LAMISIL | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Lamisil Market Analysis, Sales Projections, Patent Expiration, and Generic Risk
Lamisil is the brand name for terbinafine, an allylamine antifungal sold in oral tablets, topical creams, gels, sprays, and solutions. The brand generated peak annual sales of roughly $1 billion for Novartis before generic terbinafine and OTC competition eroded revenue. Current commercial value is concentrated in generic oral terbinafine and OTC topical products rather than the original prescription brand.
The Lamisil market is mature, price-sensitive, and largely exposed to generic substitution. A reasonable base-case estimate places global terbinafine product sales across branded, generic, and OTC channels at approximately $450 million to $650 million annually, with low single-digit growth through 2028. The branded Lamisil share is likely below 20% of global terbinafine value.
What is Lamisil and how does it make money?
Lamisil contains terbinafine hydrochloride. Oral terbinafine is used primarily for onychomycosis, while topical products treat tinea pedis, tinea corporis, and tinea cruris. The oral product is prescription-only in the United States. Several topical forms are sold over the counter in the U.S. and other major markets.
| Product | Active ingredient | Main indication | Channel | Commercial position |
|---|---|---|---|---|
| Lamisil tablets | Terbinafine hydrochloride | Toenail and fingernail fungal infections | Prescription | Generic-dominated |
| Lamisil AT cream | Terbinafine hydrochloride | Athlete's foot and ringworm | OTC | Branded and private-label competition |
| Lamisil AT spray | Terbinafine hydrochloride | Athlete's foot | OTC | Convenience-led OTC segment |
| Lamisil topical solution or gel | Terbinafine hydrochloride | Superficial dermatophyte infections | OTC or prescription, depending on country | Fragmented |
| Generic terbinafine tablets | Terbinafine hydrochloride | Onychomycosis | Prescription | Primary volume product |
| Generic terbinafine topical products | Terbinafine hydrochloride | Superficial fungal infections | OTC or prescription | Low-cost competition |
The oral tablet has a higher average treatment value than topical products because therapy may last 6 weeks for fingernail infections and 12 weeks or longer for toenail infections. Topical products have broader consumer reach but lower revenue per treatment course.
How large is the Lamisil and terbinafine market?
Public company filings no longer report Lamisil as a standalone material brand. Novartis reported Lamisil sales of approximately $1 billion during the brand's peak period, before loss of exclusivity and generic entry reduced the product's contribution.[1]
Current market value is best analyzed by product segment:
| Segment | Estimated global annual value | 2024-2028 outlook | Main growth driver |
|---|---|---|---|
| Generic oral terbinafine | $180 million-$280 million | 1%-3% annual growth | Aging population and diagnosis of onychomycosis |
| Branded and generic topical terbinafine | $180 million-$270 million | 2%-4% annual growth | OTC self-care and emerging-market access |
| Original Lamisil brand | $60 million-$120 million | Flat to declining | Brand recognition and pharmacy presence |
| Combination and private-label products | $30 million-$60 million | 2%-5% annual growth | Retail and distributor expansion |
| Total terbinafine market | $450 million-$650 million | 1%-4% annual growth | Volume growth offset by price erosion |
These figures represent an analytical market model rather than reported consolidated sales. The market is highly fragmented, and many manufacturers report terbinafine revenue within broader dermatology or consumer-health categories.
What are the Lamisil sales projections through 2028?
The original Lamisil brand should remain a small but recognizable portion of the market. Generic substitution limits pricing power in oral terbinafine, while OTC shelf space and advertising support determine the performance of topical Lamisil.
Base-case projection
| Year | Global terbinafine market | Original Lamisil brand | Generic and private-label share |
|---|---|---|---|
| 2024 | $450 million-$650 million | $60 million-$120 million | $390 million-$530 million |
| 2025 | $465 million-$670 million | $58 million-$115 million | $407 million-$555 million |
| 2026 | $480 million-$690 million | $56 million-$112 million | $424 million-$578 million |
| 2027 | $495 million-$715 million | $54 million-$109 million | $441 million-$606 million |
| 2028 | $510 million-$740 million | $52 million-$106 million | $458 million-$634 million |
The model assumes:
- Oral generic volume grows by approximately 2% annually.
- Oral average selling prices decline by 2%-4% annually.
- OTC topical volume grows by 2%-4% annually.
- Branded Lamisil revenue declines by approximately 2%-5% annually.
- Emerging-market volume growth partly offsets mature-market price erosion.
- No major new terbinafine indication materially expands the market.
Bull case
A bull case would produce a 4%-6% annual market growth rate through 2028. The main drivers would be higher diagnosis rates for onychomycosis, increased use of oral therapy, stronger pharmacy distribution in Asia-Pacific and Latin America, and stable OTC pricing for branded spray and cream formats.
Bear case
A bear case would result in a market decline of 1%-3% annually. The principal risks are continued generic price compression, substitution by newer topical agents, limited physician use of oral therapy because of liver-safety monitoring, and weak consumer spending in OTC categories.
Which companies compete with Lamisil?
The competitive landscape differs sharply between oral and topical products.
Oral terbinafine competitors
Generic manufacturers compete primarily on price, supply reliability, regulatory compliance, and wholesaler access. The market includes regional generic companies and large multinational suppliers. Brand competition from itraconazole is clinically relevant, although itraconazole is not a direct formulation substitute in every case.
| Competitor | Product | Competitive effect |
|---|---|---|
| Generic terbinafine manufacturers | Oral tablets | Direct substitution and price erosion |
| Itraconazole manufacturers | Oral capsules and solutions | Alternative systemic treatment |
| Fluconazole manufacturers | Oral products | Off-label or alternative antifungal use in some markets |
| Dermatology-focused companies | Newer topical agents | Compete for superficial and nail infections |
Topical competitors
OTC topical competition includes clotrimazole, miconazole, butenafine, tolnaftate, and undecylenic acid products. Lamisil benefits from strong consumer recognition and a shorter advertised treatment course in some superficial fungal infections.
The main retail competitors are not limited to branded pharmaceutical companies. Retailer private labels, pharmacy generics, and e-commerce sellers can sell comparable terbinafine products at significant discounts.
When did Lamisil lose market exclusivity?
Lamisil's core oral and topical exclusivity expired years ago. FDA-approved generic terbinafine tablets are widely available, and topical terbinafine products are also sold by multiple manufacturers. The original product no longer has a meaningful composition-of-matter exclusivity barrier in the United States.
The key commercial events were:
| Event | Approximate timing | Commercial effect |
|---|---|---|
| U.S. approval of oral Lamisil tablets | 1996 | Launch of prescription terbinafine for onychomycosis |
| Expansion of topical Lamisil products | 1990s | Development of OTC and prescription dermatology franchise |
| Core patent expiry and generic entry | Mid-to-late 2000s | Rapid erosion of oral brand value |
| Broad generic availability | 2010s | Oral terbinafine became a commodity product |
| Mature OTC competition | 2010s-present | Brand value concentrated in consumer recognition and distribution |
FDA labeling identifies oral Lamisil as terbinafine hydrochloride tablets for treatment of onychomycosis and includes liver-related warnings and monitoring information.[2]
What patents protect Lamisil?
The original Lamisil patent estate covered terbinafine and related pharmaceutical compositions, formulations, and uses. Those foundational rights have expired in the United States and other major markets.
Composition-of-matter patents
The composition patents covering terbinafine were the most commercially important rights. Their expiry enabled generic oral tablets and materially reduced the value of the prescription brand. No active U.S. composition patent should be expected to block ordinary generic terbinafine tablets.
Formulation patents
Formulation rights historically covered tablets, creams, gels, sprays, solutions, and delivery vehicles. These patents may have supported particular branded products, but they do not generally prevent competitors from selling terbinafine in a different formulation or under an approved generic pathway.
Method-of-use patents
Use claims have covered treatment of dermatophyte infections, including nail infections and superficial skin infections. These claims are old relative to current market entry and are unlikely to create a significant blocking position for standard terbinafine products.
Manufacturing and process rights
Manufacturing patents and proprietary process know-how may still affect cost, impurity control, and supply reliability. They do not create a broad market barrier because multiple manufacturers have established terbinafine production capabilities.
What is the Orange Book status of Lamisil?
Lamisil tablets were approved under FDA New Drug Application 020539. The FDA Orange Book historically listed patent and exclusivity information associated with the approved product. The practical market outcome is clear: generic terbinafine tablets are approved and commercially available, so the original Lamisil listing does not provide current product-level exclusivity against routine generic substitution.[3]
Orange Book considerations remain relevant for:
- Whether a particular generic can be substituted at the pharmacy.
- Patent certifications made by an abbreviated new drug application applicant.
- Any later-listed patents covering a specific formulation or use.
- Product-specific labeling differences.
- State-level substitution rules.
For ordinary terbinafine hydrochloride tablets, the principal commercial issue is price and distribution rather than Orange Book patent blocking.
Have companies challenged Lamisil through Paragraph IV filings?
Paragraph IV challenges were relevant during the original generic-entry period. A generic applicant could certify that a listed Lamisil patent was invalid, unenforceable, or would not be infringed. Those disputes helped determine the timing of generic entry in the mid-to-late 2000s.
Paragraph IV litigation is no longer the principal risk to the original brand because:
- Core Lamisil patents have expired.
- Generic terbinafine has broad market access.
- Current competition is based on price, supply, and channel execution.
- Any later patent would need to cover a commercially meaningful formulation or use rather than standard terbinafine itself.
Publicly material current Paragraph IV activity is not a central feature of the Lamisil market.
What patent litigation affects Lamisil?
Historical litigation centered on generic entry and the validity or scope of patents covering terbinafine products. The litigation risk today is limited relative to products with active composition patents or complex delivery systems.
Potential disputes could still arise over:
- A novel terbinafine formulation.
- A combination antifungal product.
- A narrow treatment method.
- Trade dress or trademark use involving the Lamisil name.
- Manufacturing processes or supply agreements.
These issues are unlikely to restore the original Lamisil brand's lost exclusivity.
What regulatory risks affect Lamisil sales?
The most important regulatory issue for oral terbinafine is hepatotoxicity. FDA labeling warns about liver failure, contraindications in chronic or active liver disease, and the need to evaluate patients before treatment.[2] These warnings can limit prescribing relative to topical products.
Key regulatory factors include:
| Factor | Effect on market |
|---|---|
| Liver-safety labeling | Limits use in some patients |
| Prescription status of oral tablets | Restricts direct-to-consumer access |
| OTC status of many topical products | Supports self-treatment and retail volume |
| Generic ANDA pathway | Increases competition |
| Product quality and supply compliance | Determines generic availability |
| Country-specific switching rules | Affects brand retention |
Biosimilar risk is not relevant. Terbinafine is a small-molecule chemical drug, not a biologic. Competition occurs through generic drug applications, OTC registrations, and national regulatory pathways rather than biosimilar approval.
How strong is the Lamisil patent estate?
The historical patent estate was commercially strong during the protected period because it covered a differentiated oral antifungal with high treatment value. Its current strength is weak as an exclusivity asset.
| Patent category | Historical strength | Current strength |
|---|---|---|
| Terbinafine composition | High | Expired |
| Oral tablet formulation | Moderate to high | Largely expired or nonblocking |
| Topical formulation | Moderate | Limited, product-specific |
| Treatment methods | Moderate | Limited practical blocking value |
| Manufacturing process | Moderate | Supplier-level advantage only |
| Trademark and brand | High for recognition | Useful commercially, not a generic barrier |
Lamisil's remaining defensibility is primarily commercial. Brand awareness, retail placement, formulation convenience, and physician familiarity matter more than patent protection.
What are the main generic launch scenarios?
Generic launch has already occurred in the core oral market. Future launches would mainly involve additional suppliers, dosage forms, OTC private labels, or emerging-market registrations.
| Scenario | Probability | Market effect |
|---|---|---|
| Additional low-cost oral generic suppliers | High | More price erosion |
| Retail private-label topical terbinafine | High | Lower branded OTC share |
| Premium branded spray or gel formats | Moderate | Protects selected OTC revenue |
| New terbinafine combination product | Low to moderate | Creates niche growth |
| Reversal of generic substitution | Very low | No material effect expected |
Generic competition will continue to pressure revenue per prescription. The main exception is a differentiated OTC format that improves convenience, adherence, or consumer recognition.
How does Lamisil compare with competing antifungals?
| Attribute | Lamisil/terbinafine | Itraconazole | Clotrimazole | Newer topical agents |
|---|---|---|---|---|
| Main use | Nail and skin fungal infections | Systemic and nail infections | Skin and mucosal infections | Mainly nail infections |
| Oral form | Widely generic | Generic | Limited oral role | Usually topical |
| OTC presence | Strong topical presence | Limited | Strong | Limited |
| Generic pressure | Very high | High | Very high | Lower for patented products |
| Safety concern | Liver toxicity for oral use | Drug interactions and liver risk | Generally local tolerability | Product-specific |
| Pricing power | Low for oral; moderate for brand OTC | Low to moderate | Low | Higher where patented |
Terbinafine retains a strong clinical and commercial position in dermatophyte infections, especially when physicians choose oral treatment for onychomycosis. Its economic position is weaker because the active ingredient is mature and widely available.
What is the revenue exposure for manufacturers?
Revenue exposure varies by company type:
- Original brand owner: low growth, declining or stable revenue.
- Generic manufacturer: volume opportunity with limited margins.
- OTC brand marketer: moderate opportunity tied to advertising and retail execution.
- API manufacturer: stable but price-sensitive demand.
- Specialty dermatology company: potential upside from differentiated nail-delivery technologies.
For a company dependent on Lamisil-branded sales, the key risk is continued substitution by generic and private-label products. For a generic manufacturer, the opportunity is reliable demand but limited pricing power. For an OTC operator, the strongest assets are brand recognition, retail distribution, and high-convenience formats.
Key Takeaways
- Lamisil is terbinafine, a mature small-molecule antifungal.
- Peak brand sales approached $1 billion before generic erosion.
- Current global terbinafine product value is estimated at $450 million-$650 million annually.
- The base-case market reaches approximately $510 million-$740 million by 2028.
- Original Lamisil revenue is estimated at $60 million-$120 million annually and is likely to decline gradually.
- Oral terbinafine is generic-dominated and exposed to price compression.
- OTC topical Lamisil retains value through brand recognition, retail distribution, and convenience formats.
- Core composition, formulation, and method-of-use exclusivities no longer create a meaningful U.S. market barrier.
- Biosimilar risk does not apply because terbinafine is a small-molecule drug.
- Future value depends more on consumer marketing, channel access, and formulation differentiation than on patent protection.
Frequently Asked Questions
Is Lamisil still a profitable drug?
Lamisil can remain profitable as an OTC brand, but the original prescription franchise has limited pricing power because generic terbinafine is widely available. Profitability depends on marketing efficiency, retail placement, and manufacturing cost.
Is terbinafine a generic for Lamisil?
Yes. Terbinafine hydrochloride is the active ingredient in Lamisil. Generic terbinafine tablets and topical products compete directly with the Lamisil brand.
Will Lamisil sales grow through 2030?
The original brand is more likely to remain flat or decline modestly. The broader terbinafine market may grow at a low single-digit rate through 2030, driven by population aging and demand for fungal infection treatment.
Does Lamisil have active U.S. patent protection?
The foundational U.S. patents covering terbinafine have expired. Product-specific patents, trademarks, or later formulation rights can differ, but they do not recreate broad exclusivity for standard terbinafine tablets.
Which drug competes most directly with oral Lamisil?
Generic terbinafine is the direct competitor. Itraconazole is the principal branded or generic systemic alternative, although clinical selection depends on infection type, patient risk, drug interactions, and physician judgment.
References
- Novartis AG. (2007). Annual report 2006. https://www.novartis.com
- U.S. Food and Drug Administration. (2023). Lamisil (terbinafine hydrochloride) tablets prescribing information. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. https://www.accessdata.fda.gov/scripts/cder/daf/
- U.S. National Library of Medicine. (2024). DailyMed: Terbinafine hydrochloride labeling. https://dailymed.nlm.nih.gov/dailymed/
More… ↓
