Share This Page
Drug Sales Trends for FLOMAX
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for FLOMAX (2007)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
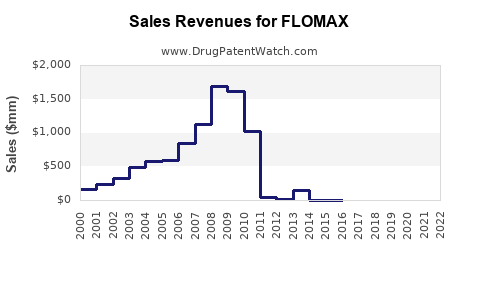
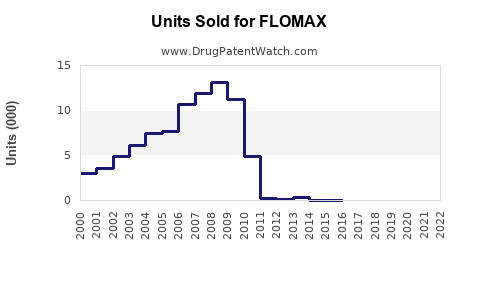
Annual Sales Revenues and Units Sold for FLOMAX
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| FLOMAX | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| FLOMAX | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| FLOMAX | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| FLOMAX | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| FLOMAX | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Flomax Market Analysis and Sales Projections: Tamsulosin, Generic Competition, and Commercial Outlook
Flomax is the original branded formulation of tamsulosin hydrochloride, an alpha-1 adrenergic receptor antagonist approved in the United States for the treatment of signs and symptoms of benign prostatic hyperplasia, or BPH. Its commercial peak has passed. U.S. and international patent barriers expired years ago, generic tamsulosin dominates volume, and current branded Flomax revenue is not separately disclosed by its commercial rights holders.
The tamsulosin market remains commercially relevant because BPH is chronic, prevalent, and treated primarily with oral medicines. Growth is driven by the aging male population and persistent diagnosis rates, but pricing pressure, generic substitution, and competition from other alpha blockers and 5-alpha-reductase inhibitors limit revenue expansion.
What is Flomax and how does it work?
Flomax contains tamsulosin hydrochloride, a selective alpha-1A and alpha-1D adrenergic receptor antagonist. It relaxes smooth muscle in the prostate and bladder neck, improving urinary flow and reducing BPH symptoms. The standard U.S. dose is 0.4 mg once daily, with an increase to 0.8 mg in selected patients who do not respond adequately to the initial dose. The product is administered orally as a modified-release capsule.
| Attribute | Flomax |
|---|---|
| Active ingredient | Tamsulosin hydrochloride |
| Therapeutic area | Benign prostatic hyperplasia |
| Drug class | Alpha-1 adrenergic receptor antagonist |
| Original U.S. sponsor | Boehringer Ingelheim |
| U.S. commercial rights history | Astellas |
| FDA approval | 1997 |
| Dosage form | Oral modified-release capsule |
| Common strength | 0.4 mg |
| Primary use | Signs and symptoms of BPH |
| Current competitive status | Generic-dominated |
The product does not reduce prostate size. Its commercial value is based on symptomatic relief, rapid use initiation, and broad prescribing familiarity rather than disease modification.
When did Flomax lose exclusivity?
Flomax lost meaningful U.S. exclusivity after the expiration of its principal patent protection and subsequent generic approvals. The brand has no current exclusivity period that protects it from ordinary generic substitution.
Flomax exclusivity timeline
| Event | Approximate date | Commercial effect |
|---|---|---|
| FDA approval for BPH | 1997 | U.S. launch |
| Peak branded adoption | Late 1990s to late 2000s | Strong cash-flow period |
| Principal U.S. patent expiry | 2009 | Generic entry became possible |
| Generic tamsulosin approvals | 2010 | Rapid price and share erosion |
| Current status | 2026 | Mature generic market |
The patent landscape included compound, formulation, and use-related protection in multiple jurisdictions. The commercial effect of those rights ended well before the current forecast period. Any remaining patent rights associated with legacy tamsulosin products would not create a material barrier to generic 0.4 mg capsule competition.
What is the FDA and Orange Book status of Flomax?
Flomax is an FDA-approved prescription product for BPH. Its regulatory significance is now historical rather than exclusivity-driven.
The FDA Orange Book is relevant because generic tamsulosin products were approved through abbreviated new drug applications, or ANDAs, referencing the branded product. Generic applicants could use Paragraph IV certifications against unexpired listed patents during the relevant period. Once the principal patents expired, ANDA applicants could proceed under ordinary patent-expiry pathways.
Orange Book and Paragraph IV implications
Flomax’s historical generic-entry process included the standard Hatch-Waxman framework:
- Generic applicants filed ANDAs referencing the Flomax product.
- Applicants certified against listed patents.
- Paragraph IV certifications could trigger patent litigation.
- Patent expiry or successful litigation outcomes opened the market.
- Multiple suppliers entered, producing rapid price erosion.
No current Paragraph IV event is expected to materially affect branded Flomax revenue because the core product is already genericized. Any new Paragraph IV litigation would more likely involve a specific formulation, combination product, or unrelated tamsulosin presentation.
How large is the tamsulosin market?
The global market consists mainly of generic tamsulosin sold under national brands, pharmacy labels, and low-cost generic names. Public market-research estimates differ materially because some reports measure tamsulosin alone, while others combine alpha blockers, BPH drugs, or lower urinary tract symptom treatments.
A reasonable commercial framing is:
- The worldwide tamsulosin market is a mature, multi-billion-dollar prescription market at retail value.
- Manufacturer net revenue is substantially lower than retail sales because of rebates, wholesaler discounts, tender pricing, and pharmacy margins.
- Tamsulosin is one of the highest-volume pharmacologic treatments for BPH.
- Branded Flomax represents a small share of current global tamsulosin volume and an even smaller share of current market revenue.
The relevant market is not a single homogeneous category. It includes:
| Segment | Principal competitors | Commercial characteristics |
|---|---|---|
| Generic tamsulosin | Teva, Viatris, Sandoz, Lupin, Dr. Reddy's, regional suppliers | Lowest price; high substitution |
| Branded tamsulosin | Flomax and country-specific brands | Residual premium pricing |
| Other alpha blockers | Uroxatral, Rapaflo, Hytrin, Cardura | Differentiated by tolerability and dosing |
| 5-alpha-reductase inhibitors | Proscar, Avodart, generics | Used when prostate enlargement is significant |
| Combination therapy | Dutasteride/tamsulosin and finasteride/tamsulosin products | Higher unit value; chronic use |
| Procedural therapies | UroLift, Rezum, TURP, laser procedures | Compete with long-term drug treatment |
What are Flomax sales and peak revenue?
Flomax generated substantial revenue before generic entry. Astellas reported Flomax among its major products during the period before loss of exclusivity. Reported sales varied by fiscal year, geography, exchange rates, and whether figures included related tamsulosin products.
The brand’s U.S. sales reached approximately the billion-dollar range during its mature branded period, based on historical company disclosures and market reports. After generic entry, the brand experienced the standard post-exclusivity pattern:
- Immediate prescription migration to generic tamsulosin.
- Declining branded volumes.
- Lower net pricing and higher rebate pressure.
- Reduced physician and pharmacy preference for the originator.
- Residual brand demand among patients who remain on the branded product or whose prescriptions are not automatically substituted.
The key analytical distinction is between historical Flomax sales and current tamsulosin-market sales. Current market growth benefits generic manufacturers, not the original Flomax brand owner.
What are the sales projections for Flomax and tamsulosin?
Branded Flomax projection
A reasonable base-case forecast for branded Flomax assumes continued erosion, no meaningful new indication, and no material restoration of exclusivity.
| Year | Estimated branded Flomax revenue index* | Expected direction |
|---|---|---|
| 2025 | 100 | Baseline |
| 2026 | 94-98 | Low-single-digit decline |
| 2027 | 88-95 | Continued substitution |
| 2028 | 82-92 | Mature residual brand |
| 2029 | 76-89 | Slow erosion |
| 2030 | 70-86 | Long-tail demand |
*Index reflects a modeled baseline because current standalone Flomax revenue is not publicly reported.
The base case assumes annual branded revenue declines of approximately 2% to 6%. A faster decline of 8% to 15% annually is possible in markets with aggressive generic substitution. A slower decline could occur where brand loyalty, reimbursement rules, or non-substitution policies remain strong.
Total tamsulosin market projection
A practical base case for total tamsulosin manufacturer revenue is low-single-digit growth through 2030, supported by patient expansion but offset by pricing pressure.
| Scenario | 2026-2030 annual revenue growth | Main assumptions |
|---|---|---|
| Downside | -2% to 0% | Heavy price erosion, lower diagnosis rates, substitution by procedures |
| Base case | 1% to 3% | Aging population offsets generic price declines |
| Upside | 3% to 5% | Greater diagnosis, broader treatment, stronger emerging-market demand |
Volume growth should exceed value growth. In many markets, prescription volume may increase by approximately 2% to 4% annually while average selling prices decline by 1% to 4% annually.
What patent protection remains for Flomax?
The practical patent estate for the original Flomax product is expired. Historical protection covered the tamsulosin molecule, pharmaceutical formulations, and methods of treating BPH-related symptoms. The principal commercial barrier was the ability to market tamsulosin in a controlled-release oral dosage form.
Formulation and manufacturing barriers
Generic manufacturers still face technical requirements, even without enforceable exclusivity:
- Demonstrating bioequivalence for the modified-release capsule.
- Controlling dissolution and release characteristics.
- Managing capsule-fill uniformity.
- Matching pharmacokinetic performance.
- Maintaining stability during storage.
- Meeting FDA current good manufacturing practice requirements.
- Avoiding manufacturing deviations and supply interruptions.
These requirements create regulatory and operational barriers, but they do not provide durable commercial protection comparable to an unexpired patent.
Which companies compete with Flomax and generic tamsulosin?
The competitive landscape is fragmented. No company has a durable monopoly in standard tamsulosin capsules.
Principal competitors
- Teva Pharmaceutical Industries
- Viatris
- Sandoz
- Lupin
- Dr. Reddy's Laboratories
- Sun Pharmaceutical Industries
- Zydus Lifesciences
- Regional generic manufacturers
- Astellas, through legacy Flomax commercialization in relevant markets
Clinical competitors include alfuzosin, silodosin, doxazosin, terazosin, finasteride, dutasteride, and combination products. Silodosin may compete on receptor selectivity, while combination therapy competes in patients with both bothersome symptoms and enlarged prostate volume.
What generic entry risks exist for Flomax?
Generic entry risk is no longer a future event. It is the core market condition.
The main commercial risks are:
- Continued automatic substitution at retail pharmacies.
- Tender-based purchasing that favors the lowest-cost supplier.
- Wholesale price compression.
- Multiple-source supply and limited differentiation.
- Pharmacy benefit manager preference for generic products.
- Prescriber movement toward combination therapy or office-based procedures.
- Manufacturing interruptions that shift share among generic suppliers.
A generic manufacturer can gain share through price, reliable supply, pharmacy contracts, and regulatory compliance. Clinical differentiation is limited for standard tamsulosin capsules.
What licensing deals and litigation affect Flomax?
Flomax’s commercial history included licensing and regional commercialization arrangements associated with tamsulosin and Astellas’s urology portfolio. Those arrangements were important during the branded period but do not materially change the current generic market structure.
Historical patent litigation centered on generic entry and the validity, scope, or infringement of tamsulosin-related patents. The economic impact of that litigation declined sharply once the principal patents expired and multiple generic products entered.
Current litigation risk is more likely to involve:
- Product liability claims.
- Manufacturing and quality disputes.
- ANDA litigation for a new dosage form.
- Trademark or trade-dress issues.
- Contract disputes between suppliers and distributors.
There is no known current litigation pathway that would restore broad exclusivity for legacy Flomax capsules.
How strong is the Flomax patent estate?
The current patent estate is commercially weak because the relevant legacy rights have expired. Historical strength was moderate to strong during the protected period because Flomax had:
- A clinically established active ingredient.
- A widely used modified-release presentation.
- Strong physician familiarity.
- Significant prescription volume.
- A long period of branded market development.
The present value of the estate is low. Any remaining opportunity would depend on a new protected product, such as a novel delivery system, fixed-dose combination, or formulation with credible clinical differentiation.
What is the revenue exposure for manufacturers and investors?
Originator exposure
Current Flomax exposure is limited. The original brand generates residual revenue but does not represent a major growth asset. Its value is primarily in legacy cash flow, brand recognition, and possible portfolio relationships.
Generic manufacturer exposure
Generic companies face a low-margin, high-volume opportunity. Revenue depends on:
- Market access and pharmacy contracts.
- Manufacturing cost.
- Supply reliability.
- Number of approved competitors.
- Country-specific reimbursement.
- Ability to avoid recalls and warning letters.
Broader BPH market exposure
The stronger commercial opportunity is in differentiated BPH products, including:
- Combination therapy.
- Long-acting delivery.
- Products with improved sexual or cardiovascular tolerability.
- Procedural alternatives.
- Therapies targeting patients inadequately controlled with alpha-blocker monotherapy.
Key Takeaways
- Flomax is the original branded tamsulosin product for BPH.
- Its U.S. patent-based exclusivity ended around the 2009-2010 period.
- Generic tamsulosin now controls most prescription volume.
- Current branded Flomax revenue is not separately disclosed and is expected to decline gradually.
- Total tamsulosin market revenue is likely to grow at approximately 1% to 3% annually through 2030 in a base-case scenario.
- Volume growth should exceed revenue growth because of generic price erosion.
- The principal competitive risks are generic substitution, combination therapy, and minimally invasive BPH procedures.
- The legacy Flomax patent estate has limited current commercial strength.
- The most valuable future IP opportunities are differentiated formulations, fixed-dose combinations, and new delivery systems.
FAQs
Is Flomax still a profitable drug?
Flomax may generate residual branded revenue, but it is no longer a high-growth branded asset. Most economic value has shifted to generic tamsulosin manufacturers.
Is tamsulosin market growth driven by price or volume?
Volume is the primary growth driver. Aging populations and continued BPH diagnosis support prescription growth, while generic competition suppresses average selling prices.
Can a company obtain new patents on tamsulosin?
New patents may be available for novel formulations, combinations, manufacturing processes, or delivery systems if they satisfy patentability requirements. They would not automatically protect standard tamsulosin capsules.
Does Flomax compete with UroLift and Rezum?
Yes. UroLift and Rezum compete with chronic drug therapy by offering office-based or minimally invasive treatment options for selected BPH patients.
What is the most attractive commercial segment related to Flomax?
Differentiated products are more attractive than standard tamsulosin capsules. Fixed-dose combinations, improved tolerability profiles, and therapies that reduce reliance on chronic medication offer stronger pricing potential.
References
-
U.S. Food and Drug Administration. (1997). Flomax (tamsulosin hydrochloride) prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: The Orange Book. FDA.
-
Astellas Pharma Inc. (2009). Annual report. Astellas Pharma Inc.
-
U.S. Food and Drug Administration. (2010). FDA approves first generic versions of Flomax. FDA.
-
American Urological Association. (2023). Benign prostatic hyperplasia clinical guideline. AUA.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: Flomax and tamsulosin hydrochloride product records. FDA.
More… ↓
