Share This Page
Drug Sales Trends for PLAVIX
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for PLAVIX (2006)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
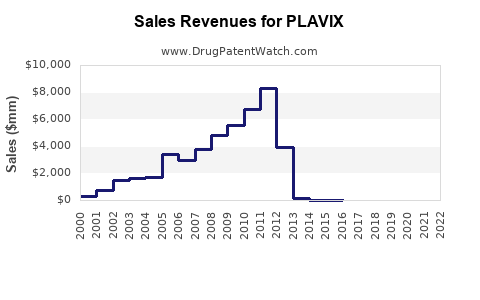
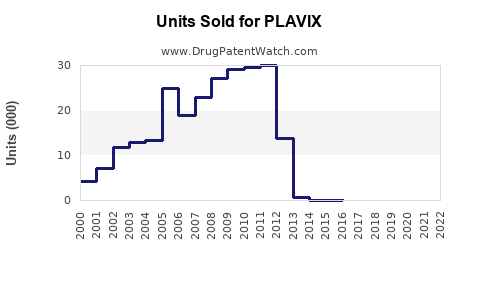
Annual Sales Revenues and Units Sold for PLAVIX
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| PLAVIX | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| PLAVIX | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| PLAVIX | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| PLAVIX | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| PLAVIX | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| PLAVIX | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Plavix Market Analysis and Sales Projections: Clopidogrel Revenue, Competition, Patents, and Generic Risk
Plavix, the branded version of clopidogrel bisulfate, has moved from a multibillion-dollar cardiovascular franchise to a mature generic market. U.S. composition-of-matter and market-exclusivity barriers expired in 2012, and generic clopidogrel is widely available. The original brand has limited commercial value, while the active ingredient retains substantial demand in antiplatelet therapy.
The key market conclusions are:
- Historical peak global sales exceeded $6 billion annually.
- U.S. generic entry in 2012 caused a rapid collapse in branded revenue.
- Current commercial value is concentrated in low-cost generic clopidogrel, not the Plavix brand.
- Ticagrelor and prasugrel compete in acute coronary syndrome, but clopidogrel remains widely used because of cost, familiarity, oral dosing, and broad guideline acceptance.
- No meaningful biosimilar risk exists because Plavix is a small-molecule drug, not a biologic.
- Future value will depend primarily on generic volume, supply reliability, hospital and government purchasing, and clinical substitution rather than patent protection.
What is Plavix and how large is its addressable market?
Plavix is clopidogrel bisulfate, an oral P2Y12 platelet inhibitor. It is used to reduce atherothrombotic events in patients with recent myocardial infarction, recent ischemic stroke, established peripheral arterial disease, and acute coronary syndrome, including patients undergoing percutaneous coronary intervention (FDA, 2024a).
Clopidogrel is generally administered at 75 mg once daily for maintenance therapy. Acute coronary syndrome protocols may use a 300 mg or 600 mg loading dose before maintenance treatment.
The addressable market includes:
- Acute coronary syndrome
- Secondary prevention after myocardial infarction
- Secondary prevention after ischemic stroke
- Peripheral arterial disease
- Dual antiplatelet therapy after coronary stenting
- Selected patients with aspirin intolerance
- Certain cerebrovascular and peripheral vascular indications
The market is large in patient volume but limited in per-patient revenue. Generic clopidogrel is inexpensive, and many patients receive treatment for defined periods rather than indefinitely. Long-term secondary prevention creates a recurring prescription base, while hospital initiation creates substantial switching between P2Y12 agents.
What were Plavix’s peak sales and historical revenue trends?
Plavix was one of the largest-selling cardiovascular products in pharmaceutical history. Bristol-Myers Squibb reported approximately $6.7 billion in worldwide Plavix sales in 2011, before broad generic erosion. Sanofi also reported Plavix as a major product in its portfolio, reflecting the co-commercialization arrangement between Sanofi and Bristol-Myers Squibb (Bristol-Myers Squibb, 2012; Sanofi, 2012).
| Period | Commercial position | Estimated revenue implication |
|---|---|---|
| 2008-2011 | Global branded growth and peak penetration | More than $6 billion annually at peak |
| 2012 | U.S. generic entry and loss of exclusivity | Rapid branded erosion |
| 2013-2015 | Broad international generic substitution | Brand revenue fell sharply |
| 2016-2020 | Mature generic market | Low brand relevance; high-volume generic use |
| 2021-2024 | Stable mature-market demand | Revenue concentrated in generics and selected international brands |
| 2025-2030 | Low-single-digit volume growth or decline | Value determined by price, access, and cardiovascular treatment volumes |
Plavix revenue did not decline because of a sudden loss of medical utility. The decline resulted from patent expiry and substitution by lower-priced clopidogrel products.
When did Plavix lose exclusivity?
U.S. market exclusivity ended in 2012. The core clopidogrel patent, U.S. Patent No. 4,847,265, covered the thienopyridine compound and was assigned to Sanofi-related entities. The patent was listed in the FDA Orange Book and expired after extensions and pediatric exclusivity in 2012.
The main exclusivity events were:
| Event | Date | Effect |
|---|---|---|
| Original U.S. approval of Plavix | 1997 | Created U.S. branded market |
| Core patent protection | Through 2012 | Delayed broad generic entry |
| FDA approval of generic clopidogrel products | 2012 | Enabled large-scale substitution |
| Pediatric exclusivity period | 2012 | Extended relevant exclusivity by six months |
| Post-2012 market | 2012 onward | Generic competition became dominant |
The Orange Book continues to identify Plavix as an approved product, but its commercial position is materially different from the protected period. Listed patents no longer prevent ordinary generic substitution where applicable patents have expired.
What patents protect Plavix and what is the current patent strength?
The historical patent estate included compound, salt, formulation, and manufacturing-related protection. The principal commercial patent was the clopidogrel compound patent.
| Patent or protection category | Historical role | Current commercial effect |
|---|---|---|
| U.S. Patent No. 4,847,265 | Covered clopidogrel-related compound claims | Expired |
| Clopidogrel bisulfate salt protection | Supported the marketed salt form | No meaningful U.S. barrier after expiry |
| Formulation patents | Covered dosage-form and excipient combinations | Limited relevance where expired or non-blocking |
| Method-of-use patents | Covered cardiovascular and antiplatelet uses | Generally difficult to enforce against approved generic labeling |
| Manufacturing patents | Covered intermediates or processes | May affect suppliers, but do not restore brand exclusivity |
The current Plavix patent estate is commercially weak in the United States. Any remaining foreign or process patents would need country-specific review and would not recreate the original U.S. franchise.
Are formulation patents still important for Plavix?
Formulation patents can matter if they cover a distinct release profile, dosage form, polymorph, or manufacturing process. Standard generic clopidogrel tablets, however, are not protected by a commercially effective U.S. formulation barrier.
Potential technical barriers include:
- Control of clopidogrel bisulfate crystal form
- Stability of the active pharmaceutical ingredient
- Tablet hardness and dissolution
- Impurity control
- Salt formation and particle-size specifications
- Bioequivalence for alternative dosage forms
These issues can affect approval timing and manufacturing cost, but they do not provide a durable franchise comparable to a valid composition-of-matter patent.
What is the FDA regulatory and Orange Book status of Plavix?
Plavix was approved by the FDA as a prescription oral antiplatelet drug. Generic clopidogrel products were approved through the abbreviated new drug application pathway under section 505(j) of the Federal Food, Drug, and Cosmetic Act.
The regulatory structure is mature:
- Reference listed drug: Plavix
- Active ingredient: clopidogrel bisulfate
- Dosage form: immediate-release tablet
- Common strengths: 75 mg and 300 mg
- Generic pathway: ANDA approval
- Therapeutic equivalence: generally available for approved generic products
- Biosimilar pathway: not applicable
Generic manufacturers must establish pharmaceutical equivalence and bioequivalence to the reference product. The principal regulatory risk is not clinical novelty but manufacturing compliance, supply continuity, data integrity, and product quality.
Which companies challenged Plavix patents?
Apotex was the most commercially significant early generic challenger. Bristol-Myers Squibb and Sanofi pursued litigation against Apotex over the clopidogrel patent. The dispute included Hatch-Waxman litigation and a settlement structure that attracted regulatory and antitrust scrutiny.
Apotex launched generic clopidogrel in the United States in 2012 after the relevant patent protection ended. Other manufacturers subsequently entered or expanded in the U.S. market, including Teva, Mylan, Dr. Reddy’s Laboratories, and additional generic suppliers.
The commercial impact of Paragraph IV activity was substantial because the challenge created a path to early generic entry and accelerated the transition from brand pricing to commodity pricing.
What patent litigation and settlement agreements affected Plavix?
The principal litigation concerned the validity and enforceability of the core clopidogrel patent. The commercial dispute was resolved through agreements that controlled the timing of generic entry before the full end of the patent term.
The Federal Trade Commission reviewed the Plavix-related settlement history in the context of reverse-payment and pharmaceutical patent-settlement enforcement. The matter became part of the broader policy debate over whether branded companies used payments or commercial arrangements to delay generic launch (Federal Trade Commission, 2013).
The litigation is no longer a current barrier to ordinary U.S. generic entry. Its relevance is historical and commercial: it delayed or structured generic competition and preserved substantial brand revenue during the protected period.
How does Plavix compare with Brilinta and Effient?
Plavix competes mainly with Brilinta and Effient in acute coronary syndrome. It also competes with aspirin, dual antiplatelet regimens, anticoagulants in selected settings, and newer procedural strategies.
| Product | Active ingredient | Main commercial advantage | Main limitation |
|---|---|---|---|
| Plavix/generic clopidogrel | Clopidogrel | Low cost, broad familiarity, once-daily dosing | Variable response linked partly to CYP2C19 metabolism |
| Brilinta | Ticagrelor | Potent, reversible P2Y12 inhibition; acute coronary syndrome positioning | Higher cost, twice-daily dosing, dyspnea and bleeding concerns |
| Effient | Prasugrel | Potent platelet inhibition in selected PCI patients | Bleeding limitations and contraindications in certain patients |
| Aspirin | Acetylsalicylic acid | Very low cost and broad use | Less complete platelet inhibition when used alone in some indications |
Ticagrelor and prasugrel can command higher prices than generic clopidogrel, particularly in hospital and acute-care settings. Their commercial penetration is constrained by cost, tolerability, bleeding risk, dosing requirements, and treatment guidelines.
Clopidogrel remains structurally advantaged in price-sensitive markets and in long-term secondary prevention.
What are the current market drivers for clopidogrel?
The main demand drivers are:
- Aging populations with coronary, cerebrovascular, and peripheral vascular disease.
- Greater survival after myocardial infarction and coronary intervention.
- Continued use of dual antiplatelet therapy after stenting.
- Expansion of cardiovascular care in emerging markets.
- Hospital formularies seeking low-cost antiplatelet options.
- Broader insurance coverage and generic substitution.
- Long-term secondary prevention in patients unable to tolerate aspirin.
The principal demand constraints are:
- Treatment-duration reductions after selected coronary interventions
- Greater use of ticagrelor or prasugrel in high-risk acute coronary syndrome
- Bleeding-related discontinuation
- Pharmacogenomic concerns involving CYP2C19 loss-of-function alleles
- Competition from alternative antithrombotic regimens
- Lower diagnosis and treatment rates in underdeveloped healthcare systems
What are the sales projections for Plavix and generic clopidogrel?
No single current public revenue line captures global Plavix and generic clopidogrel sales across all manufacturers. The appropriate projection is a scenario model that separates the residual branded product from the broader active-ingredient market.
Branded Plavix projection
| Year | Base-case branded sales index, 2024 = 100 | Expected trend |
|---|---|---|
| 2024 | 100 | Residual brand sales in selected markets |
| 2025 | 92 | Continued substitution and tender pressure |
| 2026 | 84 | Declining brand prescriptions |
| 2027 | 77 | Brand retained mainly for preference, reimbursement, or local availability |
| 2028 | 70 | Further erosion |
| 2029 | 64 | Low-value mature brand |
| 2030 | 58 | Declining but persistent niche sales |
This implies a base-case branded revenue compound annual growth rate of approximately negative 8% to negative 9% from 2024 through 2030.
Generic clopidogrel projection
| Scenario | 2024-2030 volume CAGR | 2024-2030 price trend | Revenue outcome |
|---|---|---|---|
| Downside | -2% to 0% | -5% to -8% annually | Material revenue contraction |
| Base case | 1% to 3% | -2% to -4% annually | Flat to modest decline |
| Upside | 3% to 5% | Stable in regulated markets | Low- to mid-single-digit growth |
The base case assumes patient volumes rise modestly while generic prices continue to decline. Revenue growth is therefore weaker than prescription growth.
For an investor or manufacturer, generic clopidogrel is a volume-and-efficiency market. Gross margins depend on plant utilization, procurement scale, active pharmaceutical ingredient costs, regulatory compliance, and access to government or hospital tenders.
What generic launch scenarios exist for Plavix?
The primary U.S. generic launch scenario has already occurred. Future commercial outcomes are more likely to involve supplier expansion, contract wins, or temporary shortages than a new patent-driven launch event.
Base case
Generic suppliers maintain broad availability. Brand sales decline gradually, and generic prices remain under pressure. Clopidogrel retains a stable role in outpatient secondary prevention.
Upside case
Cardiovascular patient volumes increase, emerging-market access expands, and clopidogrel gains use in cost-sensitive formularies. Supply consolidation allows reliable manufacturers to improve utilization and protect margins.
Downside case
Treatment durations shorten, ticagrelor and prasugrel gain share in acute coronary syndrome, and generic price competition intensifies. Manufacturer exits or quality issues could create temporary shortages without increasing long-term market value.
What licensing deals and commercial arrangements affect Plavix?
The core commercial arrangement was the co-development and co-commercialization relationship between Sanofi and Bristol-Myers Squibb. The companies jointly commercialized Plavix in major markets, with regional arrangements governing promotion, sales, and economics.
The market no longer depends on a major new licensing deal. Future transactions would more likely involve:
- Regional brand rights
- Generic distribution
- Authorized generic supply
- API sourcing
- Hospital and government tenders
- Portfolio acquisitions by generic manufacturers
The brand’s low exclusivity value reduces the economic rationale for large upfront licensing payments.
What is the revenue exposure for manufacturers?
The revenue profile differs by participant:
| Participant | Revenue exposure | Strategic issue |
|---|---|---|
| Sanofi and Bristol-Myers Squibb | Residual branded sales | Limited growth and ongoing substitution |
| Large generic manufacturers | High-volume, low-price sales | Scale, compliance, and tender access |
| API manufacturers | Ingredient demand across multiple suppliers | Price competition and geographic concentration |
| Hospitals and payers | Drug-budget savings | Product availability and quality |
| Cardiovascular specialists | Clinical choice among P2Y12 agents | Balance between efficacy, bleeding, genotype, and cost |
For the original brand owners, Plavix is no longer a material growth asset. For generic manufacturers, the product can remain commercially useful as part of a broad cardiovascular portfolio, but it is unlikely to justify a stand-alone premium valuation.
How strong is the Plavix patent estate compared with newer drugs?
Plavix has a weak current patent estate because its principal U.S. exclusivity has expired. Newer agents such as ticagrelor historically had more recent composition-of-matter and formulation protection, allowing higher branded pricing and greater commercial differentiation.
| Attribute | Plavix/clopidogrel | Brilinta/ticagrelor | Effient/prasugrel |
|---|---|---|---|
| Patent position | Expired in major markets | More recent historical protection | Expired or mature in major markets |
| Generic competition | Extensive | Increasing as protection expires by market | Extensive |
| Pricing power | Very low | Higher during protected period | Moderate during protected period |
| Long-term volume | High | Lower than clopidogrel in many markets | Lower |
| Commercial risk | Price erosion | Patent expiry and clinical substitution | Price erosion and limited population |
What geographic markets remain attractive?
The most attractive geographic opportunities are markets where:
- Cardiovascular disease prevalence is increasing.
- Generic penetration remains incomplete.
- Public procurement is expanding.
- Local manufacturing or registration creates an access advantage.
- Brand trust or supply reliability supports a modest premium.
The United States and Western Europe are mature and price-sensitive. Growth opportunities are more likely in Asia-Pacific, Latin America, the Middle East, and selected African markets, although regulatory registration, tender pricing, local competition, and supply-chain requirements reduce margins.
Key Takeaways
- Plavix generated more than $6 billion in annual sales at its peak.
- U.S. exclusivity ended in 2012, and generic clopidogrel now dominates the market.
- The current Plavix brand has low patent strength and declining commercial relevance.
- Clopidogrel remains clinically important because of low cost, broad familiarity, and substantial secondary-prevention use.
- Brilinta and Effient compete primarily in acute coronary syndrome and selected high-risk PCI populations.
- Generic clopidogrel volume may grow modestly through 2030, but price erosion will limit revenue growth.
- The principal commercial risks are generic oversupply, shorter treatment durations, clinical substitution, and manufacturing disruption.
- The principal opportunity is efficient, compliant supply into high-volume hospital, government, and outpatient markets.
FAQs About Plavix Market Size and Exclusivity
What is the active ingredient in Plavix?
The active ingredient is clopidogrel bisulfate, an oral P2Y12 platelet inhibitor.
Is Plavix still under patent?
The principal U.S. patents that protected Plavix have expired. Any remaining country-specific, process, or formulation rights require jurisdiction-by-jurisdiction review and do not recreate the original U.S. exclusivity position.
Is generic clopidogrel therapeutically equivalent to Plavix?
FDA-approved generic clopidogrel products are generally therapeutically equivalent to the reference product when listed as substitutable in the FDA Orange Book.
Does Plavix have biosimilar competition?
No. Clopidogrel is a chemically synthesized small molecule. It competes with generic drugs through the ANDA pathway, not biosimilars through the biologics pathway.
Will Plavix sales grow through 2030?
Branded Plavix sales are expected to decline. The broader generic clopidogrel market may maintain or modestly increase prescription volume, but continued price erosion is likely to constrain revenue growth.
References
-
Bristol-Myers Squibb. (2012). 2011 annual report. Bristol-Myers Squibb Company.
-
Federal Trade Commission. (2013). Pay-for-delay: How drug company pay-offs cost consumers billions. Federal Trade Commission.
-
Sanofi. (2012). 2011 annual report. Sanofi.
-
U.S. Food and Drug Administration. (2024a). Plavix prescribing information. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024b). Approved drug products with therapeutic equivalence evaluations: Orange Book. U.S. Department of Health and Human Services.
More… ↓