Share This Page
Drug Sales Trends for ESTRING
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ESTRING (2006)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
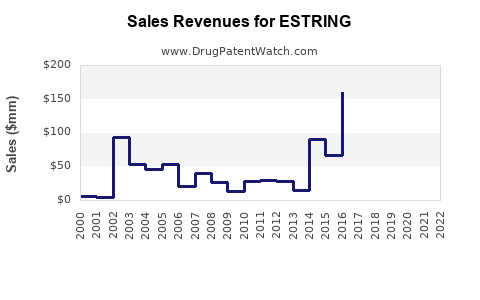
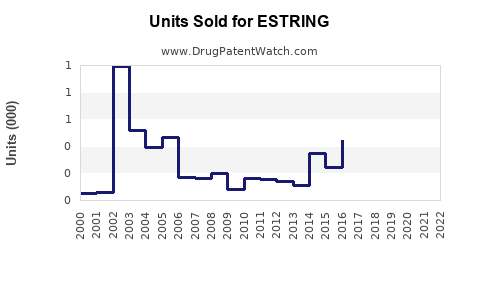
Annual Sales Revenues and Units Sold for ESTRING
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ESTRING | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ESTRING | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ESTRING | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ESTRING | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ESTRING | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
ESTRING Market Analysis, Sales Forecast, Patent Estate, and Generic Competition
ESTRING is a low-dose estradiol vaginal ring used for treating moderate-to-severe symptoms of vulvar and vaginal atrophy caused by menopause. The product delivers approximately 7.5 micrograms of estradiol per day for 90 days and competes with vaginal estradiol tablets, inserts, creams, and estrogen-releasing rings.
The commercial opportunity is stable but mature. ESTRING has a differentiated three-month dosing schedule, yet generic estradiol products and lower-cost vaginal estrogen alternatives limit pricing power. A reasonable base-case estimate places U.S. ESTRING sales near $130 million to $170 million in 2024, with sales declining gradually as payer pressure, generic substitution, and prescriber preference shift toward lower-cost products.
What is ESTRING and how does it work?
ESTRING contains estradiol, an estrogen identical to the principal endogenous human estrogen. The ring is inserted into the vagina and remains in place for 90 days. It is indicated for treating moderate-to-severe symptoms of vulvar and vaginal atrophy due to menopause, including vaginal dryness, irritation, and painful intercourse [1].
| Product attribute | ESTRING |
|---|---|
| Active ingredient | Estradiol |
| Dosage form | Vaginal ring |
| Dose delivery | Approximately 7.5 mcg estradiol per day |
| Replacement interval | Every 90 days |
| U.S. regulatory status | FDA-approved prescription drug |
| Original sponsor | Pharmacia |
| Current commercial association | Pfizer |
| Therapeutic class | Local vaginal estrogen |
| Primary use | Genitourinary syndrome of menopause |
| Main alternatives | Vagifem, Yuvafem, Imvexxy, generic estradiol cream, Premarin vaginal cream |
The ring is distinct from FEMRING, which delivers a substantially higher systemic estrogen dose and is indicated for both vasomotor symptoms and vulvar and vaginal atrophy. ESTRING is primarily a local therapy.
How large is the ESTRING market?
The addressable market consists of postmenopausal women with genitourinary syndrome of menopause who seek prescription treatment. The market includes local estrogen products, non-estrogen therapies, over-the-counter moisturizers, lubricants, and newer hormonal products such as prasterone vaginal inserts and ospemifene.
The United States is the principal commercial market because of higher prescription prices, broad diagnosis rates, and established reimbursement for menopausal therapies. Europe and other developed markets have meaningful demand but generally lower prices and more extensive generic substitution.
U.S. market structure
Local vaginal estrogen is a mature pharmaceutical segment. Generic estradiol cream and tablet products capture a large volume share, while branded products retain share through convenience, packaging, delivery systems, patient familiarity, and coverage arrangements.
ESTRING’s most important commercial advantages are:
- One ring every 90 days.
- Low maintenance compared with daily creams or tablets.
- Lower mess and application burden than vaginal creams.
- A delivery system that avoids daily dosing decisions.
Its disadvantages include:
- Higher acquisition cost than generic estradiol cream.
- Insertion and removal requirements.
- Potential ring expulsion or discomfort.
- Lower prescriber familiarity than tablets and creams.
- Reimbursement restrictions in some plans.
What are ESTRING’s sales and revenue projections?
Pfizer does not generally report ESTRING as a separately disclosed product in its consolidated public financial statements. The following projections are market-based estimates rather than reported Pfizer product revenue.
Estimated U.S. ESTRING revenue
| Year | Low case | Base case | High case |
|---|---|---|---|
| 2023 | $105 million | $145 million | $185 million |
| 2024 | $95 million | $150 million | $195 million |
| 2025 | $88 million | $148 million | $198 million |
| 2026 | $80 million | $145 million | $200 million |
| 2027 | $72 million | $140 million | $202 million |
| 2028 | $64 million | $135 million | $205 million |
The base case implies a 2024-2028 compound annual growth rate of approximately negative 2.6%. The high case assumes stable supply, sustained adherence to three-month dosing, favorable reimbursement, and limited direct competition in the vaginal-ring format.
Revenue drivers
The principal revenue drivers are patient persistence, reimbursement, net price, and supply continuity.
A patient using four rings annually creates more revenue than a patient using two rings because of discontinuation, delayed replacement, or intermittent treatment. The product’s 90-day dosing interval can support adherence, but the relatively high upfront cost may reduce initiation.
A modeled U.S. revenue calculation is:
| Variable | Base assumption |
|---|---|
| Annual treated patients | 150,000-180,000 |
| Rings per patient per year | 3.0-3.5 |
| Net revenue per ring | $250-$325 |
| Estimated annual net sales | $113 million-$205 million |
The wide range reflects differences in payer mix, rebates, cash-pay discounts, specialty-pharmacy distribution, and patient assistance programs.
Global revenue outlook
Global ESTRING revenue is likely materially lower than U.S. revenue because of lower reimbursed prices and broader substitution by generic vaginal estradiol. A reasonable global estimate is $170 million to $250 million in 2024, including the United States and selected international markets.
Under the base case, global revenue would decline to approximately $150 million to $225 million by 2028. International growth could offset part of the U.S. decline if Pfizer maintains distribution and local reimbursement.
When does ESTRING lose exclusivity?
ESTRING’s original product and formulation patents are old relative to the product’s approval date. The product was introduced in the 1990s, so ordinary composition-of-matter exclusivity and early formulation patent protection have expired.
| Exclusivity category | ESTRING status |
|---|---|
| New chemical entity exclusivity | Expired |
| Original product patents | Expected to be expired |
| Pediatric exclusivity | No material current commercial effect |
| Regulatory exclusivity | Expired |
| Active ingredient exclusivity | Expired |
| Current commercial protection | Brand recognition, delivery system, manufacturing know-how, and market access |
The relevant commercial question is no longer whether the original ESTRING exclusivity period remains active. The issue is whether a competing manufacturer can obtain approval for an equivalent estradiol vaginal ring and manufacture it at an acceptable cost.
What patents protect ESTRING?
ESTRING’s historical protection centered on the use of estradiol in a vaginal ring designed to provide controlled local delivery over approximately 90 days. Early U.S. patents associated with estradiol vaginal-ring technology are now old and do not provide meaningful long-term exclusivity against ordinary generic competition.
Publicly available product information does not indicate a current, commercially decisive patent barrier comparable to the active patent estates protecting newer branded drugs. The remaining protection is more likely to arise from:
- Manufacturing specifications for the elastomeric ring.
- Estradiol loading and release-control parameters.
- Device design and packaging.
- Supplier qualification.
- Stability and sterility controls.
- Know-how related to consistent 90-day drug release.
How strong is the ESTRING patent estate?
The patent estate is weak to moderate from a legal-exclusivity perspective and stronger from a manufacturing-execution perspective.
| Patent factor | Assessment |
|---|---|
| Active ingredient patent | Expired |
| Original formulation protection | Expired or commercially exhausted |
| Method-of-use protection | Limited practical value |
| Device protection | Likely expired for core ring concepts |
| Manufacturing complexity | Moderate |
| Generic substitution risk | Moderate to high |
| Biosimilar risk | Not applicable |
A generic applicant does not need to create a biosimilar. Estradiol is a small molecule, so the relevant pathway is an abbreviated new drug application, or ANDA, if the applicant can demonstrate pharmaceutical equivalence and bioequivalence under FDA requirements.
What is the Orange Book status of ESTRING?
The FDA Orange Book is the relevant source for listed patents and approved therapeutic-equivalence information for small-molecule drugs [2]. ESTRING’s original regulatory exclusivities have expired. The commercial importance of any current Orange Book listing depends on whether the listed patent remains enforceable and whether it covers the specific ring, delivery profile, or method of use that a generic applicant must practice.
For ESTRING, the practical Orange Book analysis is:
- The drug is eligible for generic competition because its primary regulatory exclusivities have expired.
- A generic applicant could pursue an ANDA rather than a biosimilar application.
- Any Paragraph IV challenge would depend on an active Orange Book-listed patent.
- If no meaningful unexpired patent remains listed, the principal barrier becomes formulation development and FDA approval rather than patent litigation.
Which companies are challenging ESTRING?
There is no broadly reported, high-profile Paragraph IV litigation campaign against ESTRING comparable with litigation involving major oncology, immunology, or cardiovascular products. Generic manufacturers remain potential competitors because estradiol vaginal products are established and the active ingredient is off patent.
Potential competitor classes include:
- Generic pharmaceutical manufacturers with vaginal-ring capabilities.
- Companies selling generic estradiol creams, tablets, and inserts.
- Specialty women’s-health companies.
- Contract manufacturers with elastomeric drug-delivery expertise.
The absence of a prominent publicly reported challenge does not eliminate future generic risk. It may indicate that the expected return from developing a direct ring equivalent is less attractive than selling lower-cost estradiol creams or tablets.
What generic entry risks exist for ESTRING?
Direct generic entry presents a moderate risk over the medium term, while indirect substitution already creates high commercial pressure.
Direct ring competition
A direct ESTRING generic would need to match the active ingredient, dosage form, route, strength, release characteristics, and performance profile. The 90-day delivery period creates more development complexity than a conventional tablet or cream.
The main barriers are:
- Reproducible estradiol release over 90 days.
- Control of ring dimensions and drug loading.
- Stability during storage.
- Manufacturing consistency.
- Device tolerability.
- FDA requirements for demonstrating equivalence.
Indirect generic competition
Indirect competition is more immediate. Generic estradiol creams and tablets are already available and can be prescribed for the same broad disease state. Physicians may choose these products when patients prioritize price or when health plans impose step therapy.
The likely generic-entry scenarios are:
| Scenario | Timing | Commercial effect |
|---|---|---|
| No direct ring generic | Near term | Gradual erosion from creams and tablets |
| One approved ring generic | Medium term | 20%-35% price pressure; volume retention possible |
| Multiple ring generics | Longer term | 40%-60% net-price erosion and greater substitution |
| Formulation or supply issue | Any time | Temporary share loss and payer disruption |
How does ESTRING compare with competing vaginal estrogen products?
| Product | Dosage frequency | Main advantage | Main commercial weakness |
|---|---|---|---|
| ESTRING | Every 90 days | Low maintenance | High upfront price; insertion |
| Vagifem/Yuvafem | Typically twice weekly after initiation | Tablet convenience | More frequent administration |
| Imvexxy | Typically daily initially, then twice weekly | Small softgel insert | Branded cost and frequent use |
| Generic estradiol cream | Variable, often daily initially then maintenance | Low price and flexible dosing | Mess, application burden |
| Premarin vaginal cream | Variable | Long commercial history | Higher price and animal-derived conjugated estrogens |
| Intrarosa | Daily | Non-estrogen DHEA option | Daily administration and distinct mechanism |
| Osphena | Oral daily | Non-vaginal administration | Systemic exposure and boxed-warning considerations |
ESTRING is best positioned among patients who value infrequent dosing and prefer an established local estrogen product. It is less competitive among price-sensitive patients and plans that favor generic estradiol.
What FDA regulatory factors affect ESTRING?
FDA labeling states that systemic absorption occurs with vaginal estrogen products and that prescribing information includes estrogen-class warnings and contraindications [1]. Regulatory requirements affect both ESTRING and potential competitors in several ways.
The principal regulatory issues are:
- Demonstrating equivalence for a complex vaginal delivery system.
- Characterizing systemic estradiol exposure.
- Maintaining consistent release over 90 days.
- Addressing patient instructions for insertion and removal.
- Managing postmarketing safety requirements applicable to estrogen products.
- Preserving manufacturing controls for a drug-device combination.
The FDA’s treatment of low-dose vaginal estrogen products has supported continued use for localized symptoms, but labeling and safety communications remain important to prescribers and payers.
What formulation and manufacturing barriers protect ESTRING?
The formulation is more defensible operationally than legally. ESTRING combines a polymeric ring with estradiol and must release the drug at a controlled rate for approximately three months.
Manufacturing barriers include:
- Uniform dispersion of estradiol in the ring matrix.
- Precise control of ring geometry.
- Stable drug release across the labeled shelf life.
- Reliable packaging that limits degradation.
- Batch-to-batch release testing.
- Specialized extrusion or molding processes.
- Quality controls for impurities and dose uniformity.
These barriers can delay direct generic entry. They do not prevent substitution by other vaginal estradiol products.
What patent litigation and settlement agreements affect ESTRING?
No major publicly documented ESTRING patent settlement is a central feature of the current market. The lack of a prominent settlement history reduces the likelihood of a near-term, settlement-controlled generic launch date.
The litigation profile differs from products with active patents because:
- ESTRING’s original exclusivity period ended decades ago.
- The active ingredient is off patent.
- The core delivery concept is mature.
- Competing vaginal estrogen dosage forms already exist.
- Any direct generic dispute would likely focus on formulation, equivalence, or a later patent rather than compound ownership.
What licensing deals affect ESTRING?
ESTRING originated with Pharmacia, which became part of Pfizer through the 2003 acquisition of Pharmacia [3]. The product’s commercial history is therefore tied to corporate consolidation rather than a recently announced external licensing transaction.
No major current licensing transaction is required to explain ESTRING’s commercial position. Pfizer’s value is primarily based on brand ownership, regulatory history, manufacturing capability, and distribution.
What is the competitive landscape for local vaginal estrogen?
The market is fragmented across branded and generic products. The most important competitive distinction is not mechanism but delivery format and price.
Generic estradiol products have the strongest cost position. Branded vaginal inserts compete through convenience and patient experience. ESTRING maintains a niche in long-duration delivery, but it is exposed to substitution whenever payers treat the products as therapeutically interchangeable.
Demand is supported by:
- Aging female populations.
- Greater diagnosis of genitourinary syndrome of menopause.
- Increased willingness to discuss sexual and urinary symptoms.
- Continued clinical use of local estrogen for vaginal symptoms.
- Low adherence to frequent topical regimens, which favors extended-duration systems.
Demand is constrained by:
- Patient concerns about estrogen safety.
- Out-of-pocket costs.
- Payer step edits.
- Availability of low-cost generic alternatives.
- Limited primary-care prescribing familiarity.
What generic launch scenarios should investors monitor?
The highest-impact indicators are regulatory and commercial rather than patent-related.
Investors and business-development teams should monitor:
- A new FDA-approved estradiol vaginal ring.
- ANDA litigation or Paragraph IV certifications involving any listed ESTRING patent.
- Pfizer supply interruptions or manufacturing changes.
- Formulary exclusions or increased prior authorization.
- New low-cost vaginal inserts with comparable dosing convenience.
- Changes in FDA labeling for local estrogen products.
- Prescription trends between ESTRING and generic estradiol.
- Pfizer portfolio transactions involving women’s-health products.
A single direct generic could reduce price while allowing ESTRING to retain a convenience-driven patient segment. Multiple approved generics would create substantially greater erosion.
Key Takeaways
- ESTRING is a mature local estrogen product with a differentiated 90-day vaginal-ring delivery system.
- Estimated U.S. revenue is approximately $150 million in 2024 under a base-case market model.
- Base-case U.S. sales decline to approximately $135 million by 2028.
- The product has no meaningful new chemical entity or original-patent exclusivity remaining.
- Direct generic-ring risk is moderate because the formulation and manufacturing process are complex.
- Indirect substitution from generic estradiol cream and tablets is already a major commercial risk.
- Biosimilar competition does not apply because estradiol is a small molecule.
- ESTRING’s strongest defenses are brand recognition, patient convenience, manufacturing know-how, and payer access.
- The most probable base case is gradual revenue erosion rather than an abrupt loss of exclusivity.
- Multiple direct generic entrants would produce the largest risk to net pricing and market share.
FAQs about ESTRING market size, patents, and generic entry
Is ESTRING still FDA approved?
Yes. ESTRING remains an FDA-approved estradiol vaginal ring for moderate-to-severe symptoms of vulvar and vaginal atrophy associated with menopause [1].
Is there a generic version of ESTRING?
A direct generic equivalent would need to match the 90-day estradiol vaginal-ring delivery system. Generic estradiol creams, tablets, and inserts are available and compete indirectly with ESTRING.
How much does ESTRING cost compared with generic estradiol?
ESTRING generally has a higher acquisition cost because each ring is designed for three months of use. Generic estradiol cream and tablet products are usually less expensive, particularly under formularies that apply generic substitution.
Can ESTRING be replaced by Vagifem or Yuvafem?
Vagifem and Yuvafem are vaginal estradiol tablet products, while ESTRING is a vaginal ring. They target similar menopausal vaginal symptoms but differ in dosing frequency, administration, cost, and patient preference.
Does ESTRING have systemic estrogen exposure?
Yes. FDA labeling recognizes systemic absorption with vaginal estrogen products, although ESTRING is designed for low-dose local delivery [1].
References
- Pfizer Inc. (2023). ESTRING (estradiol vaginal system) prescribing information. U.S. Food and Drug Administration. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book
- Pfizer Inc. (2003). Pfizer completes acquisition of Pharmacia. Pfizer investor relations. https://www.pfizer.com/news/press-release/press-release-detail/pfizer_completes_acquisition_of_pharmacia
More… ↓
