Share This Page
Drug Sales Trends for DEPAKOTE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for DEPAKOTE (2005)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
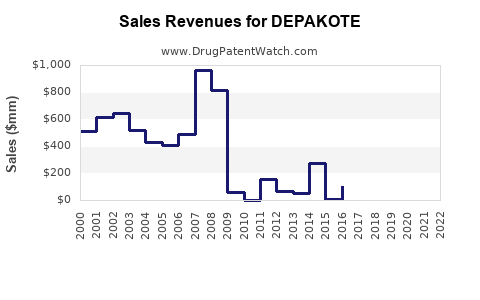
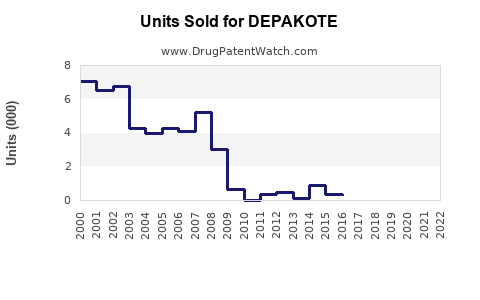
Annual Sales Revenues and Units Sold for DEPAKOTE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| DEPAKOTE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| DEPAKOTE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| DEPAKOTE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
ecutive summary: Depakote is a mature, largely genericized divalproex sodium franchise with limited remaining patent protection and declining branded commercial relevance. AbbVie does not separately disclose current Depakote revenue in a way that supports a precise brand-only forecast. A market-based model indicates U.S. branded Depakote revenue of approximately $250 million to $320 million in 2025, declining to $150 million to $220 million by 2029 under a base case. The broader divalproex market should remain materially larger, supported by chronic epilepsy treatment, bipolar disorder maintenance, and use in institutional and specialty settings.
Depakote Market Analysis and Sales Projections Through 2029
What is Depakote and which products are included in the franchise?
Depakote is the brand name for divalproex sodium, a valproate product marketed primarily by AbbVie. Divalproex sodium dissociates to valproate in the gastrointestinal tract and is used in epilepsy, acute manic or mixed episodes associated with bipolar disorder, and migraine prophylaxis.
The franchise includes several dosage forms:
| Product | Active ingredient | Primary use | Commercial status |
|---|---|---|---|
| Depakote delayed-release tablets | Divalproex sodium | Epilepsy, bipolar mania, migraine prevention | Generic competition |
| Depakote ER extended-release tablets | Divalproex sodium | Epilepsy, bipolar mania | Generic competition |
| Depakote Sprinkle Capsules | Divalproex sodium | Epilepsy, primarily patients needing administration flexibility | Generic competition |
| Depacon injection | Valproate sodium | Intravenous seizure treatment when oral therapy is impractical | Generic competition |
| Depakene | Valproic acid | Epilepsy and related valproate therapy | Separate but overlapping franchise |
The commercial analysis should distinguish branded Depakote revenue from the total divalproex market. Most prescriptions are now filled with generic divalproex sodium rather than AbbVie’s branded products.
How large is the Depakote and divalproex market?
The total divalproex market remains clinically significant but is mature and price-sensitive. Demand is driven by the number of patients requiring long-term antiseizure therapy and by continued use in bipolar disorder. Migraine prevention contributes less volume than epilepsy and psychiatric indications.
Estimated U.S. market structure
| Segment | 2025 estimated U.S. sales | Growth outlook through 2029 | Main driver |
|---|---|---|---|
| Branded Depakote and related AbbVie products | $250 million-$320 million | -5% to -8% annually | Residual brand loyalty and institutional demand |
| Generic divalproex sodium | $450 million-$650 million | 0% to 3% annually | Chronic prescription volume |
| Total oral divalproex market | $700 million-$950 million | Flat to low single-digit growth | Stable treatment population |
| Injectable valproate market | $100 million-$180 million | 1% to 4% annually | Hospital and acute-care use |
| Global divalproex and valproate market | $1.4 billion-$2.0 billion | 1% to 3% annually | Emerging-market volume and persistent clinical use |
These figures are analytical estimates rather than reported AbbVie guidance. They reflect the loss of exclusivity, generic substitution, mature prescription demand, and limited innovation in the product class.
The total valproate market is broader than Depakote because it includes divalproex sodium, valproic acid, valproate sodium, generic products, and non-U.S. brands.
What were Depakote’s historical sales?
Depakote was a major Abbott pharmaceutical product before AbbVie separated from Abbott in 2013. Reported sales declined as generic competition expanded and patent protection ended.
| Year | Reported Depakote sales | Company | Source context |
|---|---|---|---|
| 2014 | Approximately $927 million | AbbVie | Annual report product sales |
| 2015 | Approximately $731 million | AbbVie | Annual report product sales |
| 2016 | Approximately $569 million | AbbVie | Annual report product sales |
| 2017 onward | Not consistently disclosed as a standalone current franchise metric | AbbVie | Reduced reporting prominence |
The decline from 2014 through 2016 represents a compound annual decrease of approximately 22%. The principal causes were generic substitution, erosion of branded pricing power, and reduced contribution from legacy formulations.
AbbVie’s current revenue reporting is concentrated on larger growth products, including immunology, oncology, neuroscience, aesthetics, and migraine products. Depakote is no longer a core disclosed growth asset.
What are the Depakote sales projections for 2025 through 2029?
The base-case forecast assumes continued generic substitution, stable clinical demand, modest price erosion, and no major withdrawal from the market.
U.S. branded Depakote revenue forecast
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2025 | $230 million | $285 million | $325 million |
| 2026 | $210 million | $265 million | $315 million |
| 2027 | $190 million | $245 million | $305 million |
| 2028 | $170 million | $225 million | $295 million |
| 2029 | $150 million | $205 million | $285 million |
Scenario assumptions
The bear case assumes faster conversion to generic divalproex, continued payer pressure, reduced physician preference for branded products, and lower institutional purchasing.
The base case assumes a 7% annual decline in branded revenue. This reflects the behavior of mature off-patent products that retain some demand from physicians, patients, hospitals, and pharmacies but have limited pricing leverage.
The bull case assumes slower brand erosion caused by supply disruptions among generic manufacturers, persistent demand for specific dosage forms, and stable institutional contracts. It does not assume a return to exclusivity or material price increases.
Total U.S. divalproex market forecast
| Year | Estimated total U.S. market |
|---|---|
| 2025 | $700 million-$950 million |
| 2026 | $710 million-$970 million |
| 2027 | $720 million-$990 million |
| 2028 | $730 million-$1.01 billion |
| 2029 | $740 million-$1.03 billion |
The total market can remain stable while branded Depakote declines because generic manufacturers capture a larger share of prescriptions and maintain lower prices.
When did Depakote lose exclusivity?
Depakote has lost the exclusivity characteristics associated with a protected innovative product. The key formulations have faced generic competition for many years, and the original compound, delayed-release, extended-release, and sprinkle products do not provide a credible basis for a new period of market exclusivity.
| Protection category | Commercial implication |
|---|---|
| Original valproate and divalproex patents | Expired or commercially exhausted |
| Delayed-release tablet protection | Generic competition established |
| Extended-release formulation protection | Generic competition established |
| Sprinkle capsule protection | Generic competition established |
| Orphan-drug exclusivity | No current exclusivity relevant to ordinary Depakote sales |
| Pediatric exclusivity | Historical, not commercially blocking today |
| Data exclusivity | Expired |
| Regulatory exclusivity | No current blocking period identified |
A generic applicant does not need to overcome a meaningful remaining Depakote patent barrier for ordinary entry. Market access is primarily a regulatory, manufacturing, supply, and commercial execution issue.
What is the FDA regulatory status of Depakote?
Depakote is FDA-approved for:
- Complex partial seizures, either alone or with other seizure types.
- Absence seizures, alone or with other seizure types.
- Manic episodes associated with bipolar disorder.
- Prevention of migraine headaches.
Depakote is not approved for acute treatment of migraine pain. Its migraine indication is preventive.
Valproate products carry major safety restrictions. The FDA labeling includes boxed warnings for hepatotoxicity, fetal risk, and pancreatitis. Valproate exposure during pregnancy is associated with neural tube defects and other adverse developmental outcomes. These risks affect prescribing, patient counseling, reproductive-health restrictions, and long-term market demand.
The safety profile can favor competing antiseizure or migraine-prevention products when clinical alternatives are suitable. It also limits use in women of childbearing potential and creates additional monitoring requirements.
What patents protect Depakote and are any Orange Book barriers remaining?
The commercial patent estate is weak because the main product patents and formulation protections have already been exposed to generic competition. The Orange Book historically included patents associated with Depakote formulations and related products, but those listings do not create a current, durable barrier comparable to a newly launched branded medicine.
The relevant intellectual-property categories were:
- Divalproex sodium composition and pharmaceutical forms.
- Enteric-coated delayed-release tablets.
- Extended-release dosage forms.
- Sprinkle capsules.
- Manufacturing and formulation processes.
- Labeling and method-of-use claims.
Method-of-use patents have limited practical value when the approved indications are longstanding, generic labels are available, and prescribing can occur under established clinical practice. Formulation patents also have reduced value when multiple generic dosage forms have been approved.
No current Paragraph IV challenge is commercially central to the Depakote franchise. The important generic litigation cycle occurred during the earlier loss-of-exclusivity period. Current competition is better analyzed through generic approvals, pricing, supply reliability, and channel share than through pending patent litigation.
Which companies compete with Depakote?
Competition occurs at both the molecule level and the therapeutic-class level.
Generic divalproex competitors
Generic competition includes manufacturers of delayed-release tablets, extended-release tablets, and sprinkle capsules. The specific supplier mix changes over time because generic manufacturers enter, exit, consolidate, or experience manufacturing disruptions.
Generic products compete primarily on:
- Wholesale acquisition cost.
- Pharmacy benefit manager formulary position.
- Supply reliability.
- Dosage-form availability.
- Product quality and regulatory compliance.
- Hospital and institutional contracts.
Therapeutic alternatives
| Therapy | Main competitive area | Relative commercial effect |
|---|---|---|
| Levetiracetam | Epilepsy | Strong substitution option with broad use |
| Lamotrigine | Epilepsy and bipolar maintenance | Important alternative, especially in selected psychiatric patients |
| Topiramate | Epilepsy and migraine prevention | Competes in both major non-psychiatric uses |
| Carbamazepine | Epilepsy and bipolar disorder | Older alternative with drug-interaction limitations |
| Lithium | Bipolar disorder | Competes mainly in mood stabilization |
| Atypical antipsychotics | Bipolar mania and maintenance | Major competition in psychiatric treatment |
| CGRP-targeted therapies | Migraine prevention | Reduces valproate use in eligible migraine patients |
Levetiracetam and lamotrigine are the most important epilepsy alternatives in many prescribing settings. In bipolar disorder, lithium and atypical antipsychotics compete more directly than newer antiseizure drugs. In migraine, CGRP monoclonal antibodies and oral CGRP antagonists have expanded treatment choices, although their higher cost can preserve a role for generic valproate.
What generic entry risks affect Depakote sales?
The principal risk is continued branded-to-generic conversion rather than a single future launch event.
High-probability risks
- Further pharmacy substitution for Depakote delayed-release tablets.
- Reduced reimbursement for branded extended-release products.
- Payer-mandated step therapy involving generic antiseizure drugs.
- Generic entry or re-entry in under-supplied dosage forms.
- Hospital purchasing based on lowest-cost injectable valproate.
- Physician migration toward levetiracetam, lamotrigine, or newer migraine agents.
- Lower use in women of reproductive potential because of fetal-risk concerns.
Offsetting factors
- Long-established clinical familiarity.
- Availability of multiple dosage forms.
- Low generic cost and broad reimbursement.
- Continued need for seizure control in chronic patients.
- Use in patients who are stable on existing therapy.
- Institutional demand for oral and intravenous valproate.
How strong is the Depakote patent estate?
The estate is weak from a new-product investment perspective but still has residual defensive value around manufacturing, trademarks, regulatory know-how, and selected formulation claims.
| Factor | Assessment |
|---|---|
| Remaining exclusivity | Low |
| Generic blocking power | Low |
| Formulation differentiation | Low to moderate |
| Manufacturing complexity | Low to moderate |
| Regulatory switching friction | Moderate |
| Trademark value | Moderate in legacy channels |
| Pricing power | Low |
| Litigation leverage | Low |
| Long-term growth potential | Low |
Divalproex is not a biologic and has no biosimilar risk. Its competitive exposure is conventional generic substitution. Manufacturing barriers are also limited relative to complex injectables, long-acting products, or biologics, although quality controls and supply continuity remain operational concerns.
What is the commercial outlook for Depakote?
Depakote is likely to remain a cash-generating but declining legacy franchise. Its value is based on residual volume, not innovation or patent exclusivity.
The most probable commercial path is:
- Branded revenue continues to decline at a mid-single-digit to high-single-digit rate.
- Generic divalproex captures most prescription growth.
- Total molecule demand remains broadly stable.
- Newer epilepsy, bipolar, and migraine products take selected patients.
- Safety restrictions limit expansion in reproductive-age populations.
- Product-specific supply reliability determines short-term share changes.
- AbbVie’s strategic focus remains outside Depakote.
A buyer or licensee would need to value Depakote as a mature cash-flow asset with limited upside. The principal diligence priorities would be net pricing, channel mix, generic substitution, manufacturing costs, product liability exposure, regulatory compliance, and the remaining customer base.
Key takeaways
- Depakote is a mature divalproex sodium franchise with extensive generic competition.
- Estimated U.S. branded revenue is approximately $250 million to $320 million in 2025.
- Base-case branded revenue declines to approximately $205 million by 2029.
- The broader U.S. divalproex market is estimated at $700 million to $950 million in 2025 and should remain broadly stable.
- Depakote has no meaningful current patent or regulatory exclusivity supporting a new generic-entry barrier.
- Generic divalproex, levetiracetam, lamotrigine, lithium, atypical antipsychotics, and newer migraine therapies are the principal competitive threats.
- The main commercial risk is continued generic substitution, not Paragraph IV litigation.
- Safety restrictions, particularly fetal-risk warnings, constrain prescribing and future growth.
FAQs about Depakote market size, patents, and future sales
Is Depakote still profitable for AbbVie?
Depakote can remain profitable because manufacturing and commercial costs are lower for a mature product, but it is no longer a principal AbbVie growth driver. Current standalone brand profitability is not publicly disclosed.
Will generic Depakote reduce the price of divalproex sodium?
Yes. Generic substitution places sustained pressure on branded pricing and typically shifts prescription volume toward lower-cost manufacturers. The effect is strongest where pharmacy benefit managers impose mandatory substitution.
Can Depakote sales grow through new indications?
Meaningful indication-driven growth is unlikely without new clinical evidence, label expansion, or a reformulated product with differentiated safety or adherence benefits. The core indications are longstanding.
Does Depakote face biosimilar competition?
No. Depakote is a small-molecule drug, not a biologic. Its competitive risk comes from traditional generic manufacturers.
Is Depakote a takeover or licensing target?
It is more likely to attract buyers seeking mature branded cash flow, established distribution, or selected dosage-form rights than buyers seeking a high-growth pharmaceutical asset. Valuation would depend heavily on remaining net sales, liability reserves, manufacturing economics, and generic share.
References
-
AbbVie Inc. (2015). 2014 annual report. AbbVie Inc.
-
AbbVie Inc. (2016). 2015 annual report. AbbVie Inc.
-
AbbVie Inc. (2017). 2016 annual report. AbbVie Inc.
-
U.S. Food and Drug Administration. (2024). Depakote prescribing information. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Valproate information. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. U.S. Department of Health and Human Services.
More… ↓
