Share This Page
Drug Sales Trends for ZOFRAN
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ZOFRAN (2004)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
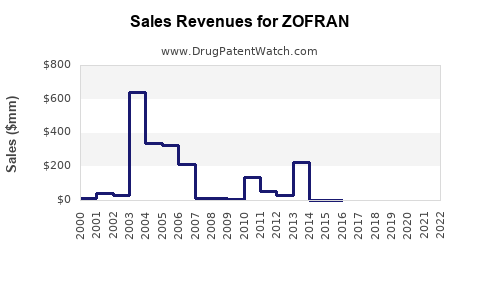
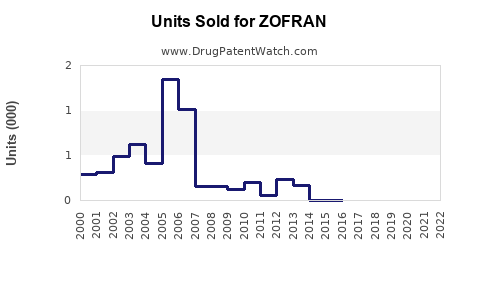
Annual Sales Revenues and Units Sold for ZOFRAN
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ZOFRAN | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ZOFRAN | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ZOFRAN | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ZOFRAN | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ZOFRAN | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ZOFRAN | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Zofran Market Analysis and Sales Projections: Ondansetron Generics, Demand, Pricing, and Patent Status
Zofran is the original branded formulation of ondansetron, a 5-HT3 receptor antagonist used to prevent nausea and vomiting associated with chemotherapy, radiotherapy, surgery, and other clinical settings. The product has lost U.S. market exclusivity. Commercial value is now concentrated in generic ondansetron tablets, orally disintegrating tablets, oral solution, and injection rather than the Zofran brand.
The market outlook is stable in volume and declining in price. A reasonable base case is low-single-digit annual unit growth with flat-to-declining market revenue through 2030, subject to hospital purchasing, injectable supply conditions, and demand in oncology and perioperative care.
What is Zofran and how is ondansetron used?
Zofran contains ondansetron hydrochloride, an antiemetic that blocks serotonin 5-HT3 receptors. FDA-approved uses include:
- Prevention of nausea and vomiting associated with highly emetogenic cancer chemotherapy
- Prevention of nausea and vomiting associated with radiotherapy
- Prevention of postoperative nausea and vomiting
- Pediatric use in selected indications and dosage forms
Ondansetron is available in several dosage forms:
| Dosage form | Primary market | Commercial status |
|---|---|---|
| Immediate-release tablets | Retail and institutional | Generic |
| Orally disintegrating tablets | Retail, outpatient, emergency care | Generic |
| Oral solution | Pediatric and selected outpatient use | Generic |
| Injection | Hospitals, surgery centers, oncology | Generic |
| Branded Zofran tablets and ODT | Historical branded market | Largely displaced by generics |
The product is often prescribed off-label for nausea and vomiting related to gastroenteritis, pregnancy, migraine, and other conditions. Those uses contribute to demand but are not equivalent to FDA-approved indications.
What is the current market status of Zofran?
The current market is a mature generic market, not a conventional branded pharmaceutical market. GlaxoSmithKline originally commercialized Zofran, but patent expiry enabled multiple generic manufacturers to enter the U.S. market. FDA-approved generic products are listed in the Orange Book under ondansetron dosage forms and strengths [1].
Brand-level Zofran sales are no longer a reliable measure of ondansetron demand. The relevant commercial metrics are:
- Total prescriptions and hospital units
- Generic net price per unit
- Injectable contract volume
- Dosage-form mix
- Manufacturer supply reliability
- Formulary position and wholesaler share
Retail demand is relatively price-sensitive because multiple generic suppliers compete. Hospital injectable demand is more exposed to shortages, purchasing contracts, and manufacturing interruptions.
When did Zofran lose exclusivity?
Zofran’s primary U.S. composition-of-matter patent expired in the mid-2000s. FDA approval of ondansetron occurred in 1991, and generic competition followed after expiration of the principal patent and related regulatory exclusivities [1][2].
| Milestone | Approximate timing | Commercial effect |
|---|---|---|
| Original U.S. approval | 1991 | Launch of branded ondansetron |
| Core patent protection | Through the mid-2000s | Protected branded pricing |
| Generic entry | Mid-2000s | Rapid price erosion |
| Mature generic market | 2010s onward | High supplier competition |
| Current position | 2020s | Low brand relevance; generic-driven volume |
Exact patent protection depended on dosage form, patent listing, pediatric exclusivity, and market segment. The commercial loss of exclusivity occurred more than a decade ago, eliminating the basis for a conventional branded Zofran forecast.
What patents protect Zofran and ondansetron?
The principal patent estate protected the ondansetron active ingredient and related pharmaceutical compositions. Historical U.S. patent protection included patents associated with ondansetron and its use as an antiemetic. The main commercial patent barrier has expired.
Current patent risk is limited compared with products that have active formulation or device estates. Potentially relevant protections can still arise from:
- New combinations
- Novel dosing regimens
- Abuse-deterrent or modified-release systems
- Drug-device configurations
- Manufacturing processes
- New therapeutic indications
These rights would not restore broad exclusivity for standard ondansetron tablets or injection unless they covered a commercially important product and were enforceable against the relevant generic product.
What is the Orange Book status of Zofran?
FDA’s Orange Book lists approved ondansetron products and associated patents or exclusivity information where applicable [1]. The historical Zofran listings include multiple dosage forms and strengths.
The Orange Book is important for determining:
- Whether a listed patent remains active
- Whether an ANDA applicant may file a Paragraph IV certification
- Whether a generic product has an approved dosage form
- Whether a listed patent applies to tablets, ODT, oral solution, or injection
- Whether pediatric or other regulatory exclusivity remains
Because the central Zofran exclusivity period has expired, current generic competition is governed primarily by ANDA approvals, manufacturing economics, procurement contracts, and supply availability.
Which companies compete in the ondansetron market?
The market has included large generic manufacturers and specialty suppliers such as:
- Teva Pharmaceutical Industries
- Sandoz
- Hikma Pharmaceuticals
- Fresenius Kabi
- Pfizer, including hospital injectable operations
- Amneal Pharmaceuticals
- Rising Pharmaceuticals
- Dr. Reddy’s Laboratories
- Cipla
- Aurobindo Pharma
- Viatris and related legacy Mylan operations
Supplier participation varies by dosage form and jurisdiction. Injectable ondansetron is more concentrated than oral tablets because sterile manufacturing requires higher capital investment, regulatory compliance, and supply-chain controls.
How large is the Zofran and ondansetron market?
Public companies generally do not report ondansetron revenue as a separate line item. The molecule is sold across multiple generic labels, channels, and countries. As a result, a precise global market size cannot be derived from branded-company financial statements alone.
The market has three economically distinct segments:
| Segment | Demand profile | Pricing profile | Outlook |
|---|---|---|---|
| Retail oral tablets | Broad outpatient use | Highly competitive | Stable volume, declining price |
| ODT products | Convenience and pediatric use | Moderate generic competition | Stable to modest growth |
| Hospital injection | Surgery, oncology, emergency care | Contract-driven | Stable demand, supply-sensitive |
On a volume basis, ondansetron remains commercially durable because it is inexpensive, familiar to clinicians, available in several formulations, and used in high-frequency care settings. On a revenue basis, the market is materially smaller than during the branded Zofran period.
What are the sales projections for Zofran and generic ondansetron?
The following forecast applies to the U.S. ondansetron market rather than the discontinued or largely inactive branded Zofran business. It uses an indexed 2024 market revenue base of 100 because manufacturers do not disclose a consolidated ondansetron revenue figure.
| Year | Base-case market index | Unit-volume growth | Price trend | Market interpretation |
|---|---|---|---|---|
| 2024 | 100 | Base year | Base year | Mature generic market |
| 2025 | 99 | 1% to 2% | -2% to -4% | Continued generic price pressure |
| 2026 | 98 | 1% to 2% | -2% to -4% | Stable demand, lower net price |
| 2027 | 97 | 0% to 2% | -2% to -3% | Mature market conditions |
| 2028 | 96 | 0% to 2% | -1% to -3% | Limited revenue expansion |
| 2029 | 95 | 0% to 2% | -1% to -3% | Injectable supply may affect pricing |
| 2030 | 94 | 0% to 2% | -1% to -3% | Long-term revenue erosion |
Scenario analysis
| Scenario | 2030 revenue index | Assumptions |
|---|---|---|
| Downside | 80-88 | Aggressive price competition, additional suppliers, stable clinical demand |
| Base case | 90-98 | Low unit growth and continued annual price erosion |
| Upside | 105-115 | Injectable shortages, higher hospital pricing, expanded global demand, or new formulation adoption |
The branded Zofran business is expected to remain commercially immaterial relative to generic ondansetron. Any residual brand revenue would likely come from limited institutional contracts, legacy prescribing, or non-U.S. markets.
What factors will drive ondansetron sales through 2030?
Oncology and radiotherapy demand
Chemotherapy and radiotherapy remain core demand drivers. Growth in cancer incidence can support antiemetic volume, although newer antiemetic regimens may reduce reliance on ondansetron as a sole agent.
Surgical procedures
Postoperative nausea and vomiting prevention supports hospital and ambulatory surgery demand. Growth in outpatient procedures can increase use of injectable and orally administered antiemetics.
Pediatric and outpatient use
The ODT and oral-solution formats remain relevant in pediatric care and settings where swallowing tablets is difficult. Formulation convenience can support price premiums, but generic competition limits the magnitude of those premiums.
Hospital shortages
Shortages of injectable antiemetics can produce temporary price increases and supplier substitutions. These effects are usually episodic and do not create durable branded exclusivity.
Generic procurement
Large wholesalers, group purchasing organizations, hospitals, and retail pharmacies generally prioritize price, supply continuity, regulatory compliance, and product availability. Brand loyalty is weak.
What generic entry risks exist for Zofran?
Generic entry risk is no longer a future event. It has already occurred and reshaped the market. The relevant risks now concern additional competition and substitution:
- New ANDA approvals can reduce prices
- Hospital contracts can shift volume rapidly
- Retail pharmacies can substitute among approved suppliers
- Injectable products face manufacturing and inspection risk
- One supplier’s shortage can temporarily benefit competitors
- ODT products may retain modest pricing differentiation
- International markets may have different patent and regulatory timelines
A new generic entrant would face low clinical-development risk but meaningful manufacturing, distribution, and procurement barriers.
How strong is the remaining Zofran patent estate?
The remaining estate is weak for standard ondansetron products because the principal patent protection expired years ago. Patent strength is better characterized by product segment:
| Product area | Current patent strength | Commercial barrier |
|---|---|---|
| Standard tablet | Low | Generic competition |
| Standard ODT | Low to moderate | Formulation and regulatory execution |
| Oral solution | Low | Manufacturing and distribution |
| Injection | Low to moderate | Sterile manufacturing and supply reliability |
| New combination product | Potentially moderate | Depends on claim scope and validity |
| New method of use | Potentially moderate | Enforcement and prescribing behavior |
A patent covering a narrow method of use would have limited commercial value unless it materially changed prescribing or was tied to an FDA-approved labeling indication.
What litigation or Paragraph IV activity affects Zofran?
The major legal event was the historical generic challenge and subsequent market entry after expiry of core patent protection. There is no current, widely recognized patent dispute that restores exclusivity for standard Zofran products in the U.S.
Paragraph IV risk is therefore most relevant to future reformulations or new ondansetron products, not the established generic market. A new Paragraph IV case would need to target an active listed patent, and the commercial value would depend on whether the patent covers a meaningful share of prescriptions.
What is the regulatory status of ondansetron?
Ondansetron is FDA-approved and available through both NDA and ANDA pathways. Generic products must demonstrate pharmaceutical equivalence and bioequivalence to the applicable reference product. FDA approval does not prevent substitution among therapeutically equivalent products where state pharmacy rules and payer policies permit it [1][3].
The product is not a biologic, so biosimilar regulation is not applicable. Competitive entry occurs through the generic-drug pathway rather than the biosimilar pathway.
How does Zofran compare with competing antiemetics?
| Product | Class | Main competitive position |
|---|---|---|
| Ondansetron | 5-HT3 antagonist | Low cost, broad familiarity |
| Granisetron | 5-HT3 antagonist | Alternative dosing and formulation options |
| Palonosetron | Long-acting 5-HT3 antagonist | Longer duration; stronger specialty positioning |
| Aprepitant and fosaprepitant | NK1 antagonists | Used in combination for higher-risk chemotherapy |
| Olanzapine | Antipsychotic used as antiemetic | Increasing role in selected oncology regimens |
| Metoclopramide | Dopamine antagonist/prokinetic | Lower-cost alternative in selected settings |
| Promethazine | Antihistamine/phenothiazine | Broad antiemetic use with different safety profile |
Ondansetron remains competitive where low acquisition cost, predictable tolerability, and flexible dosage forms matter. It is less differentiated in high-risk chemotherapy, where multi-drug antiemetic regimens and longer-acting agents are used.
What is the investment outlook for Zofran?
Zofran is not an attractive branded-product growth asset. The investment case is a mature generic supply opportunity, particularly in:
- Injectable manufacturing
- Hospital contract supply
- Reliable sterile production
- Multi-product generic portfolios
- Geographic markets with limited competition
- ODT and pediatric dosage-form capabilities
Revenue growth is constrained by price erosion. Margin performance depends more on manufacturing efficiency, capacity utilization, shortage conditions, and contract discipline than on patent protection.
Key Takeaways
- Zofran is the historical brand for ondansetron, a mature generic antiemetic.
- U.S. exclusivity ended in the mid-2000s.
- The commercial market now consists mainly of generic tablets, ODT, oral solution, and injection.
- Brand Zofran revenue is expected to remain immaterial relative to total ondansetron volume.
- Base-case market revenue is likely to decline at a low-single-digit annual rate through 2030.
- Injectable ondansetron has stronger supply and manufacturing barriers than oral products.
- Patent strength is low for standard products and potentially higher only for narrow new formulations or uses.
- No biosimilar pathway applies because ondansetron is a small-molecule drug.
- The primary commercial risks are price erosion, procurement pressure, and manufacturing interruptions.
FAQs
Is Zofran still sold as a brand-name drug?
Brand-name Zofran has been largely displaced by generic ondansetron in the U.S. Availability and marketing status can differ by dosage form and country.
Is ondansetron more profitable as a tablet or injection?
Injectable ondansetron can offer stronger supply-based economics because sterile manufacturing limits the number of qualified suppliers. Tablets face more intense generic price competition.
Does Zofran have remaining patent protection?
The core patent protection that supported branded Zofran sales expired years ago. Any remaining rights would generally relate to narrow formulations, methods, or jurisdictions rather than standard ondansetron products.
Can a new company launch a generic Zofran product?
A company can seek FDA approval through the ANDA pathway if it satisfies applicable pharmaceutical-equivalence, bioequivalence, manufacturing, labeling, and regulatory requirements. Commercial success would depend on pricing and supply reliability.
Will ondansetron sales grow with cancer incidence?
Cancer incidence can increase demand for antiemetics, but ondansetron volume growth may be moderated by combination regimens, newer long-acting agents, treatment changes, and generic price erosion.
References
- U.S. Food and Drug Administration. (n.d.). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
- U.S. Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
- U.S. Food and Drug Administration. (2014). Approved drug products with therapeutic equivalence evaluations. FDA.
- GlaxoSmithKline plc. (Various years). Annual reports and financial statements.
- National Cancer Institute. (n.d.). Nausea and vomiting related to cancer treatment. https://www.cancer.gov/
More… ↓
