Drug Sales Trends for ARIPIPRAZOLE
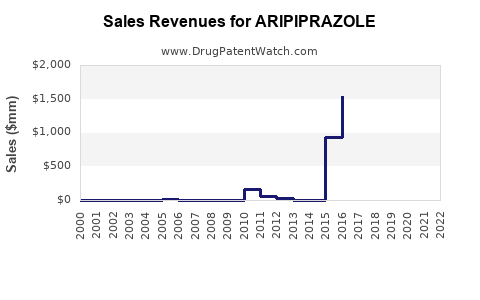
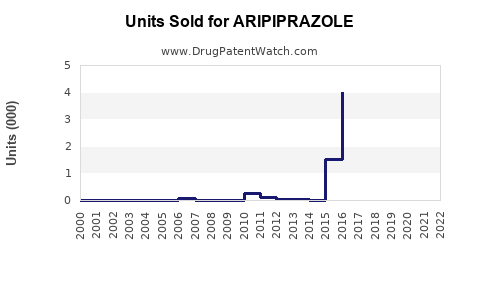
Annual Sales Revenues and Units Sold for ARIPIPRAZOLE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ARIPIPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ARIPIPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ARIPIPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ARIPIPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ARIPIPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ARIPIPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| ARIPIPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Aripiprazole Market Analysis, Sales Forecast, Patent Status, and Competitive Outlook
Aripiprazole is a mature, high-volume antipsychotic with a bifurcated market: low-priced generic oral products generate most prescriptions, while branded long-acting injectable products retain substantial revenue through formulation, delivery, and adherence advantages. Global aripiprazole sales are estimated at approximately $2.2 billion to $2.7 billion in 2024, with branded long-acting injectables accounting for an increasing share of value. The global market is projected to reach approximately $3.0 billion to $3.8 billion by 2029 under a base-case scenario.
The main commercial products are oral aripiprazole, Abilify Maintena, Abilify Asimtufii, and Aristada, which contains the prodrug aripiprazole lauroxil. Oral aripiprazole faces minimal patent-driven entry risk. Long-acting injectable products have stronger formulation and device protection but face competition from other depot antipsychotics and future generic or follow-on injectable products.
What is the current aripiprazole market size?
Aripiprazole is used primarily for schizophrenia, bipolar I disorder, adjunctive treatment of major depressive disorder, irritability associated with autistic disorder, and Tourette's disorder. The commercial market divides into four segments:
| Segment | Principal products | 2024 estimated global revenue | Market position |
|---|---|---|---|
| Generic oral tablets and orally disintegrating tablets | Multiple generic manufacturers | $0.7B-$1.0B | Dominates prescription volume |
| Branded oral aripiprazole | Limited branded supply and selected markets | Less than $0.1B | Small and declining |
| Abilify Maintena | Aripiprazole monohydrate once-monthly injection | $1.0B-$1.3B | Leading branded value segment |
| Abilify Asimtufii | Aripiprazole monohydrate two-month injection | $0.2B-$0.4B | Fast-growing newer formulation |
| Aristada | Aripiprazole lauroxil extended-release injection | $0.3B-$0.5B | Main branded competitor |
These figures are market-analysis estimates rather than reported consolidated product sales. Public companies do not consistently disclose global net sales for all aripiprazole presentations, and generic revenue is fragmented across manufacturers.
The United States is the largest value market because of higher reimbursement for long-acting injectable antipsychotics. Europe has substantial generic oral volume but lower average selling prices. Japan and other Asian markets are more dependent on local reimbursement, regulatory approvals, and branded or authorized-generic supply.
What are the aripiprazole sales projections through 2029?
The base case assumes continued growth in long-acting injectable use, stable oral prescription volume, declining oral prices, and gradual expansion of two-month dosing.
| Year | Estimated global market revenue | Growth versus prior year | Main driver |
|---|---|---|---|
| 2024 | $2.2B-$2.7B | - | Established oral and injectable base |
| 2025 | $2.3B-$2.9B | 3%-7% | Growth in Maintena, Asimtufii, and Aristada |
| 2026 | $2.4B-$3.1B | 3%-7% | Greater use of depot therapy after oral stabilization |
| 2027 | $2.6B-$3.3B | 4%-7% | Two-month dosing and adherence programs |
| 2028 | $2.7B-$3.6B | 3%-7% | Injectable market expansion offsets oral price erosion |
| 2029 | $3.0B-$3.8B | 4%-7% | Higher injectable penetration and geographic expansion |
Base-case revenue mix in 2029
- Generic and branded oral products: approximately 25% to 35% of market revenue.
- Abilify Maintena: approximately 30% to 35%.
- Abilify Asimtufii: approximately 12% to 18%.
- Aristada: approximately 12% to 18%.
- Other formulations and regional products: approximately 5% to 10%.
The most important assumption is that injectable products continue taking share of commercial value even if oral aripiprazole remains the largest source of prescriptions. Long-acting therapy produces higher revenue per treated patient because of administration fees, specialty pharmacy economics, reimbursement differences, and lower treatment discontinuation in selected populations.
How much revenue did Abilify generate before generic competition?
Abilify was one of the largest-selling atypical antipsychotics before oral generic entry. Worldwide sales reached approximately $7 billion at peak, supported by schizophrenia, bipolar disorder, adjunctive depression, and pediatric indications. The product was commercialized by Otsuka Pharmaceutical and Bristol-Myers Squibb under a collaboration arrangement.
Generic oral aripiprazole entered the United States in 2015 after settlement and regulatory developments surrounding the primary compound patent. Revenue declined sharply after loss of exclusivity, although the active ingredient retained substantial prescription volume.
The commercial transition followed a standard pattern:
- Branded oral sales contracted rapidly after generic launch.
- Generic prescriptions expanded because aripiprazole became a preferred low-cost atypical antipsychotic.
- Otsuka shifted commercial emphasis toward long-acting injectable formulations.
- Depot products preserved a higher-value branded market despite mature oral competition.
When does aripiprazole lose exclusivity?
The principal composition-of-matter protection for aripiprazole expired in the United States before generic oral launch.
| Protection or exclusivity | Product or scope | Approximate U.S. status |
|---|---|---|
| U.S. Patent No. 5,006,528 | Aripiprazole compound | Expired in 2015, after pediatric extension |
| Abilify oral exclusivity | Oral tablets and related dosage forms | Generic entry began in 2015 |
| Abilify Maintena patents | Aripiprazole monohydrate depot formulation and manufacturing | Later-expiring formulation protection; expiration varies by patent and jurisdiction |
| Abilify Asimtufii patents | Two-month injectable formulation and dosing regimen | Later-expiring formulation and method claims |
| Aristada patents | Aripiprazole lauroxil prodrug, injectable suspension, and dosing system | Separate estate from oral aripiprazole |
The oral market therefore has no meaningful compound-patent barrier. The principal protection for branded products now lies in injectable formulation patents, manufacturing processes, dosing regimens, device claims, and regulatory exclusivity.
Current Orange Book listings should be evaluated patent by patent because listed patents, pediatric extensions, terminal disclaimers, and litigation outcomes can change the practical entry date. The core patent number historically associated with Abilify is U.S. Patent No. 5,006,528, assigned to Otsuka Pharmaceutical and covering the aripiprazole compound (U.S. Patent and Trademark Office, 1991).
What is the Orange Book status of Abilify Maintena and Abilify Asimtufii?
Abilify Maintena is FDA-approved as an extended-release injectable suspension of aripiprazole for schizophrenia and maintenance monotherapy of bipolar I disorder. Abilify Asimtufii is a two-month formulation approved for schizophrenia and maintenance monotherapy of bipolar I disorder in adults who are clinically stable on aripiprazole therapy (U.S. Food and Drug Administration, 2023a, 2023b).
The commercial relevance of the Orange Book differs by product:
- Oral Abilify has substantial generic competition and limited remaining patent leverage.
- Abilify Maintena has formulation and manufacturing protection that can delay direct generic injectable competition.
- Abilify Asimtufii has newer formulation and dosing claims that support a longer period of branded exclusivity.
- A competitor may seek approval through a 505(b)(2) pathway rather than a conventional ANDA if it relies on a different formulation, delivery system, or clinical bridging strategy.
Orange Book litigation risk is therefore more material for the injectable products than for oral aripiprazole.
What patents protect aripiprazole long-acting injectables?
The long-acting injectable patent estates generally address four technical areas:
Formulation patents
These claims cover particle size, crystal form, suspension characteristics, excipients, release kinetics, concentration, and stability. Formulation claims can block a substantially similar generic suspension even when the active ingredient is off patent.
Manufacturing patents
Manufacturing claims may cover micronization, milling, sterilization, aseptic filling, suspension preparation, and control of particle-size distribution. These claims can increase development cost and complicate technology transfer.
Method-of-use patents
Claims may cover monthly or two-month administration, maintenance treatment, conversion from oral therapy, injection intervals, and patient populations. Method-of-use protection is commercially relevant where a generic applicant must carve out protected indications.
Device and administration patents
Prefilled syringes, injection kits, needle configurations, reconstitution systems, and administration procedures can create additional barriers. Device claims are more important for products requiring specialized administration than for ordinary tablets.
The strongest estate is generally the estate that combines formulation, manufacturing, dosing, and device claims. A single narrow formulation patent is more vulnerable to design-around than a layered estate covering the full product platform.
Which companies are challenging aripiprazole products?
Generic competition is extensive for oral aripiprazole. Manufacturers include Teva, Sandoz, Dr. Reddy's Laboratories, Aurobindo, Zydus, Torrent, and other regional suppliers. The generic oral market is highly price-sensitive and has relatively low entry barriers once bioequivalence is established.
The injectable market has fewer participants. Otsuka retains the Abilify franchise, while Alkermes commercializes Aristada. Potential challengers include specialty injectable manufacturers, complex-generic developers, and companies pursuing 505(b)(2) products. Publicly visible competitive activity has been more concentrated on product development and commercial contracting than on a large wave of launched generic injectables.
What is the FDA regulatory status of aripiprazole?
The FDA has approved multiple aripiprazole dosage forms and delivery systems:
| Product | Active ingredient | FDA pathway or status |
|---|---|---|
| Abilify tablets and oral solution | Aripiprazole | Original NDA; generic ANDA competition |
| Abilify Discmelt | Aripiprazole | Orally disintegrating tablet |
| Abilify Maintena | Aripiprazole monohydrate | Extended-release injectable suspension |
| Abilify Asimtufii | Aripiprazole monohydrate | Two-month extended-release injection |
| Aristada | Aripiprazole lauroxil | Extended-release injectable prodrug |
| Generic tablets and ODTs | Aripiprazole | ANDA-approved products |
The FDA-approved labeling for injectable products requires attention to oral tolerability, initiation procedures, injection-site administration, dosing intervals, and drug-interaction management. These requirements raise operational barriers for providers and may limit rapid substitution even where regulatory approval is obtained.
How does aripiprazole compare with competing antipsychotics?
| Product class | Examples | Competitive advantage | Commercial limitation |
|---|---|---|---|
| Oral atypical antipsychotics | Generic aripiprazole, quetiapine, risperidone, olanzapine | Low price and broad availability | Adherence and persistence problems |
| Monthly LAIs | Abilify Maintena, monthly risperidone products | Established depot workflow | Requires regular clinic administration |
| Two-month LAIs | Abilify Asimtufii, selected paliperidone products | Fewer visits and lower administration burden | Higher acquisition cost and narrower eligible population |
| Six-month LAIs | Paliperidone palmitate products | Very low administration frequency | High cost and different adverse-effect profile |
| Aripiprazole lauroxil | Aristada | Multiple dosing intervals and prodrug platform | Initiation complexity and reimbursement pressure |
Aripiprazole has a relatively favorable metabolic profile compared with several competing atypical antipsychotics, although akathisia and impulse-control concerns remain commercially and clinically relevant. Its partial dopamine agonism differentiates it from dopamine antagonists such as risperidone and paliperidone.
What generic entry risks exist for aripiprazole?
The generic oral market has three principal risks:
- Continued price erosion as suppliers compete for formulary volume.
- Manufacturing concentration that can create shortages or abrupt share shifts.
- Substitution away from branded oral products in government and managed-care channels.
The injectable market has different risks:
- A successful complex-generic or 505(b)(2) product could reduce net pricing.
- Payers may demand rebates or step therapy before covering branded LAIs.
- Competing two-month and six-month injections may limit market share.
- Provider administration capacity can constrain uptake.
- New safety or adherence data could alter treatment algorithms.
Biosimilar risk is not relevant to aripiprazole because aripiprazole is a small-molecule drug, not a biologic. The relevant regulatory risks are ANDA, 505(b)(2), formulation design-around, and patent litigation.
What patent litigation and settlement issues affect aripiprazole?
The key historical litigation issue involved generic challenges to the oral Abilify compound patent. That dispute ended with generic entry in 2015. The commercial significance of the litigation has largely passed because the composition-of-matter patent is expired.
Future litigation is more likely to involve:
- Formulation patents for Abilify Maintena.
- Two-month dosing claims for Abilify Asimtufii.
- Manufacturing and particle-size claims.
- Orange Book certification under Paragraph IV.
- Regulatory carve-outs for protected maintenance indications.
- Settlement agreements that specify launch dates, licenses, or authorized-generic rights.
A Paragraph IV filing against an injectable product would be commercially significant because it could establish the first credible pathway to direct generic competition in a higher-margin segment. The absence of a publicly material injectable generic launch does not eliminate the risk; it indicates that technical development, patent scope, reimbursement, or manufacturing economics remain barriers.
How strong is the aripiprazole patent estate?
The estate is weak for oral products and stronger for branded injectables.
| Segment | Patent strength | Commercial durability |
|---|---|---|
| Oral aripiprazole | Low | Generic competition is established |
| Abilify Maintena | Moderate to strong | Depends on surviving formulation and manufacturing claims |
| Abilify Asimtufii | Stronger than oral and newer than Maintena | Supported by dosing and formulation differentiation |
| Aristada | Moderate to strong | Separate prodrug estate with technical manufacturing barriers |
The main weakness is that the underlying molecule is mature and widely available. The main strength is that injectable delivery systems can be difficult to reproduce while maintaining equivalent pharmacokinetics, stability, sterility, and administration performance.
What are the main licensing and commercial relationships?
Otsuka Pharmaceutical developed and commercializes the Abilify franchise. Bristol-Myers Squibb was a historical commercial partner for oral Abilify. Alkermes developed and commercializes Aristada, creating a direct branded competitor based on aripiprazole lauroxil rather than aripiprazole monohydrate.
The most valuable commercial rights relate to:
- U.S. and European injectable commercialization.
- Specialty pharmacy distribution.
- Clinic administration and buy-and-bill reimbursement.
- Regional manufacturing and supply agreements.
- Authorized-generic or settlement arrangements.
- Co-development of follow-on depot formulations.
What is the likely aripiprazole launch scenario?
The base case is continued oral generic price decline with steady growth in injectable revenue. A downside case assumes faster payer substitution, a successful injectable generic, or stronger competition from long-interval paliperidone products. An upside case assumes higher adherence-driven adoption, broader use of two-month dosing, and favorable reimbursement for clinic-administered therapy.
| Scenario | 2029 global revenue | Key assumptions |
|---|---|---|
| Downside | $2.2B-$2.7B | Injectable price pressure and slower uptake |
| Base case | $3.0B-$3.8B | Injectable growth offsets oral erosion |
| Upside | $4.0B-$4.8B | Strong two-month adoption and limited direct generic competition |
The most important investment variable is not oral prescription growth. It is the durability of the branded injectable franchise and the speed at which providers and payers adopt longer dosing intervals.
Key Takeaways
- Aripiprazole is a mature molecule with an established generic oral market.
- The composition-of-matter patent expired before current commercial projections.
- Long-acting injectables represent the principal source of future market value.
- Abilify Maintena and Abilify Asimtufii have stronger commercial protection than oral aripiprazole.
- Aristada is the main branded competitor and uses the aripiprazole lauroxil prodrug.
- Global aripiprazole revenue is estimated at $2.2 billion to $2.7 billion in 2024.
- Base-case revenue is projected at $3.0 billion to $3.8 billion by 2029.
- Generic oral entry risk is high; direct injectable generic risk is lower but economically material.
- Biosimilar competition does not apply.
- Future litigation is most likely to involve injectable formulation, dosing, manufacturing, and device patents.
FAQs
Is aripiprazole still a commercially attractive drug?
Yes. Oral aripiprazole is a low-margin generic, but long-acting injectable products support higher revenue per patient and preserve commercial value.
Which aripiprazole product has the strongest growth outlook?
Abilify Asimtufii has the strongest percentage-growth outlook because two-month dosing can reduce clinic visits and improve treatment persistence.
Can a generic company copy Abilify Maintena?
A generic company can seek approval, but it must meet complex requirements for injectable formulation, pharmacokinetics, sterility, stability, and device or administration performance. Orange Book patents can create additional barriers.
Is Aristada interchangeable with Abilify Maintena?
No. Aristada contains aripiprazole lauroxil, while Abilify Maintena contains aripiprazole monohydrate. They have different initiation procedures, dosing options, formulations, and labeling.
What is the largest threat to aripiprazole sales?
The largest threat is faster-than-expected price erosion or substitution in the long-acting injectable segment. Oral generic erosion is already largely reflected in the market structure.
References
-
U.S. Food and Drug Administration. (2023a). Abilify Maintena prescribing information. FDA.
-
U.S. Food and Drug Administration. (2023b). Abilify Asimtufii prescribing information. FDA.
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Patent and Trademark Office. (1991). U.S. Patent No. 5,006,528: Quinolinone derivatives. USPTO.
-
U.S. Food and Drug Administration. (2015). FDA approves first generic versions of Abilify tablets. FDA.
-
Otsuka Pharmaceutical Co., Ltd. (2024). Annual report and financial results materials. Otsuka Pharmaceutical.
-
Alkermes plc. (2024). Annual report for the fiscal year ended December 31, 2023. Alkermes.
More… ↓
