Drug Sales Trends for HUMIRA
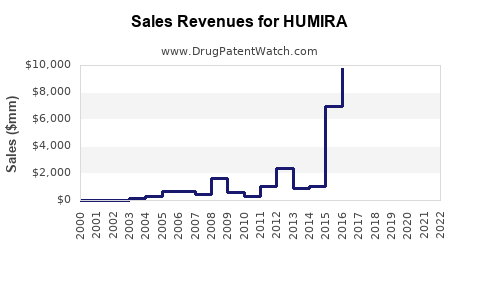
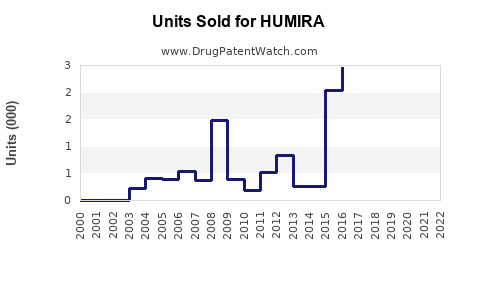
Annual Sales Revenues and Units Sold for HUMIRA
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| HUMIRA | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| HUMIRA | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| HUMIRA | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| HUMIRA | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Humira Market Analysis, Sales Projections, Patent Exclusivity, and Biosimilar Competition
Humira remains the largest biologic franchise in the anti-TNF market, but its commercial profile changed sharply after U.S. biosimilar launches in 2023. AbbVie’s global Humira revenue fell from $21.2 billion in 2022 to approximately $14.4 billion in 2023 and roughly $4.8 billion in 2024. The base-case outlook is continued annual erosion, with global sales declining below $1 billion by the end of the decade as biosimilar substitution expands and AbbVie shifts prescribing toward Skyrizi and Rinvoq.
What are Humira sales and revenue projections through 2029?
Humira is adalimumab, a fully human monoclonal antibody targeting tumor necrosis factor alpha. AbbVie markets it across rheumatoid arthritis, psoriasis, psoriatic arthritis, Crohn’s disease, ulcerative colitis, ankylosing spondylitis, hidradenitis suppurativa, uveitis and other inflammatory conditions.
Historical Humira revenue
| Year | AbbVie Humira revenue | Approximate change |
|---|---|---|
| 2021 | $20.7 billion | 7% |
| 2022 | $21.2 billion | 3% |
| 2023 | $14.4 billion | -32% |
| 2024 | Approximately $4.8 billion | Approximately -67% |
The 2021 and 2022 figures reflect the period before U.S. biosimilar commercialization. The 2023 decline began after Amgen launched Amjevita in January 2023, followed by broader biosimilar availability during the second half of the year (AbbVie, 2023, 2024).
Base-case Humira sales projection
| Year | Estimated global sales | Year-over-year change | Primary driver |
|---|---|---|---|
| 2025 | $2.7 billion | -44% | U.S. biosimilar contracting |
| 2026 | $1.8 billion | -33% | Higher payer substitution |
| 2027 | $1.3 billion | -28% | Mature biosimilar competition |
| 2028 | $1.0 billion | -23% | Residual branded use and international sales |
| 2029 | $0.8 billion | -20% | Stable maintenance demand in selected markets |
These projections are a market model rather than AbbVie guidance. The principal variables are formulary placement, Humira net pricing, biosimilar interchangeability, international tender pricing and the rate at which existing patients switch therapies.
A downside case places Humira below $500 million by 2029 if payers accelerate nonmedical switching and biosimilar manufacturers use aggressive rebates. An upside case of approximately $1.5 billion in 2029 is possible if AbbVie retains a meaningful share of U.S. commercial plans through rebates and maintains stronger-than-expected international pricing.
Why did Humira revenue decline after biosimilar entry?
The U.S. market moved from patent-protected branded biologic pricing to multi-source competition in 2023. Amgen’s Amjevita was the first U.S. adalimumab biosimilar. Other products launched during 2023, including Cyltezo, Abrilada, Hadlima, Hyrimoz, Hulio and Idacio.
Unlike small-molecule generics, biosimilar uptake is influenced by rebates, specialty-pharmacy contracts, physician prescribing, interchangeability designations and payer benefit structure. As a result, market share erosion is gradual rather than instantaneous.
Key commercial erosion factors
- Multiple biosimilar suppliers created price competition.
- Amgen’s launch established an early contracting position.
- Optum Rx, CVS Caremark and other large pharmacy-benefit managers gained leverage over rebate negotiations.
- Employers and health plans increasingly encouraged switching for chronic maintenance patients.
- AbbVie used discounts and contracting to preserve volume, which reduced net revenue per patient.
- Skyrizi and Rinvoq allowed AbbVie to retain patients within its immunology portfolio while reducing dependence on Humira.
Humira continues to have advantages in physician familiarity, global regulatory approvals, pediatric use, citrate-free delivery and extensive real-world evidence. Its primary disadvantage is that competing adalimumab products have comparable mechanisms and increasingly similar delivery options.
Which companies are challenging Humira with biosimilars?
The principal Humira biosimilar competitors are Amgen, Boehringer Ingelheim, Samsung Bioepis, Sandoz, Biocon Biologics and Celltrion.
| Biosimilar | Sponsor | FDA approval or market status | Interchangeability position |
|---|---|---|---|
| Amjevita | Amgen | Approved 2016; U.S. launch January 2023 | Not interchangeable |
| Cyltezo | Boehringer Ingelheim | Approved 2017 | Interchangeable designation |
| Abrilada | Pfizer | Approved 2019 | Interchangeable designation |
| Hadlima | Samsung Bioepis / Organon | Approved 2019 | Interchangeable designation |
| Hyrimoz | Sandoz | Approved 2018 | Interchangeable designation |
| Hulio | Biocon Biologics / Viatris | Approved 2020 | Not interchangeable at initial launch |
| Idacio | Fresenius Kabi | Approved 2022 | Not interchangeable at initial launch |
FDA approval does not guarantee rapid commercial uptake. Interchangeability permits pharmacy-level substitution where state law allows, but payer contracts remain the principal driver of market share. The Purple Book identifies approved biosimilars and interchangeable biosimilars; Humira itself is regulated as a licensed biologic rather than an Orange Book-listed small-molecule product (FDA, 2024a, 2024b).
What is the patent and exclusivity status of Humira?
Humira’s core U.S. composition patent expired in 2018, but AbbVie obtained or asserted a large secondary patent portfolio covering formulations, dosing regimens, manufacturing processes and methods of treatment.
Major Humira exclusivity milestones
| Event | Date |
|---|---|
| U.S. FDA approval | December 31, 2002 |
| U.S. 12-year biologic exclusivity expiration | December 2016 |
| Core composition patent expiration | 2018 |
| First U.S. biosimilar launch | January 2023 |
| Broad U.S. biosimilar entry | July 2023 onward |
| European biosimilar entry | 2018 onward |
The statutory biologic exclusivity period expired well before commercial biosimilar launch because patent settlements delayed entry. AbbVie negotiated launch dates with multiple biosimilar developers, generally permitting U.S. entry during 2023.
What patents protect Humira?
Representative U.S. patents historically associated with Humira include:
| Patent | General subject matter | Approximate expiration |
|---|---|---|
| U.S. Patent No. 6,090,382 | Anti-TNF antibody and related composition | 2018 |
| U.S. Patent No. 8,916,392 | Adalimumab formulation and concentration claims | 2033, subject to patent-term adjustments |
| U.S. Patent No. 8,926,975 | High-concentration, low-buffer formulation | 2034, subject to patent-term adjustments |
| U.S. Patent No. 9,017,680 | Formulation-related claims | Early-to-mid 2030s, subject to claim scope |
| Additional continuation patents | Dosing, formulations, methods and manufacturing | Dates vary by patent and claims |
The commercial value of the later patents depended on whether a biosimilar applicant used a formulation or dosing approach covered by enforceable claims. Several courts invalidated or narrowed Humira-related claims, while settlements enabled biosimilar launches before the latest asserted patent expiration dates.
What Paragraph IV challenges and litigation affected Humira?
Humira biosimilar applicants challenged AbbVie patents through the U.S. biosimilar patent dance and related litigation. AbbVie filed extensive infringement actions in federal courts against biosimilar sponsors, asserting patents covering formulation, dosing and manufacturing.
The litigation outcome was commercially important because the principal issue was not whether adalimumab could be copied after the composition patent expired. The issue was whether biosimilar products could enter before the expiration of later formulation and method patents.
Settlement structure
AbbVie entered agreements with several biosimilar developers that established negotiated U.S. launch dates in 2023. These settlements reduced immediate litigation risk for biosimilar sponsors while extending Humira’s U.S. commercial protection beyond the 2018 composition patent expiration.
The settlements did not preserve monopoly pricing. They created a staggered entry structure in which multiple products launched during the same year. That concentrated competitive pressure and accelerated net price erosion.
Patent litigation involving Humira should be analyzed at the claim level. A patent covering a specific citrate-free formulation may not block an alternative formulation. A dosing-method patent may have limited practical value if a biosimilar sponsor uses a noninfringing label or relies on physician-directed use outside the claimed method.
What is the FDA regulatory status and Orange Book status of Humira?
Humira is an FDA-approved licensed biologic. It is not evaluated through the conventional abbreviated new drug application pathway used for small-molecule generics.
The relevant FDA regulatory framework is:
- Biologics License Application No. 125057 for Humira.
- Biosimilar applications submitted under the Public Health Service Act.
- FDA Purple Book listings for approved biosimilars and interchangeable products.
- FDA interchangeability determinations for products such as Cyltezo, Abrilada and Hadlima.
- No conventional Orange Book listing for Humira as a small-molecule drug.
Humira’s extensive indication set increases the commercial value of its regulatory package. A biosimilar sponsor can obtain approval for some or all reference-product indications depending on patent, exclusivity and regulatory strategy. Extrapolation permits a biosimilar to rely on the totality of evidence rather than conducting a separate pivotal efficacy trial in every indication.
How strong is the Humira patent estate?
Humira’s patent estate was strong as a litigation and contracting asset but weaker as a long-term barrier after multiple court decisions and biosimilar settlements.
Strengths
- Large number of continuation and secondary patents.
- Multiple claim categories covering formulations and dosing.
- High commercial stakes for biosimilar applicants.
- Ability to impose litigation costs and delay launch.
- Global patent coverage that varied by country.
Weaknesses
- Core composition protection expired in 2018.
- Secondary patents faced validity and obviousness challenges.
- Biosimilar sponsors developed alternative formulations and manufacturing routes.
- Settlements established a clear launch window rather than indefinite exclusion.
- Multiple biosimilars entered the U.S. market concurrently.
The estate is best characterized as a successful launch-delay strategy rather than a durable post-2023 monopoly. Its remaining value lies in product differentiation, contracting, manufacturing know-how and residual brand loyalty.
How does Humira compare with Skyrizi and Rinvoq?
AbbVie’s commercial strategy has shifted from Humira retention to immunology franchise replacement. Skyrizi, or risankizumab, is an IL-23 inhibitor. Rinvoq, or upadacitinib, is a JAK inhibitor.
| Product | Mechanism | Key commercial role | Patent outlook |
|---|---|---|---|
| Humira | TNF inhibitor | Mature biologic facing biosimilars | Core patent expired; secondary protection largely exhausted commercially |
| Skyrizi | IL-23 inhibitor | Principal replacement growth product | Later-generation patent estate |
| Rinvoq | JAK inhibitor | Oral immunology growth product | Later exclusivity, with safety and label considerations |
Skyrizi and Rinvoq have helped offset Humira losses. AbbVie reported strong growth from both products in 2023 and 2024, reducing the company’s dependence on Humira revenue. The replacement is not one-for-one because pricing, indications, route of administration and patient populations differ.
Humira retains an advantage where physicians prefer long-established TNF inhibition, where biosimilar economics favor adalimumab, or where patients are stable on treatment. Skyrizi and Rinvoq are more important in new-start patients and in patients requiring a different mechanism after inadequate response.
What generic entry risks exist for Humira?
Humira faces biosimilar risk rather than conventional generic risk. The principal risks are:
- Rapid formulary exclusion of branded Humira.
- Rebate-driven migration to one or two preferred biosimilars.
- Interchangeable product substitution at the pharmacy level.
- Lower net pricing as sponsors compete for specialty-pharmacy access.
- International tender competition.
- Physician switching of stable patients.
- Loss of clinical trial relevance as biosimilar real-world evidence expands.
The most likely launch scenario is continued volume retention with substantial price erosion. AbbVie may preserve a smaller branded segment through contracting, patient services and supply reliability, but branded Humira is unlikely to recover pre-2023 revenue.
What is Humira’s geographic market outlook?
The United States remains the largest historical Humira market and the source of the steepest post-entry decline. Europe experienced biosimilar competition earlier, with adalimumab biosimilars available from 2018. Tender-based European markets generally produce faster price erosion than the U.S. commercial market.
Japan, Canada, Australia and other regulated markets have also experienced biosimilar competition, although timing and substitution rules differ. Emerging markets remain price-sensitive and typically do not support U.S.-level branded biologic pricing.
Geographic risk is therefore asymmetric:
| Region | Competitive intensity | Revenue outlook |
|---|---|---|
| United States | High and increasing | Sharp decline |
| Europe | Mature biosimilar market | Low residual revenue |
| Japan and Canada | Moderate to high | Continued erosion |
| Emerging markets | High price sensitivity | Limited branded growth |
What revenue exposure does Humira create for AbbVie?
Humira represented approximately 25% of AbbVie’s revenue in 2022. That percentage fell to roughly 15% in 2023 and below 10% in 2024 as Humira declined and other products grew.
The key investor issue is no longer whether Humira will decline. It is whether Skyrizi, Rinvoq and newer pipeline assets can replace the lost gross profit while maintaining AbbVie’s immunology market position. AbbVie’s replacement strategy reduces revenue concentration but increases dependence on newer products with their own clinical, regulatory and patent risks.
Key Takeaways
- Humira global revenue fell from $21.2 billion in 2022 to approximately $4.8 billion in 2024.
- U.S. biosimilar competition began in January 2023 and expanded materially in July 2023.
- Base-case sales are projected to decline below $1 billion by 2029.
- Humira’s core composition patent expired in 2018; later formulation and method patents delayed but did not prevent biosimilar entry.
- Humira is a biologic covered by the Purple Book framework, not a conventional Orange Book generic framework.
- Amgen, Boehringer Ingelheim, Pfizer, Samsung Bioepis, Sandoz, Biocon Biologics, Celltrion and Fresenius Kabi are among the principal challengers.
- AbbVie’s commercial replacement products are Skyrizi and Rinvoq.
- The remaining Humira value is concentrated in residual brand loyalty, contracting, manufacturing scale and selected international markets.
FAQs About Humira Sales, Patents, and Market Competition
When did Humira lose U.S. market exclusivity?
Humira’s 12-year U.S. biologic exclusivity expired in December 2016. Its core composition patent expired in 2018, but patent settlements delayed commercial biosimilar entry until January 2023.
Is Humira still protected by patents?
Yes, various secondary patents have expiration dates extending into the 2030s, but their practical ability to block biosimilar competition has been limited by litigation outcomes, alternative formulations and negotiated settlements.
Which Humira biosimilar has interchangeable status?
Cyltezo received an interchangeable biosimilar designation, and other adalimumab products, including Abrilada and Hadlima, also received interchangeability determinations at relevant times. Substitution remains subject to state pharmacy law and payer policy.
Will Humira sales reach zero?
No. Residual sales are likely to persist through branded contracting, physician preference, international markets, supply arrangements and patients who remain stable on existing therapy. The commercial base is expected to be substantially smaller than before biosimilar entry.
Is Humira a greater threat to biosimilars or is biosimilar competition a greater threat to Humira?
Biosimilar competition is the greater threat to Humira. The product’s clinical franchise remains relevant, but the loss of single-source pricing materially reduces revenue and profit per patient.
References
-
AbbVie Inc. (2023). 2022 annual report. AbbVie.
-
AbbVie Inc. (2024). 2023 annual report. AbbVie.
-
AbbVie Inc. (2025). 2024 annual report. AbbVie.
-
U.S. Food and Drug Administration. (2024a). Purple Book: Database of licensed biological products. U.S. Department of Health and Human Services.
-
U.S. Food and Drug Administration. (2024b). Biosimilar and interchangeable biosimilar products. U.S. Department of Health and Human Services.
-
U.S. Patent and Trademark Office. (2024). Patent examination data and patent term information. U.S. Department of Commerce.
More… ↓
