Share This Page
Drug Sales Trends for ENALAPRIL
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ENALAPRIL (2003)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
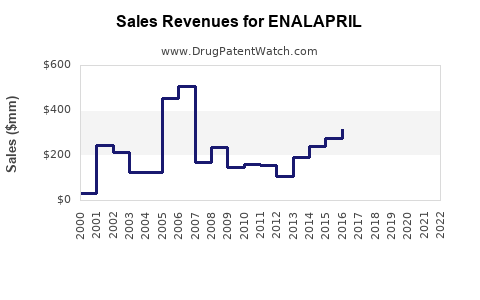
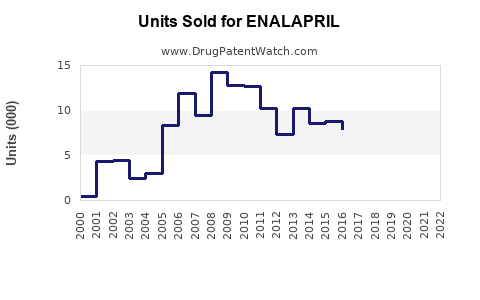
Annual Sales Revenues and Units Sold for ENALAPRIL
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ENALAPRIL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ENALAPRIL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ENALAPRIL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ENALAPRIL | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| ENALAPRIL | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| ENALAPRIL | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| ENALAPRIL | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Enalapril Market Analysis, Sales Projections, Patent Status, and Generic Competition
Enalapril is a mature, globally genericized ACE inhibitor with low prices, broad regulatory approval, and limited commercial protection. Its market is driven by prescription volume in hypertension and heart failure rather than branded pricing. Global annual sales of enalapril products are likely in the low hundreds of millions of dollars, with most revenue generated by multisource generic manufacturers. Base-case sales should decline gradually through 2030 as treatment shifts toward ARBs, ARNI therapy, SGLT2 inhibitors, and newer hypertension combinations.
What is enalapril and how is it used?
Enalapril is an oral angiotensin-converting enzyme inhibitor. Its active metabolite, enalaprilat, suppresses the renin-angiotensin-aldosterone system and reduces vasoconstriction and aldosterone secretion.
Enalapril maleate is approved for:
- Hypertension
- Symptomatic heart failure
- Asymptomatic left ventricular dysfunction in certain labeling jurisdictions
- Pediatric hypertension in approved oral formulations
The product is marketed primarily as tablets, with common strengths of 2.5 mg, 5 mg, 10 mg, and 20 mg. Enalapril is also supplied in combination with hydrochlorothiazide in several markets.
| Attribute | Enalapril |
|---|---|
| Active ingredient | Enalapril maleate |
| Drug class | ACE inhibitor |
| Original innovator | Merck & Co. |
| Original brand | Vasotec |
| Primary indications | Hypertension and heart failure |
| Common dosage forms | Immediate-release tablets; oral solutions in some markets |
| U.S. regulatory status | Generic multisource product |
| U.S. reference product | Vasotec |
| Patent position | Core composition protection expired |
| Current market structure | Highly fragmented generic market |
The FDA approved Vasotec in the mid-1980s. Enalapril has since become a low-cost alternative to branded and newer renin-angiotensin-system therapies [1].
How large is the enalapril market?
The enalapril market is substantial in unit volume but modest in revenue. It has no single global commercial owner, and public company filings generally do not report enalapril sales separately from broader generic portfolios.
A reasonable 2025 estimate for global enalapril product sales is approximately $150 million to $300 million at manufacturer revenue, including enalapril-only products and selected enalapril/hydrochlorothiazide combinations. The estimate excludes hospital procurement discounts that are not consistently disclosed and varies materially by country.
| Market | Estimated 2025 manufacturer sales | Market characteristics |
|---|---|---|
| United States | $20 million-$50 million | High prescription volume, very low generic prices |
| Europe | $40 million-$80 million | Large installed base, national tendering, price pressure |
| Japan | $15 million-$35 million | Established generic use and reimbursement controls |
| China | $25 million-$60 million | Large hypertension population and domestic manufacturing |
| Latin America | $15 million-$35 million | Retail generic and public-sector demand |
| Middle East, Africa, and other markets | $25 million-$40 million | Variable access and higher branded-generic use |
| Estimated global total | $150 million-$300 million | Directional market model |
These figures are modeled estimates rather than reported company sales. The market is difficult to measure because enalapril is sold by numerous manufacturers, frequently through tenders, and often bundled with other cardiovascular products.
What drives enalapril demand?
Demand remains supported by four factors:
- High prevalence of hypertension and heart failure.
- Low acquisition cost.
- Long clinical experience and extensive guideline familiarity.
- Continued use in markets where ARBs and newer heart-failure therapies are less affordable.
The main volume constraint is therapeutic substitution. Many physicians favor ARBs for patients who develop ACE-inhibitor cough or who have adherence issues. In heart failure with reduced ejection fraction, sacubitril/valsartan and guideline-directed combinations have taken share from ACE inhibitors in higher-income markets [2].
What are the sales projections for enalapril through 2030?
The base case is a low-single-digit annual decline in global manufacturer revenue. Volume should remain relatively stable in emerging markets, but price erosion and substitution will reduce sales value.
| Scenario | 2025 sales estimate | 2030 sales estimate | 2025-2030 CAGR | Principal assumptions |
|---|---|---|---|---|
| Bull case | $300 million | $290 million | -0.7% | Stable use in emerging markets; limited further price erosion |
| Base case | $225 million | $195 million | -2.8% | Continued generic pricing pressure and gradual class substitution |
| Bear case | $150 million | $105 million | -6.8% | Faster ARB and ARNI adoption; aggressive public tender pricing |
Base-case outlook
Under the base case, the global market declines from approximately $225 million in 2025 to approximately $195 million in 2030. Unit demand remains resilient, but average selling prices decline as more suppliers compete for tenders and pharmacy contracts.
The United States is likely to decline faster than lower-income markets because:
- Enalapril has been generic for decades.
- Retail prices are already compressed.
- ACE inhibitors face substitution by lisinopril, losartan, valsartan, and combination products.
- Heart-failure prescribing increasingly includes sacubitril/valsartan, beta blockers, mineralocorticoid receptor antagonists, and SGLT2 inhibitors.
Emerging markets should account for a growing share of global volume. That shift will not necessarily increase global revenue because pricing is lower and government procurement is concentrated.
How does enalapril compare with competing ACE inhibitors?
Enalapril competes mainly with lisinopril, captopril, ramipril, perindopril, and benazepril. Lisinopril is generally the strongest direct competitor in the United States because it has simple once-daily dosing, broad generic availability, and a large prescribing base.
| Drug | Competitive position versus enalapril | Commercial implication |
|---|---|---|
| Lisinopril | Stronger U.S. volume and broad formulary presence | Limits enalapril price and share growth |
| Losartan | ARB alternative with lower cough risk | Captures ACE-intolerant patients |
| Ramipril | Strong cardiovascular and post-event positioning in some markets | Competes in higher-value chronic treatment |
| Perindopril | Strong presence in parts of Europe and Asia | Regional share pressure |
| Captopril | Older, shorter-acting ACE inhibitor | Limited growth, still used in selected settings |
| Sacubitril/valsartan | Premium heart-failure alternative | Reduces enalapril use in eligible HFrEF patients |
| Enalapril/hydrochlorothiazide | Fixed-dose combination | Preserves some volume through convenience and tender access |
Enalapril retains a clinical role where physicians value established evidence, affordability, and availability. Its weakness is commercial differentiation. Most generic suppliers sell an essentially interchangeable product.
What patents protect enalapril?
The original enalapril composition and product patents have expired. Enalapril therefore has no meaningful U.S. composition-of-matter exclusivity.
The original innovator estate was associated with Merck’s Vasotec program and covered enalapril-related compounds, pharmaceutical compositions, and therapeutic use. The principal U.S. patent family dates to the early 1980s, including U.S. Patent No. 4,374,829. Any patent-term adjustment or regulatory extension associated with the original development period has long expired.
| Protection category | Current position |
|---|---|
| Core compound patent | Expired |
| Original product patent | Expired |
| U.S. pediatric exclusivity | No current relevance |
| Formulation exclusivity | No material broad exclusivity identified |
| Method-of-use exclusivity | No commercially blocking exclusivity |
| Generic approval pathway | Abbreviated New Drug Application |
| Biosimilar pathway | Not applicable |
What formulations are protected by enalapril patents?
No broad, commercially meaningful formulation patent is known to protect standard immediate-release enalapril tablets in the current market. Enalapril maleate tablets use conventional oral dosage technology, and manufacturers can generally compete through ANDAs or equivalent national generic pathways.
Certain companies may hold narrow patents or applications covering excipients, liquid formulations, manufacturing processes, particle characteristics, or packaging. Those rights would not recreate the original market exclusivity and are unlikely to block ordinary tablet competition across major jurisdictions.
What is the Orange Book status of enalapril?
The FDA Orange Book lists approved enalapril products and the reference-listed drug framework used for generic approval. The branded Vasotec patents are not an active barrier to ordinary generic entry.
Generic manufacturers typically rely on ANDA certifications asserting that relevant patents are expired, invalid, or not infringed. Because the core patent estate expired many years ago, the commercial significance of new Paragraph IV activity is limited.
The U.S. market includes enalapril maleate tablets and combination products containing enalapril and hydrochlorothiazide. Orange Book status can change as individual products are withdrawn, discontinued, or updated, so product-level listings should be checked against the current FDA database before transaction or litigation decisions [3].
Are there Paragraph IV challenges or generic lawsuits involving enalapril?
The principal generic challenge occurred decades ago, before the current mature market structure. Enalapril now has extensive generic competition, and the expired core patent estate does not create a meaningful basis for a new branded exclusivity strategy.
No current, commercially material Paragraph IV campaign is central to the enalapril market. Litigation risk is more likely to involve:
- ANDA product quality or manufacturing issues
- Labeling disputes
- Supply contracts
- Product liability
- Narrow process or formulation claims
- Competition-law issues in public tenders
There is no active branded settlement structure comparable to the settlements associated with recently launched specialty drugs.
What is the FDA regulatory status of enalapril?
Enalapril is an FDA-approved generic drug. Manufacturers must demonstrate pharmaceutical equivalence and bioequivalence to the reference product through the ANDA pathway. The product is not a biologic and does not face biosimilar substitution rules.
Key regulatory considerations include:
- Demonstration of bioequivalence to the reference listed drug
- Compliance with current good manufacturing practices
- Stability and impurity controls
- Control of enalaprilat-related degradation products
- Accurate labeling for hypertension and heart failure
- Pediatric labeling where applicable
- Pharmacovigilance for angioedema, hyperkalemia, renal impairment, and fetal toxicity
The principal regulatory risk is manufacturing compliance, not loss of market exclusivity. Recalls, warning letters, or supply interruptions at a major manufacturer can temporarily shift share, but they do not generally support durable price increases.
Which companies manufacture or sell enalapril?
Enalapril is supplied by a broad group of generic pharmaceutical companies. Participants vary by country and may include Teva, Sandoz, Viatris, Lupin, Zydus, Cipla, Sun Pharma, Torrent Pharmaceuticals, Aurobindo, and regional manufacturers.
Supplier concentration is higher in hospital and government channels than in retail pharmacy. A procurement winner may hold substantial country-level share for a limited contract period, but the global market remains fragmented.
Commercial success depends on:
- Low-cost active pharmaceutical ingredient supply
- Reliable tablet production
- Regulatory approvals across multiple markets
- Tender participation
- Distribution access
- Ability to supply both standalone and fixed-dose combination products
How strong is the enalapril patent estate?
The patent estate is commercially weak because its primary protection has expired and generic substitution is established.
| Patent-strength factor | Assessment |
|---|---|
| Core molecule protection | None remaining |
| Remaining term | No meaningful term |
| Generic barriers | Low |
| Manufacturing complexity | Low to moderate |
| Regulatory burden | Standard generic requirements |
| Formulation differentiation | Limited |
| Litigation leverage | Low |
| Commercial durability | Dependent on cost and supply execution |
The main defensible assets are operational rather than patent-based. These include efficient manufacturing, regulatory filings, reliable supply, local reimbursement access, and public-sector contracts.
What generic entry risks exist for enalapril?
Generic entry risk is already realized rather than prospective. Any remaining branded or premium-priced enalapril product faces four principal risks:
- Price erosion from additional suppliers.
- Substitution by lisinopril and ARBs.
- Reduced use in heart failure because of newer combination therapies.
- Tender losses caused by manufacturing or supply failures.
For a new entrant, the risk is different. The market is open but difficult to monetize. A company must reach very low cost levels or secure a differentiated channel, such as a national tender, pediatric liquid product, or combination formulation.
What is the licensing and partnership outlook?
Large-scale licensing opportunities are limited. The original innovator rights have expired, and enalapril does not normally require a novel technology license.
Potential transactions would more likely involve:
- Regional commercialization rights
- Contract manufacturing
- API supply agreements
- Fixed-dose combination products
- Pediatric oral solutions
- Portfolio acquisitions involving multiple cardiovascular generics
The economic value of an enalapril license is usually tied to distribution rights and manufacturing cost, not intellectual-property exclusivity.
What are the key investment conclusions?
Enalapril is a stable, low-growth generic with predictable clinical demand and weak pricing power. It can support a broad cardiovascular portfolio, but it is unlikely to produce material standalone growth absent a low-cost manufacturing advantage or a strong regional tender position.
The base-case market declines at approximately 2.8% annually through 2030. Revenue exposure is concentrated in countries with large treated hypertension populations, while profit exposure is concentrated in manufacturers with low production costs and reliable government-channel access.
Key Takeaways
- Enalapril is a mature generic ACE inhibitor with no meaningful remaining composition-of-matter exclusivity.
- Estimated global manufacturer sales are approximately $150 million to $300 million in 2025.
- Base-case global sales are projected to decline from approximately $225 million in 2025 to $195 million in 2030.
- The U.S. market is commercially mature and highly price-sensitive.
- Emerging markets should preserve volume but will not fully offset price erosion.
- Lisinopril, losartan, ramipril, and sacubitril/valsartan are the main competitive pressures.
- There is no material current Paragraph IV or branded settlement opportunity.
- Biosimilar risk is irrelevant because enalapril is a small-molecule drug.
- The strongest commercial assets are manufacturing efficiency, supply reliability, and local tender access.
- Enalapril is strategically useful as a portfolio product but has limited standalone investment appeal.
Frequently Asked Questions
Is enalapril still profitable for generic manufacturers?
Yes, but profitability depends on manufacturing cost, procurement access, and scale. Standard retail sales have limited margins because multiple suppliers compete on price.
Will enalapril sales increase in developing countries?
Unit volume may increase in some developing markets as hypertension treatment expands. Revenue growth is less likely because public procurement and generic pricing keep average selling prices low.
Does enalapril have pediatric market potential?
Pediatric demand is limited but can support niche products, particularly oral solutions or age-appropriate dosage forms. The opportunity is regulatory and distribution-driven rather than patent-driven.
Can a company obtain market exclusivity for a new enalapril formulation?
A narrow formulation may qualify for patent protection if it contains a genuinely novel and non-obvious technical feature. That protection would not automatically block conventional enalapril tablets.
Is enalapril a biosimilar product?
No. Enalapril is a chemically synthesized small molecule approved through generic-drug pathways, not through the FDA biosimilar pathway.
References
- U.S. Food and Drug Administration. (n.d.). Vasotec (enalapril maleate) prescribing information. FDA.
- Heidenreich, P. A., Bozkurt, B., Aguilar, D., et al. (2022). 2022 AHA/ACC/HFSA guideline for the management of heart failure. Circulation, 145(18), e895-e1032.
- U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
- National Library of Medicine. (n.d.). DailyMed: Enalapril maleate. U.S. National Library of Medicine.
- World Health Organization. (2021). Guideline for the pharmacological treatment of hypertension in adults. World Health Organization.
More… ↓
