Share This Page
Drug Sales Trends for UCERIS
✉ Email this page to a colleague
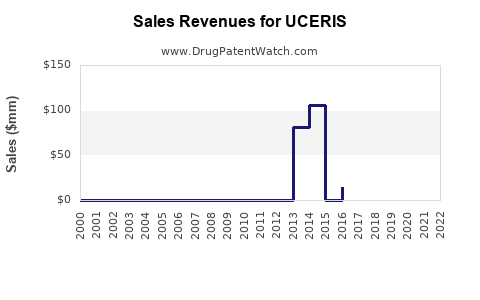
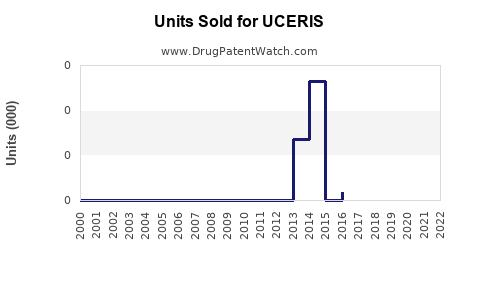
Annual Sales Revenues and Units Sold for UCERIS
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| UCERIS | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| UCERIS | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| UCERIS | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| UCERIS | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| UCERIS | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
UCERIS Market Analysis, Sales Projections, Patent Position, and Generic Competition
UCERIS is the brand name for budesonide in two ulcerative-colitis formulations: a 9 mg extended-release oral tablet and a 2 mg rectal foam. The product is commercially mature. Its principal growth constraint is generic substitution, while its main defense is clinical positioning in mild-to-moderate ulcerative colitis patients who need corticosteroid induction but not systemic prednisone exposure.
The U.S. UCERIS market is likely to remain commercially relevant through 2030, but value will shift from branded tablets to lower-priced generic budesonide extended-release products. A reasonable base-case estimate places total U.S. budesonide MMX and rectal-foam sales at approximately $180 million to $240 million annually during 2025-2030, with brand sales declining and generic sales capturing most prescription volume.
What is UCERIS and how is it used?
UCERIS contains budesonide, a locally acting corticosteroid designed to release in the colon. The oral tablet uses MMX extended-release technology to deliver budesonide throughout the colon. The foam formulation delivers budesonide directly to the rectum and sigmoid colon.
| Product | Active ingredient | Dose | FDA indication | Primary use |
|---|---|---|---|---|
| UCERIS tablets | Budesonide | 9 mg once daily | Induction of remission in mild-to-moderate active ulcerative colitis | Oral induction therapy |
| UCERIS rectal foam | Budesonide | 2 mg per actuation | Induction of remission in mild-to-moderate active ulcerative proctitis or proctosigmoiditis | Local rectal therapy |
UCERIS is not generally positioned as a long-term maintenance treatment. The oral product is typically prescribed for up to eight weeks, while the foam is generally used for six to eight weeks depending on clinical response and labeling.
The product competes with mesalamine, prednisone, other corticosteroids, immunomodulators, biologics, and small-molecule therapies. Its strongest commercial position is between 5-aminosalicylate therapy and advanced systemic treatments.
What is the FDA regulatory status of UCERIS?
UCERIS tablets received FDA approval in January 2013 for induction of remission in adults with active, mild-to-moderate ulcerative colitis. UCERIS foam received FDA approval in October 2014 for induction of remission in adults with active mild-to-moderate ulcerative proctitis or proctosigmoiditis.[1][2]
FDA milestones
| Event | Date |
|---|---|
| UCERIS oral tablets approved | January 2013 |
| UCERIS rectal foam approved | October 2014 |
| Oral budesonide MMX generic competition | Emerged after expiration or loss of enforceable blocking patents |
| Brand market phase | Mature, with declining exclusivity and increased substitution |
UCERIS is an abbreviated new drug application, or ANDA, target for generic manufacturers because budesonide is a small molecule and the products are not biologics. Biosimilar approval is therefore not relevant.
What patents protect UCERIS?
UCERIS protection has historically involved patents covering budesonide controlled-release compositions, MMX delivery technology, dosage forms, and methods of treating ulcerative colitis.
The key intellectual-property value is concentrated in the delivery system rather than in budesonide itself. Budesonide is an established corticosteroid, and composition-of-matter protection is no longer available.
Patent categories
| Patent category | Commercial relevance |
|---|---|
| Budesonide active ingredient | Expired; no remaining composition-of-matter protection |
| Extended-release tablet formulation | Protects oral colon-targeted delivery |
| MMX matrix technology | May create formulation and manufacturing barriers |
| Rectal foam formulation | Protects dosage form, propellant system, and delivery characteristics |
| Method-of-use patents | May cover induction treatment in ulcerative colitis |
| Manufacturing patents | Can complicate exact replication of coating, granulation, and release profiles |
The Orange Book is the operative source for listed UCERIS patents and associated exclusivity. Patent listings can differ by dosage form and can change after regulatory or litigation events.[3]
When does UCERIS lose exclusivity?
UCERIS has already passed the period of traditional FDA market exclusivity for both major formulations. The commercial exclusivity question is now determined by enforceable formulation patents, paragraph IV litigation, settlements, and the availability of approved generics.
Exclusivity outlook
| Exclusivity element | Current commercial effect |
|---|---|
| New chemical entity exclusivity | Expired |
| Orphan-drug exclusivity | Not applicable |
| Pediatric exclusivity | Not a principal current barrier |
| Oral tablet patents | Reduced by generic entry and patent challenges |
| Rectal foam patents | More commercially significant if generic competition remains limited |
| Brand exclusivity | Eroding through generic substitution |
The oral tablet faces the greater generic risk because it has a larger patient population, clearer prescribing role, and more straightforward pharmacy substitution economics. Rectal foam may retain stronger pricing if fewer manufacturers enter and if substitution requires more active prescriber or payer intervention.
How many patents cover UCERIS?
The practical answer depends on the formulation and the Orange Book update used. UCERIS protection has not been based on one patent alone. It has included multiple patents related to controlled-release budesonide compositions, delivery matrices, and treatment methods.
A patent-count approach can overstate commercial protection. A formulation patent may have limited value if:
- A generic can design around the claimed matrix.
- The patent is not listed for the relevant dosage form.
- The patent expires before regulatory approval.
- The patent is challenged under Paragraph IV.
- The generic obtains a label that omits a protected method of use.
The strongest remaining barriers are those that combine a listed patent, a narrow formulation claim, and a realistic infringement theory against the ANDA product.
Which companies are challenging UCERIS?
Generic competition has involved ANDA applicants targeting budesonide extended-release tablets and, separately, rectal-foam products. The competitive field has included large generic manufacturers and specialty pharmaceutical companies with gastrointestinal portfolios.
Publicly available litigation and regulatory records should be evaluated by product strength, dosage form, ANDA applicant, and litigation outcome. A company challenging the oral tablet does not automatically challenge the foam, because the formulation, delivery route, and patent claims differ.
Paragraph IV risk
Paragraph IV challenges create four possible outcomes:
| Outcome | Effect on UCERIS |
|---|---|
| Patent litigation blocks approval | Delays generic launch |
| Settlement with delayed entry | Establishes a negotiated launch date |
| Invalidity or non-infringement ruling | Accelerates generic entry |
| ANDA approval without launch | Creates latent competition but limited immediate revenue impact |
A Paragraph IV certification can trigger a 30-month stay of FDA approval when the NDA holder or patent owner files an infringement action within the statutory period.[4] The stay delays approval but does not guarantee a commercially durable barrier.
What is the Orange Book status of UCERIS?
UCERIS is subject to Orange Book analysis at the product level. The relevant questions are:
- Which patents remain listed against UCERIS tablets?
- Which patents remain listed against UCERIS foam?
- Are the patents active, expired, delisted, or under litigation?
- Has FDA approved any ANDA referencing the product?
- Are approved generics therapeutically equivalent and substitutable?
- Do product labels include carve-outs for protected methods of use?
Orange Book status is more important for the 9 mg tablet than for the foam because retail pharmacy substitution can rapidly redirect tablet volume. Foam substitution depends more heavily on product availability, payer policy, and prescriber preference.
How strong is the UCERIS patent estate?
The UCERIS patent estate is moderate rather than dominant.
Strengths
- Colon-targeted delivery provides formulation-specific differentiation.
- The oral tablet has an established FDA-approved route and clinical role.
- Manufacturing know-how may make exact replication more difficult.
- Rectal foam has a differentiated delivery profile relative to oral corticosteroids.
Weaknesses
- Budesonide is an old active ingredient.
- The market has a short-course treatment profile, limiting patient lock-in.
- Generic manufacturers can compete on price after approval.
- Method-of-use claims are narrower than composition claims.
- The drug competes with established generic prednisone and mesalamine.
- Payers have incentives to move patients to lower-cost alternatives.
The estate can delay competition, but it is unlikely to preserve premium pricing indefinitely once a therapeutically equivalent generic becomes available.
What is the UCERIS market size?
The relevant market is the U.S. mild-to-moderate ulcerative colitis induction market, not the entire inflammatory bowel disease market.
The United States has roughly 1 million or more people living with ulcerative colitis, although only a subset has active disease requiring corticosteroid induction in a given year.[5] UCERIS competes for patients who:
- Have active mild-to-moderate disease.
- Need escalation beyond mesalamine.
- Are not yet candidates for biologic or small-molecule therapy.
- Require a corticosteroid with lower systemic exposure than prednisone.
- Have distal disease suitable for rectal foam.
A reasonable annual U.S. treatment population for budesonide MMX and budesonide rectal foam is approximately 150,000 to 250,000 treatment courses. This estimate includes repeat treatment but excludes patients treated exclusively with systemic corticosteroids or advanced therapies.
What are UCERIS sales projections for 2025-2030?
Bausch Health does not consistently disclose UCERIS revenue as a stand-alone public line item. The following projections therefore represent a market model for combined U.S. oral budesonide MMX and rectal foam revenue, including branded and generic products.
Base-case U.S. sales projection
| Year | Estimated treatment courses | Average net revenue per course | Total market revenue |
|---|---|---|---|
| 2025 | 190,000 | $1,050 | $200 million |
| 2026 | 205,000 | $950 | $195 million |
| 2027 | 220,000 | $900 | $198 million |
| 2028 | 230,000 | $870 | $200 million |
| 2029 | 240,000 | $850 | $204 million |
| 2030 | 250,000 | $850 | $213 million |
The model assumes prescription growth of about 5% annually, offset by price erosion from generic competition. Growth in treatment volume reflects increasing use of colon-targeted corticosteroids and greater diagnosis of ulcerative colitis. Price pressure reflects payer substitution and additional generic entrants.
Scenario analysis
| Scenario | 2025 market revenue | 2030 market revenue | Main assumptions |
|---|---|---|---|
| Low | $120 million | $130 million | Rapid generic entry, aggressive payer substitution |
| Base | $200 million | $210 million | Gradual volume growth and moderate price erosion |
| High | $300 million | $340 million | Limited foam competition, stable brand access, higher treatment volume |
These estimates are market-level projections, not reported UCERIS brand sales. The branded product's revenue trajectory is materially weaker than the total market because generic products capture increasing prescription volume.
What revenue exposure does Bausch Health have?
UCERIS is part of Bausch Health's Salix gastrointestinal portfolio. Product-level exposure is limited by the absence of regular stand-alone revenue disclosure, but several commercial factors affect its value:
- Oral tablet revenue is vulnerable to pharmacy substitution.
- Rectal foam revenue may have a longer period of pricing resilience.
- Short treatment duration reduces annual revenue per patient.
- The brand can preserve value through payer contracting and physician familiarity.
- Generic availability can reduce net sales rapidly even if prescription volume grows.
For valuation purposes, UCERIS should be modeled as a declining branded asset with residual cash flow from the foam and from markets where generic penetration remains incomplete.
What formulations are protected by UCERIS patents?
Oral extended-release tablet
The tablet's differentiation is based on controlled release in the colon. Relevant technical barriers include:
- Multi-layer tablet construction.
- Polymer matrix design.
- Enteric or pH-dependent release.
- Uniform delivery of budesonide throughout the colon.
- Dissolution performance under gastrointestinal conditions.
- Bioequivalence to the reference product.
Rectal foam
The foam's technical protection may involve:
- Budesonide concentration.
- Foam stability.
- Propellant selection.
- Canister and actuator configuration.
- Rectal deposition.
- Dose uniformity.
- Storage and delivery performance.
Foam products can be more difficult to replicate than conventional tablets because the generic applicant must demonstrate pharmaceutical equivalence and appropriate performance of the delivery device.
How does UCERIS compare with competing drugs?
| Product | Main role | Commercial advantage | Main weakness |
|---|---|---|---|
| UCERIS oral tablet | Mild-to-moderate UC induction | Colon-targeted corticosteroid delivery | Short-course use and generic risk |
| UCERIS rectal foam | Distal UC induction | Local delivery with lower systemic exposure | Narrower eligible population |
| Mesalamine | First-line mild-to-moderate UC | Generic availability and maintenance use | Lower response in some patients |
| Prednisone | Moderate or severe flares | Very low cost and broad physician familiarity | Greater systemic adverse effects |
| Biologics | Moderate-to-severe disease | High efficacy and maintenance role | High cost and administration burden |
| JAK inhibitors | Moderate-to-severe disease | Oral administration and rapid activity | Safety restrictions and higher cost |
UCERIS is most exposed to mesalamine and prednisone in earlier treatment lines. It is less directly exposed to biologics and JAK inhibitors because those products target patients with more severe or refractory disease.
What generic launch risks exist for UCERIS?
The principal generic launch risks are:
- Multiple ANDA approvals arriving within a short period.
- Approval of products that are therapeutically equivalent to the tablets.
- Payer mandates favoring the lowest-cost generic.
- Pharmacy substitution without prescriber intervention.
- Generic foam entry that expands beyond the tablet market.
- Brand discounting that reduces net revenue without protecting volume.
Generic launch scenarios
One generic entrant
A single generic may initially price at a modest discount and allow the brand to retain some commercial volume. Brand net sales could fall 25% to 40% within the first year.
Several generic entrants
Multiple suppliers would likely produce faster price erosion. Brand volume could fall by 50% to 75%, with total market revenue declining as average net price contracts.
Delayed foam competition
If the foam remains less contested, the brand could retain a disproportionate share of value even after tablet erosion. This is the most favorable scenario for the incumbent.
What litigation and settlement issues affect UCERIS?
UCERIS litigation risk centers on ANDA patent cases, formulation validity, infringement, and settlement timing. The commercial questions are more important than the existence of a lawsuit alone:
- Does the litigation cover tablets, foam, or both?
- Is the patent enforceable through the expected generic approval date?
- Does the settlement permit an authorized generic?
- Is the entry date fixed or contingent on patent outcomes?
- Does the agreement include supply, licensing, or launch restrictions?
- Has the Federal Trade Commission reviewed the settlement?
A settlement that grants a generic an early launch date can convert a patent dispute into a predictable erosion curve. A settlement that includes an authorized generic can further reduce the incumbent's ability to preserve pricing.
How does UCERIS compare with other gastrointestinal patent estates?
UCERIS has a narrower and less durable patent position than newer gastrointestinal products protected by active ingredients, devices, or biologic manufacturing processes.
| Product type | Patent strength | Generic or biosimilar risk |
|---|---|---|
| Budesonide MMX | Moderate formulation protection | High after formulation patents weaken |
| Mesalamine delayed-release | Low to moderate formulation protection | High |
| Biologic antibody | High manufacturing and composition complexity | Biosimilar risk, but slower entry |
| JAK inhibitor | Strong active-ingredient protection | Delayed until core patents expire |
| Combination device product | Variable | Depends on device and drug claims |
UCERIS has greater near-term generic vulnerability than newer advanced therapies, but it remains differentiated from inexpensive systemic corticosteroids by its local delivery profile.
What is the geographic coverage of UCERIS?
The commercial opportunity is concentrated in the United States, where UCERIS has established FDA approval and reimbursement infrastructure. International opportunities depend on local approval, reimbursement, and licensing arrangements for budesonide MMX technology.
Geographic factors include:
- U.S. Orange Book and ANDA competition.
- European national and centralized regulatory pathways.
- Local recognition of MMX delivery technology.
- Reimbursement for mild-to-moderate ulcerative colitis.
- Availability of alternative budesonide formulations.
- Local licensing agreements and distribution rights.
The United States should remain the primary value driver because the product's clinical positioning, payer infrastructure, and generic substitution rules are most developed there.
What licensing deals affect UCERIS?
UCERIS was commercialized through specialty gastrointestinal businesses and technology arrangements associated with budesonide MMX delivery. The economic value of any licensing arrangement depends on territory, formulation, royalty rate, manufacturing rights, and generic-entry provisions.
Licensing diligence should focus on:
- Ownership of MMX-related patents.
- Royalty obligations after generic launch.
- Rights to tablets versus foam.
- Territory-specific commercialization rights.
- Supply obligations and minimum purchase commitments.
- Control of Orange Book listings and patent litigation.
Public disclosures do not provide a consistent, stand-alone view of current UCERIS royalty expense or product-level licensing economics.
Key Takeaways
- UCERIS is a mature budesonide product for induction of remission in mild-to-moderate ulcerative colitis.
- The oral 9 mg tablet is the principal generic-substitution risk.
- Rectal foam may retain stronger pricing because it has a narrower use case and more complex delivery system.
- Budesonide itself has no meaningful remaining composition-of-matter protection.
- Remaining value depends on formulation patents, manufacturing know-how, payer contracting, and generic timing.
- A reasonable base-case estimate places total U.S. UCERIS-related market revenue near $200 million annually through 2030.
- Branded revenue should decline faster than total market revenue.
- Biosimilar risk is not relevant because UCERIS is a small-molecule product.
- The most important diligence items are Orange Book listings, ANDA approvals, Paragraph IV litigation, settlement entry dates, and foam-generic availability.
FAQs
Is UCERIS still commercially relevant after generic budesonide entry?
Yes. UCERIS remains relevant because physicians use colon-targeted budesonide for patients who need corticosteroid induction but want to limit systemic exposure. Commercial value shifts toward generics as substitution increases.
Is budesonide MMX the same as ordinary budesonide?
No. Budesonide MMX is engineered for extended release in the colon. Other budesonide products, including inhaled, nebulized, and ileal-release formulations, are not automatically substitutable with UCERIS.
Can patients use UCERIS for long-term ulcerative colitis maintenance?
UCERIS is primarily an induction product. Long-term corticosteroid use is generally avoided because of systemic and adrenal risks. Maintenance treatment usually relies on mesalamine, immunomodulators, biologics, or small-molecule therapies.
Does UCERIS compete with Entocort?
Only indirectly. Entocort is an ileal- and right-colon-targeted budesonide product mainly associated with Crohn's disease, while UCERIS is designed for colonic delivery in ulcerative colitis. Their indications and release profiles differ.
What would most increase UCERIS market value?
The strongest positive drivers would be delayed foam generic entry, sustained reimbursement for locally acting corticosteroids, increased diagnosis of ulcerative colitis, and evidence supporting use after mesalamine failure but before biologic therapy.
References
- U.S. Food and Drug Administration. (2013). UCERIS (budesonide) extended-release tablets prescribing information.
- U.S. Food and Drug Administration. (2014). UCERIS (budesonide) rectal foam prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Congress. (1984). Drug Price Competition and Patent Term Restoration Act of 1984, 21 U.S.C. § 355(j).
- Crohn's & Colitis Foundation. (2024). The facts about inflammatory bowel disease.
- Bausch Health Companies Inc. (2024). Annual report on Form 10-K for the year ended December 31, 2023.
- American Gastroenterological Association. (2020). American Gastroenterological Association clinical practice guidelines on the management of mild-to-moderate ulcerative colitis. Gastroenterology, 158(5), 1450-1461.
More… ↓
