Share This Page
Drug Sales Trends for LOPERAMIDE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for LOPERAMIDE (2002)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
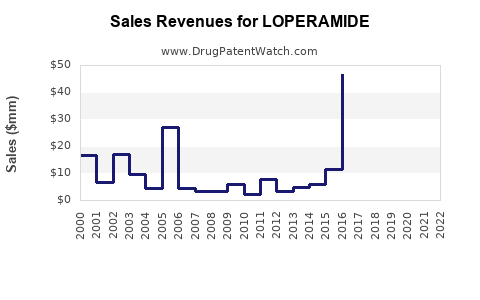
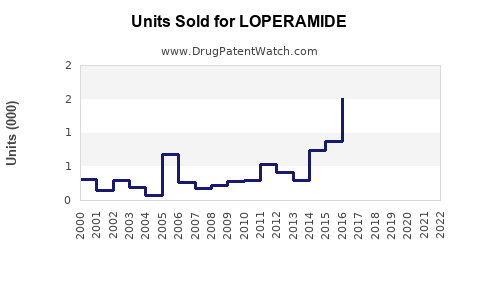
Annual Sales Revenues and Units Sold for LOPERAMIDE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| LOPERAMIDE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| LOPERAMIDE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| LOPERAMIDE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| LOPERAMIDE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Loperamide Market Analysis, Sales Projections, Patent Status, and Competitive Landscape
Loperamide is a mature, low-cost antidiarrheal with global retail sales likely in the range of $1.5 billion to $2.2 billion in 2024, based on an analyst model covering branded, generic, store-brand, and institutional products. The market is expected to grow at approximately 3% to 5% annually through 2030, reaching an estimated $1.8 billion to $2.9 billion.
The commercial opportunity is concentrated in over-the-counter products, especially Imodium and private-label loperamide. Patent protection is no longer a material barrier in the United States or major European markets. Growth depends on distribution, brand recognition, packaging compliance, emerging-market access, and retail execution rather than exclusivity.
| Metric | Assessment |
|---|---|
| Active ingredient | Loperamide hydrochloride |
| Primary use | Symptomatic treatment of acute diarrhea and chronic diarrhea |
| Main U.S. brands | Imodium A-D, store brands, generic loperamide |
| U.S. regulatory status | OTC and prescription products |
| Estimated 2024 global retail market | $1.5 billion-$2.2 billion |
| Estimated 2030 global retail market | $1.8 billion-$2.9 billion |
| Estimated 2024-2030 CAGR | 3%-5% |
| Patent position | Mature, largely expired composition and product estate |
| Biosimilar risk | None |
| Generic-entry risk | Already realized and structurally high |
| Main commercial threat | Low-price substitution and safety-related restrictions |
What is the current market size for loperamide?
The global loperamide market is driven by high-volume OTC purchases rather than premium prescription pricing. Public companies generally report loperamide within broader consumer-health categories, so standalone revenue is not consistently disclosed. Market-research estimates also vary because some reports count retail sales while others count manufacturer revenue, hospital products, or only branded products.
A practical 2024 market model is:
| Region | Estimated 2024 retail sales | Market characteristics |
|---|---|---|
| United States and Canada | $600 million-$850 million | Strong brand presence, high private-label penetration, mature OTC category |
| Western Europe | $350 million-$550 million | Pharmacy-led sales, country-specific reimbursement and OTC rules |
| Central and Eastern Europe | $100 million-$180 million | Generic-heavy, pharmacy distribution |
| Asia-Pacific | $300 million-$500 million | Population growth and wider OTC access offset lower per-unit pricing |
| Latin America | $100 million-$180 million | Retail pharmacy growth and variable regulatory controls |
| Middle East and Africa | $80 million-$150 million | Smaller base, fragmented distribution |
| Total | $1.5 billion-$2.2 billion | Includes branded, generic, and private-label products |
The United States is commercially important because loperamide is widely available in tablets, caplets, liquid, and chewable formats. The category has high household recognition, but price competition limits revenue expansion. The largest value pool is typically the branded and branded-generic segment, while unit volume is more evenly divided among national brands, pharmacy brands, and mass-retail private labels.
How are loperamide sales expected to grow through 2030?
The base-case forecast assumes low-single-digit growth in developed markets and mid-single-digit growth in selected emerging markets.
| Year | Low case | Base case | High case |
|---|---|---|---|
| 2024 | $1.5 billion | $1.85 billion | $2.2 billion |
| 2025 | $1.55 billion | $1.92 billion | $2.30 billion |
| 2026 | $1.60 billion | $2.00 billion | $2.40 billion |
| 2027 | $1.66 billion | $2.08 billion | $2.51 billion |
| 2028 | $1.71 billion | $2.18 billion | $2.63 billion |
| 2029 | $1.77 billion | $2.28 billion | $2.75 billion |
| 2030 | $1.83 billion | $2.39 billion | $2.88 billion |
| 2024-2030 CAGR | 3.3% | 4.3% | 4.5% |
The base case assumes:
- Developed-market volume growth of approximately 1% to 2%.
- Emerging-market volume growth of approximately 4% to 7%.
- Limited price increases because generic and private-label products constrain pricing.
- Continued demand for rapid symptom relief during travel, gastrointestinal infections, and chronic bowel disorders.
- Stable access through pharmacies, supermarkets, convenience retailers, and e-commerce.
The high case requires stronger growth in Asia-Pacific, Latin America, and online pharmacy channels. The low case reflects further substitution by bismuth subsalicylate, oral rehydration products, probiotics, and low-priced store brands.
Which companies sell loperamide products?
The competitive market includes branded consumer-health companies, generic manufacturers, pharmacy chains, supermarkets, and regional distributors.
| Company or channel | Product position | Commercial relevance |
|---|---|---|
| Kenvue | Imodium and related consumer-health products in markets where the brand is held by the company | Major branded OTC participant |
| Perrigo | Store-brand and contract-manufactured OTC products | Important private-label supplier |
| Haleon | Broader digestive-health portfolio, with country-specific antidiarrheal exposure | Competes for digestive-health shelf space |
| Teva, Viatris, Sandoz, Dr. Reddy's, and regional generic manufacturers | Generic prescription and OTC loperamide | Price competition and pharmacy supply |
| CVS, Walgreens, Walmart, Amazon, Boots, and supermarket chains | Private-label products | High-volume, low-price alternatives |
| Regional pharmaceutical companies | Country-specific loperamide brands | Important outside North America |
Brand ownership can vary by jurisdiction. Imodium has historically been associated with Johnson & Johnson consumer health operations, while Kenvue became the standalone consumer-health company following its separation from Johnson & Johnson. Local marketing rights, distribution arrangements, and product registrations can differ by country.[1]
What is the FDA regulatory status of loperamide?
Loperamide is available in the United States as an OTC antidiarrheal and as a prescription product. OTC products are marketed under the FDA antidiarrheal monograph framework, while prescription products are approved through individual applications.
The FDA recognizes loperamide hydrochloride as an active ingredient for controlling symptoms of diarrhea. The standard OTC indication is treatment of acute nonspecific diarrhea and chronic diarrhea associated with inflammatory bowel disease or other conditions, subject to labeling restrictions.[2]
The principal U.S. product forms include:
- 2 mg tablets and caplets.
- Chewable tablets.
- Oral solutions and liquids.
- Prescription capsules and oral solutions.
- Combination products in selected markets.
FDA safety communications have focused on serious cardiac events associated with excessive doses, including QT-interval prolongation, torsades de pointes, cardiac arrest, and death.[3] The safety issue is commercially relevant because it has driven package-size controls, warning language, pharmacist intervention, and restrictions on high-volume sales.
The FDA has also encouraged manufacturers and retailers to reduce the number of tablets available in single packages and to place loperamide products behind pharmacy counters in some settings. These measures constrain misuse without eliminating lawful OTC access.
What patents protect loperamide products?
No active U.S. composition-of-matter patent is a meaningful barrier to generic or private-label loperamide sales. The original loperamide patents date to the early development period of the molecule and have expired.
The current U.S. protection profile is characterized by:
| Protection category | Current commercial position |
|---|---|
| Composition of matter | Expired |
| Core synthesis patents | Expired |
| Basic oral dosage forms | Expired or no longer commercially restrictive |
| Original Imodium product protection | Expired |
| OTC monograph eligibility | Regulatory framework, not exclusivity |
| Brand trademarks | Still commercially important |
| Modern packaging or label claims | Potentially registrable, but narrow and weak against ordinary generic entry |
| Manufacturing know-how | May remain confidential but does not block API sourcing |
Trademark rights are more important than patent rights for the branded segment. A generic manufacturer can sell loperamide under its own name, but it cannot use the Imodium name, trade dress, or protected brand assets.
What formulations are protected by loperamide patents?
Loperamide tablets, capsules, liquids, and chewable products generally use conventional oral dosage technology. The core formulation concepts are old and widely available. Product differentiation is more likely to rely on:
- Flavor and chewability.
- Tablet size and dose convenience.
- Packaging designed for travel.
- Child-resistant or tamper-evident formats.
- Unit-dose blister packs.
- Combination products.
- Retail-specific packaging.
- Digital and pharmacy distribution.
A formulation patent could matter if it covered a genuinely distinct delivery system or stability profile. For standard immediate-release loperamide, the commercial value of such claims would likely be limited because competing products can use ordinary dosage forms.
Does loperamide have Orange Book exclusivity?
Loperamide does not have a current exclusivity position comparable to a recently approved prescription product. OTC monograph products are not protected through the same Orange Book patent-listing mechanism used for approved prescription drugs.
Prescription loperamide products may appear in FDA product databases, but the product category does not have a commercially significant active patent estate supporting delayed generic entry. Generic manufacturers have long been able to compete in the United States.
The key distinction is:
- OTC loperamide competes under the FDA monograph and private-label framework.
- Prescription loperamide competes through abbreviated and full approval pathways.
- Brand trademarks and distribution relationships, rather than Orange Book patents, determine most commercial share.
When does loperamide lose exclusivity?
Loperamide lost meaningful regulatory and patent exclusivity decades ago. The original molecule and basic oral products are now mature generic products.
The commercial exclusivity timeline is:
| Period | Event |
|---|---|
| Late 1960s | Loperamide developed and patented |
| 1970s | Prescription products introduced in several markets |
| 1980s | OTC access expanded, including U.S. OTC transition |
| 1990s onward | Generic and private-label competition expanded |
| 2010s | Safety controls intensified because of high-dose misuse |
| Current market | No meaningful molecule-level exclusivity; brand and channel strength remain |
The absence of patent exclusivity does not mean every product can be copied immediately in every country. Local registration requirements, manufacturing standards, pharmacovigilance obligations, and supply-chain qualification can delay entry. Those barriers are operational, not patent-based.
Are there Paragraph IV challenges or loperamide patent lawsuits?
Paragraph IV litigation is not a material current risk for standard loperamide products because the relevant core patents have expired and the market is already genericized. A new branded formulation could create Paragraph IV exposure if it relied on later-expiring patents, but ordinary loperamide tablets and capsules do not depend on such protection.
The most relevant legal risks are:
- Trademark infringement involving unauthorized use of Imodium branding.
- Product-liability litigation involving overdose or cardiac events.
- False advertising claims concerning speed, duration, or safety.
- Regulatory enforcement involving excessive-dose sales or misleading labeling.
- Supply and quality disputes involving API or finished-dose manufacturers.
The litigation profile is therefore different from that of a patented prescription drug. Market participants face compliance and product-liability exposure rather than a central patent cliff.
Is there biosimilar risk for loperamide?
There is no biosimilar risk. Loperamide is a small-molecule drug, not a biologic. Its competitive risk comes from conventional generic drugs, OTC private-label products, and non-loperamide alternatives.
Generic substitution is structurally strong because:
- The active ingredient is well established.
- The dosage forms are technically simple.
- Manufacturing capability is widely available.
- Prescribers and pharmacists have extensive familiarity with the product.
- Consumers often select on price and convenience.
- Retailers can switch suppliers with limited consumer disruption.
How does loperamide compare with competing antidiarrheal products?
| Product category | Competitive advantage | Limitation |
|---|---|---|
| Loperamide | Rapid symptomatic control and broad availability | Does not treat the underlying infection; misuse risk |
| Bismuth subsalicylate | Antidiarrheal and broader gastrointestinal symptom relief | Salicylate warnings, taste, contraindications |
| Diphenoxylate-atropine | Prescription option for selected chronic cases | Prescription controls and adverse-effect burden |
| Racecadotril | Used in selected international markets | Limited U.S. presence |
| Oral rehydration solutions | Treat dehydration and support recovery | Do not directly stop diarrhea |
| Probiotics | Consumer acceptance and preventive positioning | Variable evidence and slower perceived effect |
| Fiber and bulk-forming products | Useful in selected chronic bowel disorders | Not a rapid acute-diarrhea product |
Loperamide remains strongest where consumers prioritize immediate symptom control, portability, and low cost. Oral rehydration products are complementary rather than direct substitutes in dehydration-risk cases.
What manufacturing and intellectual-property barriers affect loperamide?
Manufacturing barriers are modest but not zero. The API is a mature compound with multiple global sources. Finished-product manufacturers must meet current good manufacturing practice requirements, validate content uniformity, control impurities, and maintain compliant packaging.
The main barriers include:
- API qualification and supplier reliability.
- FDA, European Union, and local manufacturing compliance.
- Stability data for tablets, liquids, and chewable formulations.
- Child-resistant and tamper-evident packaging.
- Pharmacovigilance systems.
- Retailer qualification and shelf-space access.
- Liability insurance and product-recall capacity.
No single manufacturing patent is likely to prevent competition in conventional dosage forms. Confidential process know-how may improve yield or reduce cost, but it generally creates a margin advantage rather than legal exclusivity.
What licensing deals affect loperamide sales?
Loperamide licensing is primarily commercial rather than technology-driven. Relevant arrangements may include:
- Brand licensing for Imodium in specific territories.
- Contract manufacturing for private-label retailers.
- Regional distribution agreements.
- OTC registration transfers.
- Co-branding with pharmacy chains.
- Supply agreements for loperamide API and finished products.
The commercial value of a licensing deal depends on territory, trademark rights, regulatory ownership, minimum purchase obligations, and channel access. A generic supply contract can generate meaningful volume but usually has limited pricing power because retailers can qualify alternative suppliers.
What generic launch scenarios exist for loperamide?
Because generic competition is already established, future launches will mainly be incremental rather than disruptive.
Base scenario
New suppliers compete on API cost, private-label contracts, and retail distribution. Market share shifts between manufacturers without materially expanding the total market.
Upside scenario
A manufacturer wins a national pharmacy or mass-retail contract, introduces convenient chewable or travel formats, and captures share from branded Imodium. Revenue growth comes from volume and distribution, not premium pricing.
Downside scenario
Retailers reduce shelf space because of safety concerns, package restrictions, or stronger consumer preference for bismuth and probiotic products. The market remains stable in units but declines in value.
What is the revenue exposure for major companies?
Loperamide revenue is strategically important to consumer-health portfolios but usually not large enough to drive the financial results of a diversified multinational company on its own.
Revenue exposure is highest for:
- Branded OTC companies with Imodium-centered digestive-health portfolios.
- Private-label manufacturers with large retailer contracts.
- Regional companies whose digestive-health business is concentrated in loperamide.
- API suppliers with limited product diversification.
Revenue exposure is lower for diversified generic companies because loperamide is typically one product among many. Margin pressure is likely to be greater than volume pressure. A supplier can maintain units while losing revenue through retailer tendering and private-label price reductions.
Key Takeaways
- Loperamide is a mature OTC and prescription antidiarrheal with an estimated 2024 global retail market of $1.5 billion to $2.2 billion.
- A reasonable base-case forecast reaches approximately $2.4 billion by 2030.
- Patent exclusivity has expired, and no current U.S. patent estate materially restricts ordinary generic or private-label competition.
- The FDA OTC monograph and product-safety controls are more important than Orange Book patents.
- Imodium retains brand value, but store brands and generic products limit pricing power.
- No biosimilar risk exists because loperamide is a small-molecule drug.
- Growth is likely to come from emerging markets, e-commerce, travel use, convenience formats, and pharmacy distribution.
- The principal risks are high-dose misuse, cardiac safety concerns, package restrictions, product liability, and retailer-driven price compression.
- Manufacturing technology is widely available; regulatory compliance and distribution access are the main barriers.
- Loperamide is better viewed as a cash-generating mature consumer-health category than as a patent-protected pharmaceutical growth asset.
FAQs
Is loperamide still profitable for generic manufacturers?
Yes. Profitability depends on manufacturing cost, retailer contracts, API sourcing, and scale. Unit margins are generally modest because multiple suppliers compete for pharmacy and private-label business.
Does Imodium have a patent advantage over generic loperamide?
No meaningful molecule-level patent advantage remains. Imodium competes through brand recognition, packaging, consumer trust, and retail placement.
Can loperamide sales grow despite generic competition?
Yes. Category growth can continue through population growth, expanded OTC access, emerging-market distribution, and online retail. Generic competition limits price expansion but does not eliminate volume growth.
Is loperamide approved for children?
Age limits and dosing instructions vary by product and jurisdiction. U.S. OTC labeling places restrictions on pediatric use, and caregivers are instructed to follow product labeling and medical guidance.[2]
What is the largest threat to the loperamide market?
The largest structural threat is not patent expiry, which has already occurred. It is a combination of safety-related sales restrictions, high-dose misuse concerns, retailer price compression, and substitution by bismuth subsalicylate, oral rehydration products, and probiotics.
References
-
Kenvue Inc. (2024). Annual report for the fiscal year ended December 31, 2023. Kenvue Inc.
-
U.S. Food and Drug Administration. (2023). Loperamide hydrochloride drug products and over-the-counter antidiarrheal labeling. FDA.
-
U.S. Food and Drug Administration. (2018). FDA warns about serious heart problems with high doses of the antidiarrheal medicine loperamide, including from abuse and misuse. FDA.
-
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (2024). Drug facts label requirements for over-the-counter antidiarrheal products. FDA.
More… ↓
