Share This Page
Drug Sales Trends for fosinopril
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for fosinopril (2001)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
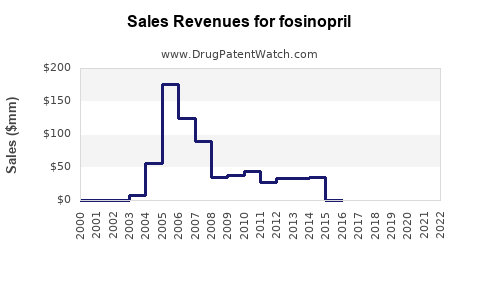
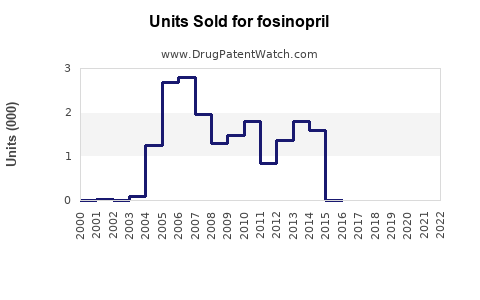
Annual Sales Revenues and Units Sold for fosinopril
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| FOSINOPRIL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| FOSINOPRIL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| FOSINOPRIL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| FOSINOPRIL | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| FOSINOPRIL | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| FOSINOPRIL | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| FOSINOPRIL | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Fosinopril Market Analysis, Patent Status, Competitive Landscape and Sales Projections
Fosinopril is a mature, low-cost generic ACE inhibitor with limited commercial growth potential. Its U.S. branded product, Monopril, lost meaningful exclusivity years ago, and multiple generic suppliers compete primarily on price, supply reliability and formulary access. Public companies do not separately report fosinopril revenue, so drug-level sales projections require a unit-and-price model rather than a historical revenue series.
The base-case outlook is stable to modestly declining prescription volume, with nominal revenue supported only by price changes or temporary supply constraints. Fosinopril is unlikely to attract significant branded investment, biosimilar competition or major licensing activity.
What is fosinopril and where is it used?
Fosinopril sodium is an orally administered ACE inhibitor used to treat hypertension and, in some markets, heart failure. It is a prodrug converted to fosinoprilat, the active ACE-inhibiting metabolite. The drug is available primarily as immediate-release tablets in strengths including 10 mg, 20 mg and 40 mg. Some markets also have fosinopril combined with hydrochlorothiazide.
The U.S. label identifies fosinopril for treatment of hypertension and as adjunctive therapy in heart failure. Like other ACE inhibitors, it carries warnings related to fetal toxicity, angioedema, hyperkalemia, renal impairment and hypotension (U.S. Food and Drug Administration [FDA], 2019).
Fosinopril product profile
| Attribute | Fosinopril |
|---|---|
| Active ingredient | Fosinopril sodium |
| Drug class | Angiotensin-converting enzyme inhibitor |
| Main indications | Hypertension; heart failure |
| Original brand | Monopril |
| Original innovator | Bristol-Myers Squibb |
| Route | Oral |
| Primary dosage form | Immediate-release tablet |
| Common strengths | 10 mg, 20 mg, 40 mg |
| Combination product | Fosinopril/hydrochlorothiazide |
| Regulatory status | Generic, prescription drug |
| Biosimilar relevance | None; fosinopril is a small molecule |
| Commercial maturity | Mature and largely commoditized |
How large is the fosinopril market?
No widely reported public source provides a current, standalone global revenue figure for fosinopril. Generic manufacturers generally aggregate fosinopril sales within broader portfolios, and U.S. public filings do not normally disclose product-level revenue for this drug.
The relevant market is divided into:
- U.S. retail and mail-order prescriptions.
- European and other regulated generic markets.
- Hospital and government tenders.
- Combination-product sales involving hydrochlorothiazide.
- Lower-price markets where ACE inhibitors remain common first-line therapies.
Fosinopril is a small product within the broader ACE inhibitor market. Lisinopril, enalapril, ramipril and perindopril have stronger prescribing visibility in many markets. Fosinopril retains clinical differentiation through hepatic and renal elimination pathways, but that feature has not produced a durable commercial premium.
Market position versus competing ACE inhibitors
| Drug | Commercial position | Main advantage | Main limitation |
|---|---|---|---|
| Lisinopril | Category leader in many markets | Low cost, extensive physician familiarity | Renal elimination; cough and angioedema risk |
| Enalapril | Large established generic market | Broad historical use and low price | Mature competition |
| Ramipril | Strong cardiovascular positioning | Extensive outcomes evidence in some settings | Higher cost in some markets |
| Perindopril | Strong in selected international markets | Established hypertension use | Regional availability varies |
| Fosinopril | Niche mature generic | Dual hepatic and renal elimination | Lower prescribing momentum and limited differentiation |
Fosinopril competes against substitutes more than against other fosinopril manufacturers. Physicians can switch patients to another ACE inhibitor or to an angiotensin receptor blocker, while pharmacies can switch among generic suppliers when contracts permit.
When did fosinopril lose exclusivity?
Fosinopril’s original U.S. market exclusivity has expired. Generic fosinopril products have been available for many years, and the product no longer has the commercial profile of a protected branded medicine.
The original Monopril franchise was developed by Bristol-Myers Squibb. FDA records identify fosinopril sodium tablets as an established generic product, while the current commercial market is supplied by generic manufacturers rather than by an actively promoted innovator brand (FDA, n.d.-a; FDA, n.d.-b).
Fosinopril exclusivity timeline
| Event | Timing | Commercial effect |
|---|---|---|
| Original U.S. approval of Monopril | Early 1990s | Created branded market |
| Brand patent and regulatory exclusivity period | Expired | Removed exclusive pricing |
| Generic approvals | Early 2000s and later | Expanded supplier base |
| Current period | Generic market | Price-led competition |
| Near-term outlook | No new exclusivity expected | Limited opportunity for premium pricing |
What patents protect fosinopril today?
No material active patent barrier is expected to prevent generic supply of standard fosinopril tablets in the United States. The original compound, formulation and core use protections are no longer commercially relevant to market entry.
The FDA Orange Book is the principal U.S. source for listed patents and regulatory exclusivity associated with approved drug products. For a mature generic such as fosinopril, the practical entry analysis focuses on manufacturing approvals, ANDA status, supplier qualification and commercial contracting rather than patent clearance (FDA, n.d.-c).
Are formulation patents a barrier for fosinopril?
Formulation patents do not appear to create a meaningful barrier for conventional immediate-release fosinopril tablets. Manufacturers can produce standard tablet products using established excipient systems and conventional solid-dose manufacturing processes.
Potentially protectable technical areas could include:
- Modified-release delivery systems.
- Specialized fixed-dose combinations.
- Taste-masked or dispersible formulations.
- Stability improvements.
- Novel salts or polymorphs.
- Combination products with other cardiovascular agents.
These areas have limited commercial value unless they address a clear adherence, tolerability or dosing problem. Fosinopril’s low price makes it difficult to support substantial development costs for a new delivery system.
What is the Orange Book status of fosinopril?
Fosinopril is an approved small-molecule prescription drug with generic listings. Its commercial status is consistent with an off-patent product marketed through abbreviated new drug applications.
The Orange Book analysis should distinguish:
- Fosinopril sodium tablets.
- Fosinopril and hydrochlorothiazide combination tablets.
- Brand and generic National Drug Codes.
- Approved strengths and manufacturers.
- Any product-specific patent listings that may appear for a particular formulation.
A generic manufacturer’s approval does not guarantee continuous supply. Product availability can change because of manufacturing economics, raw-material supply, quality actions or manufacturer discontinuation.
Are there Paragraph IV challenges involving fosinopril?
Paragraph IV litigation is not a significant current market issue for standard fosinopril. Paragraph IV certifications are primarily relevant when an ANDA applicant challenges an unexpired listed patent. Fosinopril’s central product and use protections have expired, reducing the incentive for major patent litigation.
The more relevant regulatory risks are:
- ANDA review delays.
- Manufacturing deficiencies.
- Drug shortages.
- Facility inspections.
- Product recalls.
- Labeling or stability issues.
- Withdrawal of low-volume presentations.
Fosinopril does not present the litigation profile associated with newer branded drugs facing first-wave generic entry.
Which companies compete in the fosinopril market?
Fosinopril has been marketed by multiple generic companies over time, including manufacturers operating in the U.S. and international markets. The active supplier list can change as companies discontinue low-volume products or transfer approvals.
Competition is based on:
- Wholesale acquisition cost.
- Medicaid and managed-care rebate positioning.
- Pharmacy benefit manager contracts.
- Supply continuity.
- Manufacturing scale.
- Approved strengths.
- Authorized trading partners.
- Ability to support hospital tenders.
The market is structurally fragmented, but product-level concentration can rise if several suppliers exit. That can create temporary pricing power for remaining suppliers without restoring durable brand economics.
Generic manufacturer economics
Fosinopril’s manufacturing economics are constrained by its low price and mature demand. The most viable suppliers are manufacturers with:
- Existing ACE inhibitor production lines.
- Low-cost active pharmaceutical ingredient access.
- Broad cardiovascular portfolios.
- Established U.S. or European regulatory infrastructure.
- The ability to manufacture multiple tablet strengths on the same platform.
A company focused only on fosinopril would face a weaker investment case than a company selling fosinopril alongside lisinopril, enalapril, losartan, hydrochlorothiazide and other cardiovascular products.
What are the sales projections for fosinopril?
Because public drug-level sales data are unavailable, the following projections are scenario estimates rather than reported market figures. The model uses 30-day-equivalent prescriptions and blended net revenue per 30-day equivalent.
U.S. fosinopril revenue scenarios
| Scenario | Annual 30-day equivalents | Net revenue per 30-day equivalent | Estimated annual market revenue |
|---|---|---|---|
| Low case | 0.8 million | $4 | $3.2 million |
| Base case | 1.5 million | $6 | $9.0 million |
| High case | 2.5 million | $8 | $20.0 million |
These figures represent an analytical range for the U.S. product market, not audited sales. Gross pharmacy transaction values can be higher than manufacturer net revenue because rebates, discounts, wholesaler spreads and payer concessions reduce realized manufacturer pricing.
Five-year base-case projection
Assuming annual prescription volume declines by 3%, while net price increases by 1% annually, the modeled U.S. market develops as follows:
| Year | 30-day equivalents | Net revenue per 30-day equivalent | Estimated revenue |
|---|---|---|---|
| Year 1 | 1.50 million | $6.00 | $9.00 million |
| Year 2 | 1.46 million | $6.06 | $8.84 million |
| Year 3 | 1.41 million | $6.12 | $8.68 million |
| Year 4 | 1.37 million | $6.18 | $8.53 million |
| Year 5 | 1.33 million | $6.24 | $8.39 million |
Under this model, the market contracts at approximately 1.4% annually in nominal revenue. The decline reflects volume erosion that exceeds modest price inflation.
Alternative projection cases
| Case | Volume trend | Price trend | Five-year commercial result |
|---|---|---|---|
| Downside | -7% annually | -2% annually | Sharp revenue erosion; supplier exits likely |
| Base | -3% annually | +1% annually | Gradual decline |
| Upside | +1% annually | +2% annually | Low-single-digit nominal growth |
The upside case would require a specific demand catalyst, such as a shortage of competing ACE inhibitors, formulary preference, expanded use in a regional market or a supplier disruption affecting substitutes. There is no clear evidence of a durable catalyst in the mature U.S. market.
What drives fosinopril revenue exposure?
Fosinopril revenue is more sensitive to prescription volume and supplier participation than to clinical innovation.
Key revenue drivers
- Generic prescription volume.
- Number of approved and active suppliers.
- Availability of all major tablet strengths.
- Payer reimbursement.
- Pharmacy substitution policies.
- ACE inhibitor prescribing trends.
- Cardiovascular disease prevalence.
- Hospital and government procurement.
- Competitor shortages.
- Raw-material and manufacturing costs.
Main commercial risks
| Risk | Likely effect |
|---|---|
| Continued substitution to lisinopril or ARBs | Lower volume |
| Supplier exits | Short-term supply instability |
| Price compression | Lower manufacturer revenue |
| Manufacturing observations | Product interruption or recall |
| Declining ACE inhibitor use in favor of ARBs | Structural volume pressure |
| Low prescription density | Reduced manufacturing incentive |
| New fixed-dose alternatives | Loss of niche demand |
Fosinopril’s renal and hepatic elimination profile may support use in selected patients, but it has not created a large premium segment. Prescribing decisions remain dominated by physician familiarity, guideline positioning, price and formulary coverage.
What generic launch scenarios exist for fosinopril?
A new generic entrant would not face a classic patent cliff. The commercial pathway is instead a share-capture exercise in an established market.
Scenario 1: Price-led entry
A new supplier launches at a discount to existing generic prices. This may capture wholesalers or secondary pharmacy contracts but usually compresses the entire market.
Scenario 2: Supply-reliability entry
A supplier positions around consistent availability of all strengths, with regulatory-grade manufacturing and reliable wholesaler fulfillment. This is more defensible than price alone.
Scenario 3: Portfolio bundling
A manufacturer includes fosinopril in a wider cardiovascular tender offering. This approach can improve purchasing leverage and reduce standalone product costs.
Scenario 4: Combination-product expansion
A supplier adds fosinopril/hydrochlorothiazide or another differentiated combination. The opportunity remains limited because combination products also face generic substitution and competing antihypertensive regimens.
What manufacturing and intellectual-property barriers remain?
The intellectual-property barrier is low. Manufacturing and regulatory execution are more important.
Key barriers include:
- Active pharmaceutical ingredient qualification.
- Impurity and degradation control.
- Batch-to-batch content uniformity.
- Stability across labeled shelf life.
- Bioequivalence demonstration.
- FDA current good manufacturing practice compliance.
- Reliable tablet-strength production.
- Packaging and serialization requirements.
- Pharmacovigilance and complaint handling.
Fosinopril is not technically among the most complex generic products. The main barrier is economic: maintaining a compliant supply chain for a low-revenue medicine.
How does fosinopril compare with newer cardiovascular opportunities?
Fosinopril has a lower risk profile than protected cardiovascular drugs because patent litigation and clinical development costs are minimal. It also has a much lower return potential.
| Investment category | Fosinopril | Protected cardiovascular drug |
|---|---|---|
| Patent risk | Low | High |
| Regulatory development cost | Low for approved generic | High |
| Pricing power | Very low | Potentially substantial |
| Market growth | Flat to declining | Depends on indication |
| Manufacturing complexity | Moderate-low | Variable |
| Litigation exposure | Low | Potentially high |
| Licensing value | Limited | Can be significant |
| Revenue visibility | Low at product level | Higher if branded sales reported |
For generic manufacturers, fosinopril is best viewed as a portfolio-completion product. For investors, it is unlikely to be material unless the company has unusually high exposure to the product or benefits from a temporary shortage.
What is the litigation and settlement outlook?
There is no evident current litigation structure comparable to a branded product approaching generic entry. Settlement agreements involving first-filer exclusivity, authorized generics or delayed entry are unlikely to be central to fosinopril’s current economics because the underlying market is already genericized.
The principal legal and compliance exposures are more likely to involve:
- Manufacturing quality.
- Product liability.
- Supply contracts.
- Antitrust issues involving generic pricing.
- Distributor and pharmacy disputes.
- Product recalls.
Key Takeaways
- Fosinopril is a mature, off-patent ACE inhibitor with limited pricing power.
- Monopril’s original branded exclusivity has expired, and generic competition is established.
- No material current patent barrier is expected for standard fosinopril tablets.
- Paragraph IV litigation and biosimilar risk are not significant commercial factors.
- Public companies do not generally disclose standalone fosinopril revenue.
- A modeled U.S. market range of approximately $3 million to $20 million annually illustrates the likely low-value profile, but these are analytical scenarios rather than reported sales.
- The base case is gradual market decline, driven by substitution, price compression and low prescription growth.
- Supplier reliability, manufacturing compliance and portfolio bundling matter more than patent strategy.
- Commercial upside would most likely come from a competitor shortage or broader portfolio contracting, not from clinical differentiation.
FAQs
Is fosinopril still sold in the United States?
Yes. Fosinopril sodium tablets remain an approved generic prescription product, although availability can vary by manufacturer, strength and distributor.
Is fosinopril more profitable than lisinopril?
Usually not. Lisinopril generally has greater prescription volume and stronger market recognition. Fosinopril may provide portfolio value, but its lower volume and generic pricing limit standalone profitability.
Does fosinopril have pediatric exclusivity?
No commercially relevant current pediatric exclusivity is associated with the mature generic fosinopril market.
Can fosinopril be repurposed for a new cardiovascular indication?
A new indication could theoretically be pursued, but the commercial case would require clinical evidence, regulatory investment and a defensible method-of-use position. The low generic price would make recovery of those costs difficult.
Is fosinopril included in hypertension treatment guidelines?
ACE inhibitors remain an established antihypertensive class, but guideline treatment choices vary by patient characteristics, comorbidities, region and prescriber preference. Fosinopril is generally considered within the broader ACE inhibitor class rather than as a leading guideline-driven product.
References
-
U.S. Food and Drug Administration. (2019). Fosinopril sodium prescribing information. FDA.
-
U.S. Food and Drug Administration. (n.d.-a). Drugs@FDA: Fosinopril sodium. FDA.
-
U.S. Food and Drug Administration. (n.d.-b). Approved drug products with therapeutic equivalence evaluations. FDA.
-
U.S. Food and Drug Administration. (n.d.-c). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
-
Whelton, P. K., Carey, R. M., Aronow, W. S., et al. (2018). 2017 ACC/AHA guideline for the prevention, detection, evaluation, and management of high blood pressure in adults. Hypertension, 71(6), e13-e115.
-
Williams, B., Mancia, G., Spiering, W., et al. (2018). 2018 ESC/ESH guidelines for the management of arterial hypertension. European Heart Journal, 39(33), 3021-3104.
More… ↓
