Share This Page
Drug Sales Trends for COMPRO
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for COMPRO (2001)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
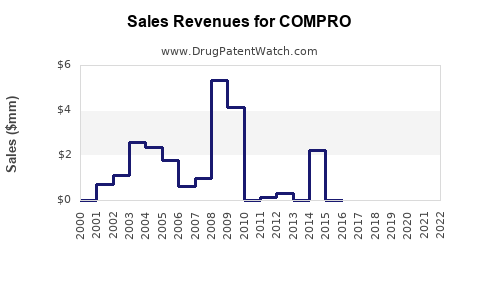
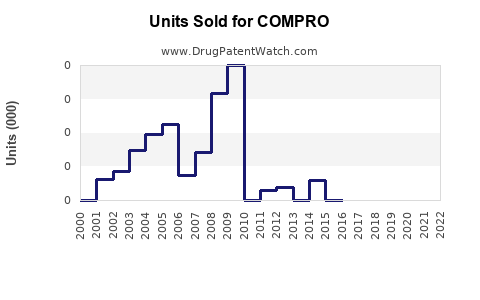
Annual Sales Revenues and Units Sold for COMPRO
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| COMPRO | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| COMPRO | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| COMPRO | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
COMPRO Market Analysis, Sales Forecast, Patent Position, and Generic Risk
COMPRO is a U.S. prescription rectal suppository containing prochlorperazine, generally supplied as a 25 mg dosage form for severe nausea and vomiting. Its commercial market is small, mature, and largely genericized. Public filings do not disclose standalone COMPRO revenue, unit volume, or net pricing. A reasonable U.S. net-sales estimate is approximately $5 million to $12 million annually, with a base-case forecast of roughly $9 million by 2029 under stable supply and limited price erosion.
What is COMPRO and what market does it serve?
COMPRO is a rectal formulation of prochlorperazine, a phenothiazine antiemetic and dopamine antagonist. The product is used primarily when oral administration is impractical because of vomiting, impaired consciousness, or acute gastrointestinal illness.
| Attribute | COMPRO profile |
|---|---|
| Active ingredient | Prochlorperazine |
| Dosage form | Rectal suppository |
| Common strength | 25 mg |
| Route | Rectal |
| Therapeutic class | Antiemetic; phenothiazine |
| Primary use | Severe nausea and vomiting |
| U.S. regulatory pathway | Prescription drug |
| Market structure | Mature, low-volume generic market |
| Principal alternatives | Prochlorperazine tablets and injection, promethazine suppositories, ondansetron, metoclopramide |
| Commercial position | Niche dosage form with limited direct competition |
The rectal route gives COMPRO a specific clinical role, but the same characteristic limits its addressable market. Most patients with nausea can receive oral, orally disintegrating, injectable, or intravenous therapy. Rectal delivery is most useful in acute-care situations where oral treatment is unsuitable.
The FDA-approved labeling identifies prochlorperazine suppositories for control of severe nausea and vomiting in adults. The product carries phenothiazine-class safety restrictions, including risks associated with extrapyramidal reactions, tardive dyskinesia, neuroleptic malignant syndrome, hypotension, and sedation (DailyMed, n.d.).
What is the current market size for COMPRO?
No public source reports COMPRO as a separate revenue line. The product is not a major contributor to the global antiemetic market, and standard market-research reports generally group it with prochlorperazine or broader antiemetic categories.
A bottom-up estimate places annual U.S. net sales in the following range:
| Scenario | Estimated annual U.S. net sales | Commercial interpretation |
|---|---|---|
| Low | $2 million-$5 million | Limited availability, weak reimbursement, substitution by other antiemetics |
| Base | $5 million-$12 million | Stable hospital and outpatient demand |
| High | $12 million-$20 million | Supply continuity, price realization, and limited alternatives |
These figures are modeled estimates rather than reported sales. The market is likely driven by institutional purchasing, wholesalers, emergency departments, hospital formularies, and a small outpatient segment.
The product’s value is concentrated in availability. A suppository can retain demand even when its clinical volume is low because hospitals and pharmacies may maintain it as an alternative dosage form for patients who cannot tolerate oral medication.
What are the COMPRO sales projections through 2029?
The base case assumes stable U.S. availability, no major label expansion, moderate pricing pressure, and continued substitution by lower-cost or more convenient antiemetic products.
| Fiscal year | Low case | Base case | High case |
|---|---|---|---|
| 2025E | $3.0 million | $7.0 million | $12.0 million |
| 2026E | $2.8 million | $7.4 million | $12.6 million |
| 2027E | $2.7 million | $7.8 million | $13.2 million |
| 2028E | $2.6 million | $8.3 million | $13.9 million |
| 2029E | $2.5 million | $8.8 million | $14.6 million |
| Implied CAGR | -4.5% | 5.9% | 5.0% |
The base case reflects a small increase in nominal sales from price adjustments and stable demand, not meaningful volume growth. Real unit demand is likely flat or declining.
What assumptions drive the forecast?
The projection uses five commercial assumptions:
- COMPRO remains available in the U.S. throughout the forecast period.
- The product retains a limited institutional and outpatient customer base.
- Average net pricing rises by approximately 2% to 4% annually.
- Unit volume declines slightly as ondansetron, promethazine, and injectable products capture treatment demand.
- No new competitor materially disrupts the rectal prochlorperazine market.
A supply interruption would have a disproportionate effect because the market is small and pharmacy inventories may be limited. Conversely, a shortage of competing antiemetics could produce temporary revenue spikes without changing the long-term market position.
What is the competitive landscape for COMPRO?
COMPRO competes against products that are usually more convenient, more familiar to prescribers, or easier to administer.
| Competitor | Dosage forms | Competitive advantage over COMPRO |
|---|---|---|
| Generic prochlorperazine | Tablet, oral solution, injection | Same active ingredient and broader administration options |
| Promethazine | Tablet, liquid, suppository, injection | Established antiemetic use and direct rectal alternative |
| Ondansetron | Tablet, ODT, oral solution, injection | Broad use, favorable tolerability, convenient ODT form |
| Metoclopramide | Tablet, liquid, injection | Established use in nausea and gastrointestinal motility disorders |
| Dimenhydrinate and related agents | Oral and injectable forms | Over-the-counter or low-cost access in some settings |
Ondansetron is the principal commercial substitute in many acute-care settings, although it does not provide a rectal dosage form. Promethazine suppositories are the closest direct route competitor. Prochlorperazine tablets and injection also reduce the need for COMPRO when those routes are clinically acceptable.
The product’s defensibility is therefore based on dosage-form availability and clinical utility, not on a differentiated molecule or broad therapeutic superiority.
What is the FDA regulatory status of COMPRO?
COMPRO is an FDA-regulated prescription product. Prochlorperazine is an established active ingredient with decades of clinical use. The product does not appear to depend on a recent New Drug Application exclusivity period or a novel active-ingredient protection strategy.
The regulatory risks are operational rather than developmental:
- Maintaining an approved manufacturing process.
- Meeting current good manufacturing practice requirements.
- Preserving supply of suppository materials and packaging.
- Maintaining stability data and quality controls.
- Managing labeling requirements for phenothiazine-related safety risks.
- Avoiding manufacturing interruptions that could trigger product unavailability.
The FDA Orange Book should be reviewed for the current reference-listed-drug designation, therapeutic-equivalence listings, and any active patent or exclusivity entries. For an old prochlorperazine suppository, the practical expectation is that market protection is limited and that any commercial advantage comes from supply reliability, customer contracts, and manufacturing capability rather than regulatory exclusivity (FDA, n.d.-a).
What patents protect COMPRO and when does exclusivity expire?
The original composition-of-matter protection for prochlorperazine has long expired. No commercially meaningful active-ingredient exclusivity should be assumed for COMPRO.
Potential intellectual-property categories include:
- Historical patents covering prochlorperazine or its salts.
- Formulation patents covering suppository excipients or manufacturing processes.
- Manufacturing know-how involving molding, uniformity, stability, and packaging.
- Trademark rights in the COMPRO brand.
- Regulatory records associated with the approved product.
The remaining commercial protection is likely weak relative to a new chemical entity. A formulation patent could create a narrower barrier, but a competitor could potentially design around it by using different excipients, manufacturing conditions, or packaging. Brand rights prevent confusingly similar branding but do not block generic prochlorperazine products.
Are there Paragraph IV challenges to COMPRO?
A current, commercially material Paragraph IV challenge is not apparent from the public profile of this mature product. Paragraph IV litigation is more relevant when an active Orange Book patent blocks an abbreviated new drug application. For COMPRO, the more likely competitive path is an ANDA supported by established prochlorperazine labeling and pharmaceutical equivalence requirements.
A generic entrant could still create litigation if an active formulation or process patent were listed. That risk cannot be quantified from product labeling alone. The absence of a prominent, active patent dispute supports the view that the main threats are price competition and substitution rather than patent litigation.
What generic entry risks exist for COMPRO?
Generic entry risk is structurally high because:
- The active ingredient is old and well characterized.
- The dosage form is established.
- Clinical development requirements are limited compared with a new drug.
- Prescribers can substitute among prochlorperazine products.
- FDA approval does not require proving superior clinical efficacy.
- The market has few barriers based on molecule ownership.
However, the market may not attract numerous entrants. Rectal suppositories require specialized manufacturing, relatively small production runs, stability controls, and reliable distribution. Expected revenue may be too low to justify development for some manufacturers.
This creates a tension between legal vulnerability and practical competition. COMPRO may have weak patent protection but retain some commercial value if manufacturing complexity and low market size discourage aggressive entry.
How strong is the COMPRO patent estate?
The patent estate is likely weak by branded-pharmaceutical standards and moderate only in relation to manufacturing execution.
| Protection category | Estimated strength | Commercial effect |
|---|---|---|
| Active ingredient | Very weak | Historical protection expired |
| Core indication | Weak | Established antiemetic use is difficult to protect broadly |
| Rectal dosage form | Low to moderate | Narrow formulation claims may be possible |
| Manufacturing process | Moderate if proprietary | May increase entry cost but can be designed around |
| Trademark | Moderate for brand identity | Does not prevent generic substitution |
| Regulatory exclusivity | Minimal or expired | Does not materially delay entry |
The most valuable assets are likely the approved product, manufacturing know-how, customer relationships, and supply history. These assets can support a niche business but do not create a high barrier to substitution.
What commercial factors could increase COMPRO revenue?
Revenue upside would most likely come from execution rather than new clinical indications.
Potential drivers include:
- Winning hospital or group-purchasing contracts.
- Maintaining uninterrupted supply during competitor shortages.
- Expanding pharmacy and long-term-care distribution.
- Improving wholesaler availability.
- Preserving reimbursement in plans that cover rectal antiemetics.
- Developing package sizes suited to institutional use.
- Licensing or acquiring complementary antiemetic products.
A shortage-driven increase could be temporary. It should not be valued as recurring growth unless supply conditions persist and prescribing behavior changes.
What factors could reduce COMPRO revenue?
The principal downside factors are:
- Generic price erosion.
- Discontinuation or intermittent supply.
- Greater use of ondansetron ODT and injectable antiemetics.
- Hospital formulary removal.
- Reimbursement restrictions.
- Manufacturing-cost inflation.
- Safety concerns associated with phenothiazines.
- A competing prochlorperazine suppository with lower pricing.
- Reduced prescribing for older antiemetic agents.
The most severe scenario is not gradual competition but loss of reliable supply. A niche product can lose formulary presence quickly after repeated back orders.
What is the investment and licensing outlook for COMPRO?
COMPRO is more suitable as a portfolio add-on than as a standalone growth asset. Its value would be highest for a company that already has:
- U.S. hospital distribution.
- Suppository manufacturing capacity.
- A mature generic or specialty-pharmaceutical portfolio.
- Established relationships with wholesalers and group-purchasing organizations.
- Additional antiemetic or acute-care products for cross-selling.
A licensing transaction would likely depend on minimum purchase commitments, supply obligations, manufacturing transfer terms, and rights to related prochlorperazine products. A high upfront payment would be difficult to justify without verified sales, stable supply data, and evidence of durable reimbursement.
Key Takeaways
- COMPRO is a mature prochlorperazine 25 mg rectal suppository with a narrow U.S. market.
- Public sources do not disclose standalone COMPRO sales.
- Estimated annual U.S. net sales are approximately $5 million to $12 million, with a modeled base case of $8.8 million in 2029.
- The active ingredient has no meaningful remaining composition-of-matter exclusivity.
- Patent risk is likely lower than supply, reimbursement, and substitution risk.
- Direct competition comes from promethazine suppositories; broader competition comes from ondansetron, prochlorperazine tablets and injection, and metoclopramide.
- The strongest commercial asset is reliable availability in a dosage form used when oral administration is unsuitable.
- COMPRO is more attractive as a niche portfolio product than as a standalone growth platform.
FAQs About COMPRO Market Sales and Exclusivity
Is COMPRO still commercially available in the United States?
COMPRO has been marketed as a prescription prochlorperazine suppository. Current availability can vary by manufacturer, wholesaler inventory, and pharmacy distribution.
Does COMPRO have FDA exclusivity?
No meaningful new-drug exclusivity should be assumed for this mature prochlorperazine product. Any current protection would more likely involve product-specific patents, trademarks, or manufacturing know-how.
Is COMPRO a generic drug?
COMPRO is a branded product containing the established generic active ingredient prochlorperazine. Therapeutically equivalent prochlorperazine products can compete with it, subject to FDA approval and product-specific equivalence requirements.
What is the main reason physicians use COMPRO?
The principal reason is the rectal route, which can be useful when a patient cannot retain oral medication or when oral administration is impractical.
Could COMPRO sales grow materially?
Material growth is unlikely without a supply disruption affecting competing products, a new distribution strategy, or portfolio expansion. The base case is stable to modestly growing nominal revenue with limited unit-volume growth.
References
DailyMed. (n.d.). COMPRO- prochlorperazine suppository. U.S. National Library of Medicine. https://dailymed.nlm.nih.gov/
U.S. Food and Drug Administration. (n.d.-a). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
U.S. Food and Drug Administration. (n.d.-b). Drugs@FDA. https://www.accessdata.fda.gov/scripts/cder/daf/
U.S. Food and Drug Administration. (n.d.-c). Abbreviated new drug application approvals. https://www.fda.gov/drugs/abbreviated-new-drug-application-anda/anda-approvals
More… ↓
