Share This Page
Drug Sales Trends for PAXIL
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for PAXIL (2000)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
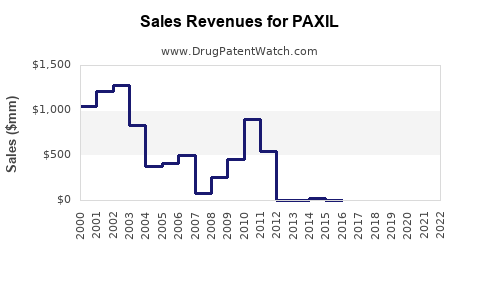
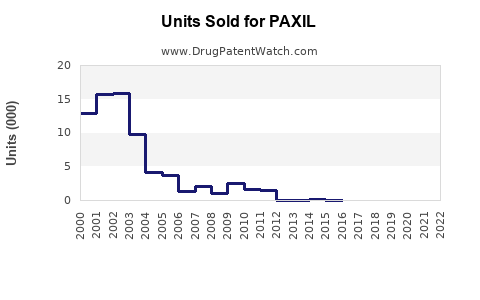
Annual Sales Revenues and Units Sold for PAXIL
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| PAXIL | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| PAXIL | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| PAXIL | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
# Paxil (Paroxetine) Market Analysis, Patent Status, Competitive Landscape, and Sales Projections
Paxil is a mature selective serotonin reuptake inhibitor (SSRI) with no remaining primary commercial exclusivity in the United States. The original brand, marketed by GSK, has been displaced by low-cost generic paroxetine. Current commercial value is concentrated in generic immediate-release and controlled-release products, while branded Paxil and Paxil CR address small residual segments.
The market outlook is stable to declining in value. Prescription demand remains supported by depression, generalized anxiety disorder, panic disorder, social anxiety disorder, obsessive-compulsive disorder, post-traumatic stress disorder, and premenstrual dysphoric disorder. Pricing, market share and revenue are constrained by competition from sertraline, escitalopram, fluoxetine, venlafaxine and other generic antidepressants.
A reasonable base-case estimate places global annual paroxetine product sales in the low hundreds of millions of dollars, with most value captured by generic manufacturers. U.S. branded Paxil sales are unlikely to be material relative to the historical peak.
What is Paxil and which products compete with paroxetine?
Paxil is the original brand for paroxetine hydrochloride, an SSRI developed by SmithKline Beecham and later marketed by GlaxoSmithKline. The FDA approved Paxil tablets in 1992. Paxil CR, an extended-release formulation, received FDA approval in 1999.
| Product | Active ingredient | Dosage form | Principal commercial status |
|---|---|---|---|
| Paxil | Paroxetine hydrochloride | Immediate-release tablet | Mature branded product |
| Paxil CR | Paroxetine hydrochloride | Controlled-release tablet | Mature branded product with generic competition |
| Brisdelle | Paroxetine mesylate | 7.5 mg capsule | Low-dose nonhormonal vasomotor-symptom product |
| Generic paroxetine | Paroxetine hydrochloride or mesylate | Tablet, capsule, oral suspension, extended-release tablet | Dominant U.S. supply |
| Sertraline | Sertraline hydrochloride | Tablet, capsule, oral concentrate | Major SSRI competitor |
| Escitalopram | Escitalopram oxalate | Tablet, solution | Major SSRI competitor |
| Fluoxetine | Fluoxetine hydrochloride | Capsule, tablet, solution | Major low-cost SSRI competitor |
| Venlafaxine | Venlafaxine hydrochloride | Tablet, extended-release capsule | SNRI competitor |
Paxil has broad FDA-approved psychiatric indications. Paroxetine is also used off-label in several anxiety and mood-related conditions, although off-label use does not create separate patent protection.
How large is the Paxil and paroxetine market?
The historical Paxil market was substantially larger than the current opportunity. GSK reported Paxil and Seroxat as major products during the late 1990s and early 2000s, when branded SSRI pricing and patent protection generated high revenue. Generic entry materially reduced sales after U.S. exclusivity ended.
The current market has three layers:
- Generic immediate-release paroxetine for common psychiatric indications.
- Generic controlled-release paroxetine, including products competing with Paxil CR.
- Residual branded demand for Paxil, Paxil CR and Brisdelle.
U.S. prescription volume remains commercially relevant, but revenue per prescription is low. Generic paroxetine is usually purchased through pharmacy benefit managers, Medicaid, Medicare Part D and cash-pay channels at prices far below historical branded levels.
Estimated market structure
| Segment | Current commercial position | Revenue outlook |
|---|---|---|
| U.S. generic immediate-release paroxetine | Largest volume segment | Stable volume, continued price pressure |
| U.S. generic extended-release paroxetine | Smaller, technically more differentiated segment | Low-growth or declining |
| Paxil and Paxil CR brand | Limited residual use | Continued decline or niche stabilization |
| Brisdelle | Small specialty indication | Potentially stable, but limited scale |
| International paroxetine | Highly fragmented generic market | Stable volume, low average pricing |
| Contract manufacturing and private-label supply | Important for low-cost distribution | Competitive, margin constrained |
Public company filings no longer provide a reliable standalone Paxil revenue series. GSK reports at a portfolio level, and generic manufacturers generally do not disclose paroxetine revenue separately. Current market sizing therefore requires a prescription-volume and net-price model rather than a direct branded-sales extrapolation.
What are the Paxil sales projections for 2025 through 2029?
The following projection estimates the total global commercial market for paroxetine products, including generic and branded sales. It is an analyst model based on mature-SSRI prescription behavior, generic pricing, limited branded demand and the absence of new exclusivity.
| Year | Bear case | Base case | Upside case |
|---|---|---|---|
| 2025 | $105 million | $155 million | $220 million |
| 2026 | $98 million | $150 million | $222 million |
| 2027 | $91 million | $145 million | $225 million |
| 2028 | $84 million | $140 million | $228 million |
| 2029 | $77 million | $135 million | $230 million |
| 2025-2029 CAGR | -7.3% | -3.4% | 1.1% |
These figures represent product-market revenue rather than GSK revenue. They exclude hospital purchasing that cannot be separated from broader antidepressant procurement and exclude unrelated SSRI products.
Base-case assumptions
The base case assumes:
- U.S. paroxetine prescriptions remain broadly stable to modestly lower.
- Generic net prices decline gradually rather than collapse.
- Brand Paxil revenue remains a small fraction of the market.
- Extended-release products retain some value because of formulation complexity.
- International markets offset part of the U.S. decline.
- No major new clinical indication materially expands use.
- No manufacturer secures durable premium pricing through a new delivery technology.
Under this model, generic manufacturers capture more than 90% of total paroxetine product revenue by 2029. Branded Paxil and Paxil CR would represent a small residual share, primarily from prescriber preference, patient continuity, limited formulary exceptions and markets where branded products remain available.
Revenue exposure for GSK
GSK’s historical Paxil exposure was substantial, but the product is no longer a core growth asset. Revenue exposure is limited by:
- Expired composition-of-matter protection.
- Generic substitution.
- Absence of a meaningful current Orange Book exclusivity position.
- The company’s portfolio shift toward vaccines, specialty medicines and respiratory products.
- Declining commercial importance of legacy CNS products.
A current GSK valuation should not assign material growth value to Paxil. Any residual brand revenue would be a maintenance contribution, not a strategic growth driver.
When did Paxil lose exclusivity?
Paxil lost effective U.S. market exclusivity in the early 2000s. The original paroxetine compound and core product patents expired before the current period, and generic manufacturers entered the market following patent litigation and regulatory approvals.
The main exclusivity events were:
| Event | Approximate timing | Commercial effect |
|---|---|---|
| FDA approval of Paxil | 1992 | Beginning of U.S. branded commercialization |
| Paxil CR approval | 1999 | Extension into controlled-release product |
| Generic litigation and abbreviated new drug applications | Early 2000s | Delayed but did not prevent generic entry |
| Generic immediate-release competition | 2003 onward | Rapid erosion of brand pricing and share |
| Generic extended-release competition | Later 2000s and 2010s | Further erosion of Paxil CR value |
| Current period | 2025 | No commercially relevant primary exclusivity |
Paxil has no remaining new chemical entity exclusivity. Any pediatric exclusivity associated with the original product has long expired.
What patents protect Paxil and paroxetine?
The original Paxil patent estate is expired or commercially exhausted in the United States. The estate historically covered the paroxetine compound, pharmaceutical salts, formulations and methods of treatment.
Historically relevant U.S. patent families included patents directed to:
- Paroxetine and related compounds.
- Paroxetine hydrochloride hemihydrate.
- Controlled-release paroxetine formulations.
- Methods of treating depression and anxiety disorders.
- Manufacturing and solid-state forms.
The Orange Book remains the controlling FDA source for currently listed patents and patent certifications. A present-day review should distinguish between expired patents, delisted patents, patents with no practical blocking effect and any remaining formulation or method-of-use listings. FDA, Orange Book, and ANDA records are the primary sources for that determination. [1]
How strong is the Paxil patent estate?
The patent estate is weak as a barrier to standard generic entry.
| Patent category | Current strength |
|---|---|
| Original compound patent | Expired |
| Core pharmaceutical composition claims | Expired or commercially exhausted |
| Immediate-release formulation claims | Weak against standard generic substitution |
| Controlled-release formulation claims | Historically more relevant, but substantially eroded |
| Method-of-use claims | Limited practical value where indication claims are carved out |
| Manufacturing claims | Potentially relevant to specific processes, not a broad market block |
| New chemical entity exclusivity | Expired |
| Biosimilar exclusivity | Not applicable |
The remaining intellectual-property risks are formulation-specific and jurisdiction-specific. They do not recreate the original Paxil monopoly.
What is the Orange Book status of Paxil?
Paxil is an FDA-approved small-molecule drug, not a biologic. Its U.S. regulatory pathway is therefore an ANDA pathway for generic products rather than a biosimilar pathway.
The current commercial implications are:
- Generic paroxetine manufacturers can rely on ANDA approvals.
- Paragraph IV litigation risk is primarily historical.
- A new generic entrant would generally face formulation, labeling, manufacturing and bioequivalence questions rather than a fundamental compound-patent barrier.
- Any listed method-of-use patents could be addressed through a section viii “skinny label” where legally and regulatorily appropriate.
- Paxil CR competition may require more complex bioequivalence evidence than immediate-release tablets.
The FDA label identifies paroxetine hydrochloride products and their approved indications, dosing, contraindications and warnings. Paroxetine carries class warnings associated with antidepressants, including suicidality risk in pediatric and young adult patients, serotonin syndrome, discontinuation reactions and interactions with monoamine oxidase inhibitors. [2]
Which companies compete with Paxil?
Competition comes from both paroxetine suppliers and alternative antidepressant manufacturers.
Direct generic competitors
The U.S. generic market has included manufacturers such as:
- Apotex
- Mylan, now part of Viatris
- Teva
- Sandoz
- Dr. Reddy’s Laboratories
- Lupin
- Zydus
- Amneal
- Solco Healthcare
- Various authorized-generic and private-label suppliers
The precise active supplier set changes because of product discontinuations, manufacturing transfers, shortages and contract arrangements. Paroxetine is generally a multi-source generic product, which limits sustainable pricing power.
Therapeutic competitors
The most important competing products are sertraline, escitalopram, fluoxetine and venlafaxine. Escitalopram and sertraline have stronger contemporary prescribing positions in many depression and anxiety treatment pathways. Fluoxetine remains a low-cost alternative with long clinical familiarity.
Paroxetine retains differentiation through:
- Long clinical history.
- Broad anxiety-related indication coverage.
- Availability in immediate-release and extended-release forms.
- Established physician familiarity.
- Specific use in premenstrual dysphoric disorder.
- Lower acquisition cost in some formularies.
Its disadvantages include anticholinergic effects, weight gain concerns, sexual dysfunction, discontinuation symptoms and CYP2D6 inhibition. These factors can drive prescribers toward sertraline, escitalopram or fluoxetine.
Are generic manufacturers challenging Paxil through Paragraph IV filings?
Paragraph IV challenges were central to the historical generic-entry process. Generic manufacturers challenged Orange Book patents by asserting that patents were invalid, unenforceable or not infringed. Litigation involving GSK and generic companies affected the timing of paroxetine entry in the early 2000s.
The commercial significance of new Paragraph IV activity is now limited because the principal Paxil patent barriers have expired. A future Paragraph IV case would be more likely to target a specific extended-release formulation, dosage form or later-listed patent than the original paroxetine molecule.
What patent litigation affects Paxil?
The most important litigation period occurred before and around generic launch. The disputes focused on GSK’s Paxil patents and generic manufacturers’ attempts to obtain ANDA approval and market entry.
The litigation had four lasting effects:
- It delayed some generic competition.
- It tested the scope and enforceability of paroxetine formulation patents.
- It influenced settlement and launch arrangements.
- It accelerated the shift from branded Paxil revenue to generic supply economics.
No current litigation appears capable of restoring broad Paxil exclusivity in the United States. Any active dispute would need to be evaluated by patent number, dosage form, jurisdiction and product labeling.
What generic entry risks exist for Paxil?
Generic entry risk is no longer a future event for immediate-release Paxil. It is the established market structure.
The remaining risks are commercial rather than exclusivity-related:
- Further price compression from additional suppliers.
- Loss of formulary preference.
- Manufacturing interruptions.
- FDA warning-letter or plant-compliance events.
- Discontinuation of low-volume strengths.
- Substitution by sertraline or escitalopram.
- Reduced physician use because of tolerability and withdrawal concerns.
- Consolidation among active pharmaceutical ingredient suppliers.
For Paxil CR, the principal risk is continued substitution by lower-cost extended-release paroxetine and therapeutic alternatives. Controlled-release products can sustain somewhat higher pricing than immediate-release tablets, but the premium is limited by generic competition.
What formulations are protected by Paxil patents?
Paxil’s historic formulation value centered on controlled-release paroxetine. Paxil CR used a formulation designed to release paroxetine over an extended period, with the aim of modifying exposure and dosing convenience.
The commercial protection has weakened for three reasons:
- Formulation patents have expired or lost practical blocking power.
- Generic manufacturers have developed extended-release products.
- Prescribers can switch patients to immediate-release paroxetine or other SSRIs.
Brisdelle is a separate low-dose paroxetine product marketed for moderate-to-severe vasomotor symptoms associated with menopause. Its commercial opportunity is narrower than Paxil’s psychiatric market. It competes with hormone therapy, nonhormonal prescription options and over-the-counter products. It does not materially change the broader paroxetine outlook.
Does Paxil face biosimilar risk?
No. Paxil is a chemically synthesized small molecule, so biosimilar competition does not apply. The relevant competitive pathway is generic substitution under the Hatch-Waxman framework.
This distinction matters for investment analysis. Paxil does not have biologic manufacturing complexity, interchangeability litigation or biosimilar exclusivity dynamics. Its market risk is driven by ordinary generic competition, API sourcing and reimbursement pressure.
What licensing deals and settlements affected Paxil?
GSK entered into agreements with generic manufacturers during the period when Paxil patents were being challenged. The best-known commercial disputes involved generic entry timing, patent litigation and supply or settlement arrangements.
These agreements were scrutinized because delayed generic entry can materially affect SSRI pricing and payer costs. The Federal Trade Commission and U.S. Department of Justice have treated pharmaceutical settlements involving potential delayed entry as competition-sensitive. [3]
Current licensing value is limited. The important transaction opportunities are more likely to involve:
- Regional distribution rights.
- Private-label generic supply.
- Branded-generic portfolios.
- Manufacturing rights for extended-release products.
- API or finished-dose supply agreements.
A new license covering the original Paxil molecule would not create meaningful global exclusivity.
What is the outlook for Paxil’s competitive position?
Paxil is a defensive, low-growth generic market rather than an innovation market.
| Factor | Assessment |
|---|---|
| Demand | Mature and gradually declining |
| Pricing | Low and subject to payer pressure |
| Brand strength | Historically high, currently limited |
| Generic intensity | High |
| Patent protection | Weak or expired |
| Regulatory complexity | Moderate for extended-release products |
| Manufacturing barriers | Low to moderate |
| Clinical differentiation | Narrow |
| Revenue growth potential | Low |
| Acquisition appeal | Limited unless bundled with a broader generic portfolio |
The strongest commercial position belongs to manufacturers with reliable API access, efficient low-cost production, broad wholesaler relationships and multiple paroxetine strengths. A standalone Paxil strategy has limited upside. A paroxetine product can still be attractive as part of a diversified CNS generic portfolio.
Key Takeaways
- Paxil is a mature SSRI with no meaningful U.S. primary exclusivity.
- Generic paroxetine captures most current market volume and revenue.
- GSK’s historical Paxil sales are not representative of current commercial value.
- The base-case global paroxetine market is estimated at about $155 million in 2025, declining to approximately $135 million by 2029.
- Immediate-release paroxetine faces intense price competition.
- Extended-release paroxetine has greater formulation complexity but no broad monopoly protection.
- Paxil has no biosimilar risk because it is a small-molecule drug.
- Current risks are generic pricing, supplier concentration, manufacturing reliability and therapeutic substitution.
- The strongest competing antidepressants are sertraline, escitalopram, fluoxetine and venlafaxine.
- Paxil should be valued as a declining generic-market product, not as an active branded-growth asset.
FAQs
What was Paxil’s peak annual sales?
Paxil reached multibillion-dollar global sales during its branded peak in the late 1990s and early 2000s, before generic competition materially reduced price and share. GSK later stopped reporting Paxil as a separately meaningful growth product.
Is Paxil still sold as a brand in the United States?
Brand Paxil and Paxil CR may remain available through limited channels, but generic paroxetine is the dominant U.S. supply source. Availability and reimbursement depend on the product, strength and distributor.
Which paroxetine formulation has the greatest commercial value?
Immediate-release paroxetine has the largest volume opportunity. Extended-release paroxetine can command higher unit value but serves a smaller market and requires more complex bioequivalence and manufacturing capabilities.
Can a generic manufacturer obtain exclusivity for paroxetine today?
A new manufacturer generally cannot obtain exclusivity for the original paroxetine molecule. Limited exclusivity could arise from a genuinely new formulation, delivery system, pediatric indication or qualifying regulatory innovation, subject to FDA approval and patent protection.
Is paroxetine a more attractive generic opportunity than escitalopram?
Usually not on a standalone basis. Escitalopram has stronger contemporary prescribing demand in many markets, while paroxetine benefits from established use and low manufacturing cost. The relative attractiveness depends on supplier competition, reimbursement and the target country.
References
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (2023). Paxil prescribing information. GlaxoSmithKline. https://www.accessdata.fda.gov/drugsatfda_docs/label/
-
Federal Trade Commission. (2013). Pay-for-delay: How drug company pay-offs cost consumers billions. https://www.ftc.gov/reports/pay-delay-how-drug-company-pay-offs-cost-consumers-billions
-
GlaxoSmithKline. (2003). Annual report 2003. https://www.gsk.com/en-gb/investors/financial-results/
-
U.S. Food and Drug Administration. (1992). Paxil approval history and labeling records. Drugs@FDA. https://www.accessdata.fda.gov/scripts/cder/daf/
More… ↓
