Share This Page
Drug Sales Trends for ESOMEPRAZOLE
✉ Email this page to a colleague
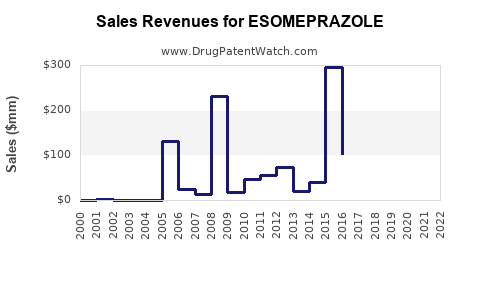
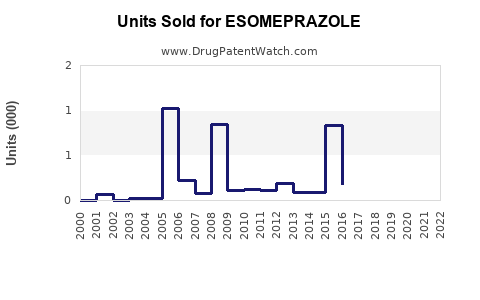
Annual Sales Revenues and Units Sold for ESOMEPRAZOLE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ESOMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ESOMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ESOMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ESOMEPRAZOLE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Esomeprazole Market Analysis and Sales Projections Through 2030
Esomeprazole is a mature proton-pump inhibitor with strong global demand but limited pricing power. The original Nexium franchise has lost composition-patent protection in the United States and major European markets. Future revenue will come primarily from generic volume, over-the-counter products, hospital supply, branded generics and selected international markets rather than premium patented sales.
A reasonable base-case estimate places global esomeprazole product sales at approximately $1.8 billion to $2.4 billion in 2024, with revenue declining toward $1.4 billion to $2.0 billion by 2030. Volume should remain stable or increase modestly, while average selling prices continue to decline.
What is the current market position of esomeprazole?
Esomeprazole is the S-isomer of omeprazole and is marketed mainly for gastroesophageal reflux disease, erosive esophagitis, peptic-ulcer disease, Helicobacter pylori eradication regimens and prevention of nonsteroidal anti-inflammatory drug-associated ulcers.
The reference product is Nexium, originally developed and commercialized by AstraZeneca. U.S. prescription approval for Nexium delayed-release capsules was granted in 2001, followed by an injectable formulation and an over-the-counter switch for Nexium 24HR in 2003 (U.S. Food and Drug Administration [FDA], 2001, 2003).
| Market attribute | Assessment |
|---|---|
| Molecule | Esomeprazole magnesium and esomeprazole sodium |
| Primary class | Proton-pump inhibitor |
| Reference brand | Nexium |
| Main dosage forms | Delayed-release capsules, tablets, granules, oral suspension, injection |
| Prescription status | Generic competition established |
| OTC status | Nexium 24HR in the United States |
| Main commercial markets | United States, Europe, Japan, China, Latin America and the Middle East |
| Patent status | Core U.S. exclusivity expired |
| Commercial phase | Mature, genericized product |
| Primary growth driver | Population volume and OTC demand |
| Primary revenue risk | Generic price erosion and substitution by other PPIs |
AstraZeneca reported peak annual Nexium sales of approximately $5 billion during the product’s protected commercial period. Nexium remained one of the company’s largest products before patent expiry, but AstraZeneca’s later public reporting no longer provides a complete global revenue figure for the entire esomeprazole molecule across generic manufacturers (AstraZeneca, 2006, 2015).
How large is the global esomeprazole market?
No public regulatory database reports consolidated global esomeprazole sales across branded, generic, OTC and hospital channels. Public company filings generally disclose reference-brand revenue but not total molecule revenue. The following estimate uses historical Nexium sales, generic entry, prescription utilization, OTC demand and the scale of the global PPI market.
| Year | Estimated global esomeprazole sales | Estimated annual change | Market interpretation |
|---|---|---|---|
| 2024 | $1.8-$2.4 billion | Baseline | Mature global generic market |
| 2025 | $1.7-$2.3 billion | -4% to -6% | Continued price erosion |
| 2026 | $1.6-$2.2 billion | -3% to -5% | Stable volume, lower prices |
| 2027 | $1.5-$2.1 billion | -2% to -4% | OTC and emerging-market offset |
| 2028 | $1.5-$2.0 billion | -1% to -3% | Slower erosion |
| 2029 | $1.4-$2.0 billion | -1% to -3% | Mature demand |
| 2030 | $1.4-$2.0 billion | -1% to -2% | Long-tail generic market |
These figures represent an analytical market estimate, not reported manufacturer revenue. The range reflects differences in whether estimates include hospital injectable products, private-label OTC products and sales in low- and middle-income countries.
What explains the difference between volume and revenue?
Esomeprazole demand is relatively defensive because reflux disease is chronic, the product is inexpensive and treatment is available through both prescription and OTC channels. Revenue is less defensive because multiple manufacturers sell therapeutically substitutable products.
The market has four distinct economic segments:
- Prescription generic capsules and tablets.
- OTC delayed-release products.
- Hospital injectable esomeprazole.
- Branded generics in countries where physician prescribing remains brand-oriented.
Prescription products account for most volume in many countries. OTC products have a higher retail price but face competition from store brands and other PPIs. Injectable esomeprazole has higher unit economics but represents a smaller share of total molecule demand.
When did esomeprazole lose patent exclusivity?
The principal U.S. Nexium compound patent was U.S. Patent No. 5,714,504, covering esomeprazole and related compositions. The patent had an expiration date in 2014, subject to applicable patent-term and pediatric-exclusivity calculations. Generic esomeprazole delayed-release products entered the U.S. market during 2015 after the principal exclusivity period ended (U.S. Patent and Trademark Office, 2014; FDA, 2015).
| Exclusivity element | Status |
|---|---|
| U.S. prescription approval | 2001 |
| U.S. OTC switch | 2003 |
| Core U.S. composition patent | Expired in 2014 |
| Generic U.S. entry | Began in 2015 |
| Current composition-patent barrier | None for standard esomeprazole products |
| Current commercial protection | Brand recognition, distribution, OTC shelf position and formulation execution |
Patent expiry did not eliminate all possible intellectual-property rights. Secondary patents historically covered formulations, dosage forms, manufacturing processes and specific therapeutic uses. Those rights generally had narrower scope than the original composition protection and were less capable of preserving broad market exclusivity.
What patents protect esomeprazole products today?
The commercially important patent estate is now primarily historical. The core patent strategy included protection for the active S-isomer, pharmaceutical compositions, formulations and manufacturing methods.
| Patent category | Commercial relevance after generic entry |
|---|---|
| Active-ingredient or stereochemical patents | Low for standard esomeprazole products after expiry |
| Delayed-release formulations | Potentially relevant to specific release profiles or excipient combinations |
| Injectable formulations | Relevant to hospital products and manufacturing design-arounds |
| Manufacturing processes | Can affect cost and supply but rarely block all competitors |
| Method-of-use patents | Narrower protection, usually tied to a defined patient group, dose or indication |
| Combination-treatment claims | Limited commercial value unless broadly enforceable |
| OTC packaging and trade dress | Brand and regulatory protection rather than patent exclusivity |
The practical barrier is no longer a single blocking patent. It is the combined cost of regulatory approval, bioequivalence testing, manufacturing validation, supply reliability and distribution access.
What formulations are protected by esomeprazole patents?
Esomeprazole is acid-labile, so delayed-release delivery is central to product performance. Commercial formulations include enteric-coated pellets in capsules, delayed-release tablets, oral granules and injectable sodium esomeprazole.
Formulation-related differentiation can involve:
- Enteric coating composition.
- Particle or pellet size.
- Release timing.
- Stability under storage conditions.
- Capsule or tablet architecture.
- Reconstitution characteristics for oral suspension.
- Injectable concentration and dilution requirements.
A formulation patent may create a litigation issue for a particular generic product, but it usually does not prevent development of an alternative formulation with equivalent therapeutic performance.
What is the FDA and Orange Book status of esomeprazole?
The FDA has approved multiple prescription esomeprazole products and generic versions of Nexium-equivalent dosage forms. The Orange Book identifies approved products and any patents or exclusivity associated with applicable reference products. The core Nexium patent protection has expired, and the U.S. market has established generic competition (FDA, 2024).
Nexium 24HR is regulated as an OTC product. OTC competition includes private-label esomeprazole and other acid-reducing medicines, including omeprazole and lansoprazole. OTC products are purchased without a prescription and compete on price, retailer placement, package count and consumer familiarity.
FDA status supports continued market access but does not provide meaningful molecule-wide exclusivity. Generic manufacturers can compete through abbreviated new drug applications, while OTC manufacturers can rely on approved monograph pathways or product-specific approvals depending on the formulation and regulatory category.
Which companies compete in the esomeprazole market?
Competition varies by country. The leading participants include AstraZeneca for Nexium, large generic manufacturers, regional branded-generic companies and retailers selling private-label OTC products.
| Company group | Typical role |
|---|---|
| AstraZeneca | Nexium prescription and OTC brand rights in applicable markets |
| Viatris | Generic and branded-generic supply |
| Teva | Generic prescription supply |
| Dr. Reddy’s Laboratories | Generic and international supply |
| Sandoz | Generic supply in multiple markets |
| Sun Pharma | Generic and branded-generic products |
| Cipla | Regional generic and international supply |
| Torrent Pharmaceuticals | Branded generics, particularly in emerging markets |
| Regional manufacturers | Country-specific prescription and OTC products |
| Retailers and private-label operators | Low-cost OTC distribution |
The competitive landscape is fragmented. No single generic supplier controls the global molecule market. Local regulatory approvals, tender participation and distribution agreements determine share in many countries.
How does esomeprazole compare with omeprazole and other PPIs?
Esomeprazole has a strong brand history but does not have a durable clinical or pricing advantage across the entire PPI category. Omeprazole is generally cheaper and widely available. Pantoprazole has substantial hospital and prescription use. Lansoprazole and rabeprazole compete in selected markets. Vonoprazan, a potassium-competitive acid blocker, is a potential higher-value competitor in indications where faster or more sustained acid suppression is preferred.
| Product | Competitive position | Price risk | Main advantage |
|---|---|---|---|
| Esomeprazole | Mature global PPI | High | Nexium brand, OTC presence, broad formulation range |
| Omeprazole | Largest low-cost substitute in many markets | Very high | Low cost and extensive generic availability |
| Pantoprazole | Strong prescription and hospital position | High | Institutional familiarity and injectable use |
| Lansoprazole | Established secondary PPI | High | Broad generic availability |
| Rabeprazole | Smaller but established share | Moderate to high | Physician preference in selected markets |
| Vonoprazan | Newer acid-suppression competitor | Lower current generic pressure | Different mechanism and potential efficacy positioning |
Esomeprazole is most vulnerable where payers treat PPIs as interchangeable. It is more resilient in OTC channels, premium branded-generic markets and countries where Nexium remains a recognized consumer brand.
What sales projections are most likely through 2030?
The base case assumes stable global treatment volume, annual net price erosion of approximately 3% to 5% in mature markets and modest volume growth in emerging markets.
Base-case forecast
| Year | Global sales estimate | Volume trend | Price trend |
|---|---|---|---|
| 2024 | $1.8-$2.4 billion | Stable | Declining |
| 2025 | $1.7-$2.3 billion | Slight increase | Declining |
| 2026 | $1.6-$2.2 billion | Slight increase | Declining |
| 2027 | $1.5-$2.1 billion | Stable to slight increase | Declining |
| 2028 | $1.5-$2.0 billion | Stable | Moderate decline |
| 2029 | $1.4-$2.0 billion | Stable | Moderate decline |
| 2030 | $1.4-$2.0 billion | Stable to slight increase | Moderate decline |
Scenario analysis
| Scenario | 2030 sales estimate | Key assumptions |
|---|---|---|
| Bear case | $1.1-$1.4 billion | Aggressive generic substitution, OTC price competition, greater use of alternatives |
| Base case | $1.4-$2.0 billion | Stable demand, continuing price erosion and moderate emerging-market growth |
| Upside case | $2.0-$2.6 billion | Strong OTC expansion, increased diagnosis of reflux disease and higher international volume |
The upside case is more likely to affect unit volume than manufacturer margin. Generic competition limits the ability of suppliers to convert higher demand into proportional revenue growth.
What generic launch risks exist for esomeprazole?
Generic launch risk is low for standard delayed-release products because the market already has multiple approved competitors. The main risks affect individual manufacturers rather than the molecule as a whole.
Regulatory and technical risks
Manufacturers must demonstrate bioequivalence and control delayed-release performance. Acid-labile drugs can be sensitive to formulation changes, coating defects, moisture exposure and stability failures. Injectable products face additional risks involving sterility, compatibility and hospital procurement requirements.
Commercial risks
A new entrant may face:
- Low reimbursement ceilings.
- Tender-driven price reductions.
- Limited pharmacy shelf space.
- Dependence on a small number of active pharmaceutical ingredient suppliers.
- Product recalls caused by dissolution or stability failures.
- Weak OTC brand recognition.
- Retailer concentration in the United States and Europe.
Manufacturing scale is more important than patent ownership. Suppliers with low-cost API access, validated coating technology and diversified regulatory approvals should have the strongest long-term position.
What patent litigation and Paragraph IV activity affect esomeprazole?
Historical U.S. litigation involved AstraZeneca’s efforts to defend Nexium patents against generic manufacturers, including challenges to patents covering the active ingredient and related formulations. The major commercial consequence was delayed generic entry until the principal protection expired.
Current Paragraph IV risk is limited for the basic molecule because the principal patent barrier has expired. Future litigation is more likely to involve:
- A specific delayed-release formulation.
- An injectable presentation.
- A method-of-use claim.
- A manufacturing process.
- A product-specific patent listed for a later-approved formulation.
The commercial value of such litigation is narrower than the original Nexium patent disputes. A successful challenge could protect one product presentation without restoring molecule-wide exclusivity.
Are licensing deals important for esomeprazole?
Licensing remains relevant for geographic rights, OTC commercialization, manufacturing and distribution, but it is less important than during the patented period. Nexium commercialization historically relied on AstraZeneca’s global development and sales infrastructure, while generic esomeprazole is commonly supplied through country-specific partnerships and contract manufacturing.
The most valuable transactions are likely to involve:
- OTC rights in specific countries.
- Hospital injectable distribution.
- API supply agreements.
- Branded-generic portfolios.
- Regional regulatory approvals.
- Retailer private-label supply.
Licensing economics are typically volume-based and price-sensitive. The absence of broad patent exclusivity reduces royalty potential and shifts value toward manufacturing cost, regulatory coverage and channel access.
What revenue exposure does esomeprazole create for manufacturers?
For AstraZeneca, Nexium is no longer a primary growth asset relative to newer oncology, respiratory and immunology products. For generic manufacturers, esomeprazole can provide recurring volume but usually has limited margin unless the company controls API production or holds strong regional distribution.
| Stakeholder | Revenue exposure |
|---|---|
| Reference-brand holder | Low growth, residual brand and OTC revenue |
| Large generic manufacturer | Stable volume, price-sensitive margin |
| API producer | Potentially attractive scale economics |
| Hospital supplier | Higher value per unit for injection |
| OTC retailer | Moderate category turnover, strong price competition |
| Regional branded-generic company | Higher margin where physician loyalty persists |
The molecule is strategically useful as part of a broader gastrointestinal portfolio. It is less attractive as a standalone investment thesis based solely on patent protection.
How strong is the esomeprazole patent estate?
The current patent estate is weak as a molecule-wide barrier and moderate for specific formulations or delivery systems.
| Patent-strength factor | Current assessment |
|---|---|
| Core composition protection | Weak or expired |
| Formulation protection | Narrow to moderate |
| Method-of-use protection | Narrow |
| Manufacturing protection | Potentially relevant but design-around risk is high |
| Regulatory exclusivity | No broad current exclusivity |
| Brand protection | Stronger in OTC channels than prescription channels |
| Supply-chain advantage | Potentially meaningful |
| Litigation leverage | Limited compared with the pre-generic period |
The strongest competitive positions are likely to come from cost leadership, validated quality systems, hospital contracts and OTC distribution rather than enforceable molecule patents.
Key Takeaways
- Esomeprazole is a mature, genericized PPI with persistent global demand.
- Estimated 2024 global sales are approximately $1.8 billion to $2.4 billion across prescription, OTC, hospital and branded-generic channels.
- Base-case 2030 sales are approximately $1.4 billion to $2.0 billion.
- Volume should remain stable, but price erosion will pressure revenue.
- The core Nexium U.S. patent expired in 2014, and generic entry followed in 2015.
- Current patent value is concentrated in formulations, injectables, manufacturing methods and narrow uses.
- OTC brand recognition and international branded-generics provide the strongest residual commercial protection.
- Generic manufacturers with low-cost API supply and broad regulatory coverage have the best market position.
- Vonoprazan is the most relevant newer mechanism-based competitive threat, while omeprazole and pantoprazole remain the principal low-cost substitutes.
- Esomeprazole is more attractive as part of a gastrointestinal portfolio than as a standalone protected asset.
FAQs
What was Nexium’s peak annual sales?
Nexium generated approximately $5 billion in annual sales during its peak protected commercial period, according to AstraZeneca’s historical reporting.
Is esomeprazole still a profitable drug?
Yes, but profitability depends on manufacturing scale, API costs, formulation efficiency and distribution access. The product no longer supports the margins associated with a patented branded medicine.
Does esomeprazole have biosimilar competition?
No. Esomeprazole is a chemically synthesized small molecule, so competitors are regulated as generic drugs rather than biosimilars.
Which esomeprazole formulation has the highest commercial value?
Delayed-release oral capsules and tablets have the largest volume. Injectable esomeprazole can generate higher revenue per unit but serves a smaller hospital market and has more demanding manufacturing requirements.
Can a new esomeprazole patent restore exclusivity?
A new patent could protect a specific formulation, manufacturing process or use, but it would be unlikely to restore broad exclusivity for the esomeprazole molecule after expiration of the core patents.
References
AstraZeneca. (2006). Annual report and form 20-F 2005. AstraZeneca PLC.
AstraZeneca. (2015). Annual report and form 20-F 2014. AstraZeneca PLC.
U.S. Food and Drug Administration. (2001). Nexium: FDA approval history and prescribing information. U.S. Department of Health and Human Services.
U.S. Food and Drug Administration. (2003). FDA approves over-the-counter Nexium 24HR. U.S. Department of Health and Human Services.
U.S. Food and Drug Administration. (2015). FDA approves first generic versions of Nexium. U.S. Department of Health and Human Services.
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, 44th edition. U.S. Department of Health and Human Services.
U.S. Patent and Trademark Office. (2014). Patent term adjustment and patent expiration records for U.S. Patent No. 5,714,504. U.S. Department of Commerce.
More… ↓
