Share This Page
Drug Sales Trends for BETADINE
✉ Email this page to a colleague
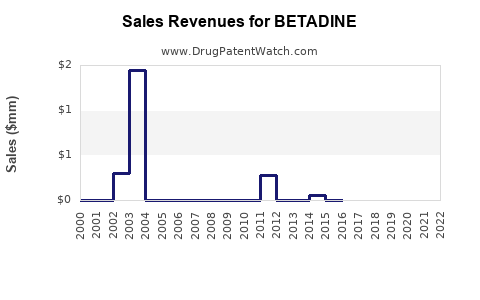
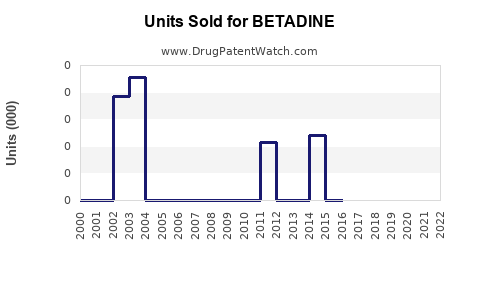
Annual Sales Revenues and Units Sold for BETADINE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| BETADINE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| BETADINE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| BETADINE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| BETADINE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| BETADINE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Betadine Market Analysis, Sales Projections, Patent Position, and Competitive Landscape
Betadine is a global povidone-iodine antiseptic brand used in wound care, preoperative skin preparation, surgical scrubs, and consumer first-aid products. Its commercial position is supported primarily by brand recognition, hospital procurement relationships, regulatory registrations, and distribution rather than by active-ingredient patent exclusivity. Global Betadine sales are not publicly reported as a standalone figure. A reasonable base-case estimate places 2024 Betadine retail and institutional sales near $300 million to $450 million, with projected annual growth of approximately 3% to 5% through 2030.
What is Betadine and who owns the brand?
Betadine products contain povidone-iodine, an iodine complex with broad-spectrum activity against bacteria, viruses, fungi, and some protozoa. Product concentrations vary by indication and geography.
| Item | Analysis |
|---|---|
| Brand | Betadine |
| Active ingredient | Povidone-iodine |
| Main uses | Wound antisepsis, surgical skin preparation, hand scrub, vaginal antisepsis, oral and dermatologic products |
| Brand owner | Mundipharma group has historically held major global Betadine rights |
| U.S. commercial rights | Betadine products have been commercialized through U.S. consumer-health entities, including Avrio Health |
| Prescription status | Primarily OTC and institutional, depending on product and jurisdiction |
| Primary competitors | Generic povidone-iodine, Hibiclens, chlorhexidine, alcohol-based antiseptics, hydrogen peroxide, octenidine |
| Patent profile | Low active-ingredient patent protection; brand, formulation, packaging, and regulatory rights are more relevant |
Ownership and commercialization vary by country. Betadine should therefore be assessed as a regional brand portfolio rather than as a single globally controlled pharmaceutical product.
How large is the povidone-iodine and antiseptic market?
Published market research estimates for the global povidone-iodine market generally place 2023-2024 sales in the range of $1.0 billion to $1.5 billion, depending on whether the estimate includes hospital products, consumer wound care, animal health, private-label products, and iodine-based surgical preparations.
The broader global antiseptics and disinfectants market is substantially larger, commonly estimated at more than $10 billion annually. Betadine competes within the narrower skin antiseptic segment, where product differentiation is limited and procurement price is important.
Estimated market structure
| Segment | Estimated 2024 global value | Growth outlook through 2030 |
|---|---|---|
| Hospital surgical antiseptics | $4.0B-$6.0B | 3%-5% |
| Consumer wound antiseptics | $2.0B-$3.0B | 3%-6% |
| Povidone-iodine products | $1.0B-$1.5B | 3%-5% |
| Betadine branded products | $300M-$450M | 3%-5% |
| Generic and private-label povidone-iodine | $600M-$1.0B | 2%-5% |
These figures are market-model estimates derived from public market reports, company disclosures, hospital antisepsis studies, and regional product availability. Betadine does not publish consolidated global revenue by brand.
What are Betadine’s estimated sales and revenue projections?
A base-case model assumes stable market share, moderate growth in hospital antisepsis, expansion of consumer wound care in emerging markets, and limited price increases.
Betadine global sales projection
| Year | Low case | Base case | High case |
|---|---|---|---|
| 2024 | $300M | $375M | $450M |
| 2025 | $306M | $390M | $468M |
| 2026 | $315M | $406M | $487M |
| 2027 | $324M | $422M | $506M |
| 2028 | $334M | $439M | $526M |
| 2029 | $344M | $457M | $547M |
| 2030 | $354M | $475M | $569M |
The base case implies a compound annual growth rate of approximately 4.0% from 2024 to 2030. The high case requires stronger emerging-market distribution, improved hospital penetration, and successful premiumization of products such as surgical prep applicators and specialty wound-care formats.
Revenue mix estimate
| Product channel | Approximate share of Betadine revenue |
|---|---|
| Hospitals and surgical facilities | 40%-50% |
| Pharmacies and mass retail | 25%-35% |
| E-commerce | 5%-10% |
| Professional distributors and clinics | 10%-15% |
| Other channels | 5%-10% |
Institutional revenue is likely to have lower gross margins than consumer products but greater volume stability. Retail and e-commerce products generally have higher unit economics and stronger brand visibility.
Which regions drive Betadine growth?
Asia-Pacific is likely to remain the largest growth region for Betadine and povidone-iodine products. The brand has significant recognition in markets where iodine antiseptics remain common in hospitals, pharmacies, and household wound care.
| Region | Market position | Growth drivers |
|---|---|---|
| Asia-Pacific | Core growth region | Population growth, hospital expansion, pharmacy distribution, high familiarity with iodine antiseptics |
| Europe | Mature market | Hospital procurement, pharmacy sales, surgical applications |
| Latin America | Moderate growth | Consumer wound care and public-health distribution |
| Middle East and Africa | Emerging market | Hospital infrastructure and infectious-disease prevention |
| United States | Competitive and mature | OTC first aid, specialty products, institutional use |
Regional performance is affected by local labeling rules, product registration, import requirements, hospital tenders, and the availability of low-cost generic povidone-iodine.
How does Betadine compare with competing antiseptics?
Betadine’s primary commercial advantage is broad-spectrum activity combined with long-standing brand recognition. Its main weakness is competition from chlorhexidine and alcohol-based preparations in modern surgical protocols.
| Product class | Principal ingredient | Commercial strength | Main limitation |
|---|---|---|---|
| Betadine | Povidone-iodine | Broad activity, established brand, wide format range | Potential concerns over iodine sensitivity, tissue irritation, and slower preference in some surgical settings |
| Hibiclens and related products | Chlorhexidine | Strong hospital use and persistent antimicrobial activity | Limited suitability for some body sites and risk of serious eye or ear injury |
| Alcohol preparations | Isopropyl or ethyl alcohol | Fast action and strong surgical-prep adoption | Flammability and limited residual activity |
| Hydrogen peroxide | Hydrogen peroxide | Low cost and consumer familiarity | Tissue toxicity and declining clinical preference for routine wound care |
| Octenidine products | Octenidine | Strong European hospital positioning | Less global distribution and lower consumer recognition |
Chlorhexidine-alcohol products represent the largest strategic threat in operating-room skin preparation. Generic povidone-iodine is the main threat in price-sensitive hospital tenders and retail channels.
What FDA regulatory status applies to Betadine?
In the United States, povidone-iodine topical antiseptic products are generally regulated under the FDA OTC antiseptic monograph framework when their formulation, concentration, labeling, and claims comply with applicable requirements.
The FDA recognizes povidone-iodine as an active ingredient for topical antiseptic use in specified concentrations and applications. Betadine products may be marketed as OTC drugs, while certain institutional or specialty products can be subject to additional regulatory requirements based on claims and formulation.
| Regulatory issue | Betadine implication |
|---|---|
| OTC status | Many first-aid products can use the OTC monograph pathway |
| Active ingredient | Povidone-iodine |
| Drug facts labeling | Required for U.S. OTC products |
| New drug application | May be unnecessary for compliant monograph products |
| Surgical preparation claims | Require product-specific compliance and labeling |
| International status | Varies by country; products may be registered as medicines, disinfectants, or medical products |
Regulatory changes affecting antiseptic active ingredients, efficacy testing, labeling, or contamination controls could increase compliance costs for branded and generic manufacturers.
What patents and exclusivity protect Betadine?
Betadine has limited protection from core drug patents because povidone-iodine is an established active ingredient with long generic availability. There is no meaningful period of new-molecule exclusivity comparable to a patented prescription drug.
Relevant protection categories
- Trademark protection. The Betadine name, logos, trade dress, and product presentation are commercially important.
- Formulation protection. Specific combinations, stabilizers, applicators, delivery systems, or specialty formats may receive patent protection, although such patents do not generally block ordinary povidone-iodine products.
- Packaging protection. Unit-dose systems, swab applicators, surgical kits, and dispensing configurations can create narrower competitive barriers.
- Regulatory registrations. Country-specific approvals and product registrations can delay competitors but do not create broad exclusivity.
- Manufacturing know-how. Stability control, iodine availability, packaging compatibility, sterility, and supply-chain execution can protect margins.
Orange Book and Paragraph IV exposure
Betadine is not primarily an Orange Book-driven product. Standard OTC monograph products generally do not create the same Paragraph IV litigation profile as patented prescription drugs. Generic manufacturers can sell competing povidone-iodine products if they satisfy FDA manufacturing, labeling, registration, and monograph requirements.
The principal legal risks are therefore trademark infringement, false advertising, trade dress, product liability, regulatory noncompliance, and channel-contract disputes rather than Hatch-Waxman patent litigation.
What formulations are protected by Betadine?
Betadine’s commercial portfolio may include:
- 5% and 10% povidone-iodine solutions
- Surgical scrubs
- Topical ointments
- Swabsticks and applicators
- Preoperative skin-preparation products
- Gargles and oral antiseptic products
- Vaginal preparations
- Wound-care sprays and specialty formats
- Hospital procedure kits
The highest-value formulation opportunities are concentrated in delivery systems that reduce preparation time, improve dosing consistency, limit contamination, or integrate with surgical workflow. Conventional bottles of povidone-iodine have limited differentiation and face direct generic substitution.
How strong is Betadine’s competitive position?
Betadine has a moderate commercial moat and a weak pharmaceutical exclusivity moat.
| Factor | Strength |
|---|---|
| Brand recognition | High |
| Active-ingredient differentiation | Low |
| Hospital purchasing relationships | Moderate to high |
| Retail shelf presence | High in core markets |
| Patent exclusivity | Low |
| Regulatory barriers | Moderate |
| Manufacturing complexity | Low to moderate |
| Switching costs | Low for standard solutions |
| Pricing power | Moderate in branded retail, low in tenders |
| Biosimilar risk | None |
Hospital customers can usually switch from Betadine to generic povidone-iodine without changing the underlying clinical category. Switching costs rise for preassembled surgical kits, validated protocols, private-label supply contracts, and products integrated into institutional purchasing systems.
What generic launch risks exist for Betadine?
Generic entry is continuous rather than event-driven. Competitors do not need to wait for a patent expiry to launch standard povidone-iodine products where local regulation permits.
The main generic risks are:
- Tender substitution in hospitals
- Retail private-label expansion
- Distributor substitution in emerging markets
- Online price competition
- Contract manufacturing by regional pharmaceutical companies
- Reduced willingness to pay for ordinary bottles and bulk solutions
Betadine can reduce substitution risk through applicator products, surgical kits, pharmacy education, packaging, quality consistency, and supply reliability. These measures support brand retention but do not prevent price competition.
What licensing deals and commercial partnerships affect Betadine?
Betadine’s commercial reach has historically depended on licensing, regional distribution, and country-specific commercialization arrangements. Rights may differ between consumer, hospital, surgical, oral, veterinary, and dermatologic applications.
Public disclosures do not provide a complete, current global schedule of Betadine licensing economics, minimum purchase commitments, royalties, or regional counterparties. The commercial value of a regional agreement depends on registration ownership, manufacturing rights, channel access, and whether the distributor controls hospital tenders.
What litigation affects Betadine?
Betadine does not have the recurring Paragraph IV litigation profile associated with high-value patented prescription medicines. Litigation exposure is more likely to arise from:
- Product liability and adverse-event claims
- Alleged misleading antiseptic or infection-prevention claims
- Trademark and trade dress disputes
- Distributor and licensing disagreements
- Regulatory actions involving labeling or manufacturing
- Hospital-contract disputes
- Competition between branded and private-label products
The absence of major patent litigation does not eliminate legal risk. It shifts the risk profile toward commercial conduct, quality systems, advertising claims, and product safety.
What are the main risks to Betadine sales?
Clinical substitution
Chlorhexidine-alcohol products have gained acceptance in surgical skin preparation. Changes in hospital protocols can reduce povidone-iodine volume even when the consumer brand remains strong.
Generic price pressure
Standard povidone-iodine solutions are relatively easy to manufacture. Hospitals and distributors may prioritize price over brand.
Supply-chain exposure
Povidone-iodine production depends on iodine supply, polymer availability, packaging components, sterile manufacturing capacity, and international logistics. Shortages can create temporary sales losses or favor substitute products.
Regulatory changes
Changes to OTC monograph requirements, antiseptic efficacy standards, or claims substantiation can require label revisions and new testing.
Product safety and claims
Improper claims involving infection prevention, wound healing, or surgical outcomes can trigger regulatory or litigation exposure. Formulation-specific warnings also affect use in neonates, thyroid-sensitive patients, and certain body sites.
What is the outlook for Betadine through 2030?
The base-case outlook is stable growth rather than rapid expansion. Betadine should benefit from:
- Growth in hospital procedure volumes
- Rising pharmacy and modern-retail penetration
- Greater use of unit-dose applicators
- Emerging-market healthcare investment
- Consumer preference for recognized antiseptic brands
- E-commerce expansion
Growth will be constrained by generic substitution, chlorhexidine adoption, limited active-ingredient differentiation, and price-sensitive hospital procurement.
Scenario analysis
| Scenario | 2030 sales estimate | Key assumptions |
|---|---|---|
| Downside | $350M-$400M | Share loss to chlorhexidine and private-label products; weak hospital pricing |
| Base case | $450M-$500M | 3%-5% annual growth; stable brand share and regional expansion |
| Upside | $550M-$650M | Strong applicator growth, emerging-market expansion, favorable distribution agreements |
Key Takeaways
- Betadine is a branded povidone-iodine antiseptic portfolio, not a patent-protected prescription franchise.
- Estimated 2024 global Betadine sales are approximately $300 million to $450 million.
- Base-case sales are projected to reach roughly $475 million by 2030.
- Asia-Pacific is the most important growth region.
- Generic povidone-iodine is the primary price threat.
- Chlorhexidine-alcohol products are the principal clinical competitor in surgical preparation.
- Betadine’s strongest barriers are brand recognition, hospital distribution, product registrations, and specialized delivery formats.
- Orange Book and Paragraph IV patent risk is limited relative to conventional branded prescription drugs.
- Revenue growth depends more on channel execution and product format innovation than on new chemical-entity exclusivity.
FAQs
Is Betadine a patented drug?
The active ingredient, povidone-iodine, is not protected by meaningful new-molecule patent exclusivity. Betadine relies on trademarks, formulations, packaging, registrations, and distribution.
Can generic companies sell povidone-iodine products?
Yes. Generic manufacturers can market compliant povidone-iodine products subject to applicable FDA or local regulatory requirements.
Does Betadine have biosimilar competition?
No. Betadine is a small-molecule topical antiseptic product and has no biosimilar pathway exposure.
Which product is more threatening to Betadine, chlorhexidine or generic povidone-iodine?
Generic povidone-iodine creates the greatest direct price threat. Chlorhexidine creates the greater long-term risk of clinical substitution in hospitals and surgical settings.
Is Betadine revenue publicly disclosed?
Standalone global Betadine revenue is not generally disclosed in audited public company filings. Sales estimates must be derived from market size, regional distribution, product availability, and channel assumptions.
References
- U.S. Food and Drug Administration. (2024). OTC monograph M003: Topical antiseptic drug products. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2024). Drug facts labeling and over-the-counter drug products. https://www.fda.gov
- World Health Organization. (2016). Global guidelines for the prevention of surgical site infection. World Health Organization. https://www.who.int
- Mundipharma. (2024). Betadine product and company information. https://www.mundipharma.com
- Centers for Disease Control and Prevention. (2024). Guideline for the prevention of surgical site infection. https://www.cdc.gov
- National Center for Biotechnology Information. (2023). Povidone-iodine. StatPearls Publishing. https://www.ncbi.nlm.nih.gov/books/
- U.S. Food and Drug Administration. (2023). OTC Monograph Order Request and administrative order procedures. https://www.fda.gov
More… ↓
