Share This Page
Drug Sales Trends for ezetimibe
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ezetimibe (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
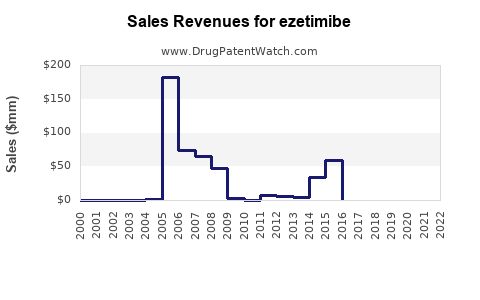
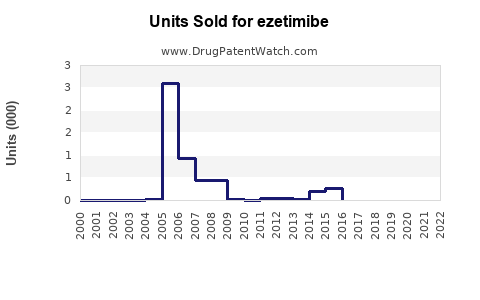
Annual Sales Revenues and Units Sold for ezetimibe
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| EZETIMIBE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| EZETIMIBE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| EZETIMIBE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| EZETIMIBE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| EZETIMIBE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| EZETIMIBE | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Ezetimibe Market Analysis, Sales Forecast, Patent Expiry, and Competitive Outlook
Ezetimibe is a mature, genericized cholesterol-lowering drug with durable demand driven by cardiovascular guidelines, statin intolerance, combination therapy, and broad availability. Global ezetimibe sales are estimated at approximately $1.3 billion to $1.7 billion in 2024, with volume growth offsetting continuing price erosion. Under a base-case model, the market reaches $1.5 billion to $1.9 billion by 2029, representing an estimated 2% to 4% annual value-growth rate.
The commercial opportunity is concentrated in generic supply, fixed-dose combinations, government reimbursement, and emerging markets. Branded Zetia and Vytorin no longer control the market after US generic entry. The principal risks are price compression, substitution by high-intensity statins and PCSK9 therapies, and limited differentiation among generic manufacturers.
What is ezetimibe and how is it used?
Ezetimibe is an oral cholesterol-absorption inhibitor that blocks the Niemann-Pick C1-like 1 protein in the intestinal brush border. It reduces low-density lipoprotein cholesterol by approximately 18% to 25% as monotherapy and produces a larger reduction when combined with a statin.
The FDA-approved indications include:
- Primary hyperlipidemia, alone or with a statin
- Homozygous familial hypercholesterolemia with atorvastatin or simvastatin
- Homozygous sitosterolemia
- Cardiovascular-risk reduction when added to statin therapy, based on the IMPROVE-IT clinical evidence base
The main commercial forms are 10 mg tablets and fixed-dose combinations with simvastatin, rosuvastatin, atorvastatin, and bempedoic acid. FDA labeling identifies Zetia as a 10 mg tablet originally marketed by Merck. [1]
Ezetimibe has several commercial advantages:
- It is oral and generally well tolerated.
- It is inexpensive compared with PCSK9 inhibitors and inclisiran.
- It has guideline support when statins do not achieve LDL-cholesterol targets.
- It is used in patients with statin intolerance or incomplete statin response.
- It is available as a generic in major markets.
How large is the global ezetimibe market?
Public market reports use different definitions. Some measure branded products, while others include all ezetimibe tablets and fixed-dose combinations. A practical market estimate should therefore distinguish between active-ingredient revenue and branded product revenue.
| Market measure | 2024 estimated value | 2029 base-case estimate | Expected trend |
|---|---|---|---|
| Global ezetimibe products, including combinations | $1.3B-$1.7B | $1.5B-$1.9B | Low-single-digit growth |
| US ezetimibe products | $350M-$550M | $360M-$500M | Flat to declining value |
| European ezetimibe products | $350M-$500M | $400M-$550M | Low growth |
| Asia-Pacific and other markets | $500M-$700M | $650M-$850M | Highest volume growth |
| Original branded Zetia/Vytorin products | Less than 15% of global value | Less than 10% | Continuing decline |
These figures are modeled estimates rather than a reported single-market total. They reflect generic pricing, prescription volume, fixed-dose combination sales, and regional reimbursement patterns. The market is more attractive on a unit-volume basis than on a revenue basis.
Which regions have the strongest ezetimibe growth?
Asia-Pacific, Latin America, and selected Middle Eastern markets have the strongest growth potential. The drivers are increasing diagnosis of dyslipidemia, wider use of combination therapy, government cardiovascular-prevention programs, and generic procurement.
North America and Western Europe remain large markets but are mature. Generic substitution is extensive, and reimbursement systems impose substantial price pressure. Japan, South Korea, China, Brazil, and Mexico offer volume opportunities, although local registration, tender access, and manufacturing requirements can affect profitability.
What are the main ezetimibe sales drivers?
Ezetimibe demand is driven by treatment intensification rather than premium pricing.
Cardiovascular guidelines and statin intolerance
Clinical guidelines recommend ezetimibe when LDL cholesterol remains above target despite maximally tolerated statin therapy or when statins are not tolerated. The 2018 American College of Cardiology/American Heart Association guideline placed ezetimibe after maximally tolerated statin therapy in several high-risk populations. [2]
The 2022 ACC pathway expanded practical use of nonstatin therapies in high-risk patients, including ezetimibe as an inexpensive oral option before injectable therapies. [3]
Combination therapy
Fixed-dose products can support adherence and procurement value. Relevant combinations include:
- Ezetimibe/simvastatin, marketed historically as Vytorin
- Ezetimibe/atorvastatin
- Ezetimibe/rosuvastatin
- Ezetimibe/bempedoic acid, including Nexlizet
Combination products are commercially important because they can preserve prescription value after monotherapy commoditization. They also create formulation and regulatory barriers that are more difficult to overcome than a standard 10 mg ezetimibe tablet.
Aging populations and cardiovascular disease
The global prevalence of cardiovascular disease and diabetes supports long-term demand for LDL reduction. The World Health Organization identifies cardiovascular disease as the leading global cause of death, supporting a large addressable treatment population. [4]
What are the ezetimibe sales projections through 2029?
The following model assumes continued generic price erosion, low-single-digit unit growth, and expanding use in emerging markets.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $1.3B | $1.5B | $1.7B |
| 2025 | $1.3B | $1.5B | $1.8B |
| 2026 | $1.3B | $1.6B | $1.8B |
| 2027 | $1.3B | $1.6B | $1.9B |
| 2028 | $1.3B | $1.7B | $2.0B |
| 2029 | $1.3B | $1.7B | $2.1B |
| 2024-2029 CAGR | 0% | 2.6% | 4.3% |
Base-case assumptions
The base case assumes:
- Global prescription volume grows 4% to 6% annually.
- Average realized price declines 2% to 4% annually.
- Fixed-dose combinations grow faster than standalone tablets.
- US value remains flat or declines modestly.
- Emerging-market unit growth offsets mature-market price erosion.
- No major safety signal changes the treatment position of ezetimibe.
- PCSK9 and inclisiran uptake increases but does not displace low-cost oral therapy in most patients.
The bull case requires stronger diagnosis and treatment of hypercholesterolemia, increased use in combination therapy, and successful expansion of ezetimibe/bempedoic-acid products. The bear case reflects deeper generic price erosion, more aggressive statin use, and rapid migration of high-risk patients to injectable therapies.
When did ezetimibe lose US market exclusivity?
Ezetimibe lost practical US exclusivity in the 2016-2017 period. The original compound patent, U.S. Patent No. 5,846,966, was assigned to Schering Corporation and covered ezetimibe-related compounds. Its effective patent protection extended beyond the ordinary 20-year term through patent-term adjustment and regulatory exclusivity considerations. The Orange Book historically listed the patent against Zetia and Vytorin. [5]
| Asset | Original sponsor | Key US exclusivity event | Current status |
|---|---|---|---|
| Zetia, ezetimibe tablets | Merck/Schering-Plough | Generic entry in 2016-2017 | Genericized |
| Vytorin, ezetimibe/simvastatin | Merck/Schering-Plough | Generic competition beginning in the late 2010s | Genericized |
| Zetia compound patent | Schering Corporation | Effective protection ended in the 2016-2017 period | Expired |
| Ezetimibe method-of-use protection | Multiple historic listings | Limited remaining practical value after generic entry | Mature/expired or nonblocking |
Because the core product is genericized, current commercial protection depends primarily on manufacturing scale, supplier reliability, regulatory approvals, formulation patents, and distribution contracts.
What is the FDA and Orange Book status of ezetimibe?
Ezetimibe remains FDA-approved and widely available through abbreviated new drug applications. The FDA Orange Book lists reference products and approved generic equivalents, including ezetimibe tablets and certain combination products. [5]
The regulatory profile is favorable:
- Prescription drug status
- Oral tablet administration
- No biologic-license pathway
- No biosimilar pathway
- Multiple ANDA-approved generic manufacturers
- Established clinical and safety record
- Limited clinical differentiation among standard generic tablets
The principal regulatory barriers for a new entrant are bioequivalence, chemistry-manufacturing-controls documentation, facility compliance, supply-chain qualification, and approval of any new fixed-dose combination.
Are there Paragraph IV challenges involving ezetimibe?
The principal Paragraph IV activity occurred before or around generic launch, when manufacturers challenged Orange Book-listed patents covering Zetia and Vytorin. Once the core patents expired and multiple generic products entered, Paragraph IV litigation ceased to be a meaningful market barrier for standalone ezetimibe.
Current litigation risk is more relevant to:
- New fixed-dose combinations
- Reformulated tablets
- Modified-release or specialty dosage forms
- Manufacturing-process patents
- Combination products containing ezetimibe and bempedoic acid
- Patent disputes involving formulation, crystalline form, or process claims
A generic manufacturer entering the standard 10 mg tablet market faces commercial competition more than patent risk.
What formulations and combinations are protected by patents?
Standalone ezetimibe tablets have limited remaining exclusivity value. Commercially relevant formulation opportunities include fixed-dose combinations and differentiated delivery systems.
Ezetimibe/bempedoic acid
The combination of ezetimibe and bempedoic acid is marketed in the United States as Nexlizet. Esperion Therapeutics developed bempedoic-acid products and retained patents relating to bempedoic acid, combinations, and associated formulations. [6]
This combination has a stronger commercial and patent position than generic ezetimibe alone because:
- It targets patients requiring additional LDL reduction.
- It combines two oral nonstatin mechanisms.
- It may be useful in statin-intolerant patients.
- Combination and formulation patents can extend protection beyond the original ezetimibe compound patent.
The commercial opportunity is smaller than the total ezetimibe market but has higher revenue per treated patient.
Ezetimibe/statin combinations
Ezetimibe/simvastatin and newer ezetimibe/atorvastatin or ezetimibe/rosuvastatin products are subject to country-specific patent and regulatory positions. Most older combinations are genericized. Newer combination products may retain limited formulation or method-of-use protection, but patent strength depends on claim scope and jurisdiction.
How strong is the ezetimibe patent estate?
The patent estate for standalone ezetimibe is weak from an exclusivity perspective because the foundational protection has expired and generic entry is established. The estate for combinations is stronger but fragmented.
| Patent category | Standalone ezetimibe | Combination products |
|---|---|---|
| Core compound patent | Expired | Usually not applicable |
| Composition-of-matter protection | No meaningful current barrier | Depends on partner molecule |
| Formulation patents | Limited commercial relevance | Potentially meaningful |
| Method-of-use patents | Narrow and difficult to enforce against generics | More relevant in selected indications |
| Manufacturing patents | Possible but generally avoidable | Can create supply-chain friction |
| Regulatory exclusivity | Expired | Depends on product and approval date |
| Generic substitution risk | Very high | Moderate to high |
Patent strength should therefore be assessed at the product level, not by the ezetimibe molecule alone.
Which companies compete in the ezetimibe market?
The competitive market includes originator-linked companies, generic pharmaceutical manufacturers, and combination-product developers.
Originator and branded companies
- Organon, which markets legacy Merck products in several markets
- Merck, through historical Zetia and Vytorin development and commercialization
- Esperion Therapeutics, through Nexlizet and related bempedoic-acid products
- Daiichi Sankyo and regional partners for selected lipid-lowering combinations and markets
Generic manufacturers
Generic competition varies by country but can include:
- Teva Pharmaceuticals
- Viatris
- Sandoz
- Sun Pharmaceutical
- Dr. Reddy's Laboratories
- Zydus Lifesciences
- Lupin
- Cipla
- Torrent Pharmaceuticals
- Apotex
- Hikma Pharmaceuticals
Manufacturers with vertically integrated active-pharmaceutical-ingredient production, reliable FDA-compliant facilities, and strong payer or tender relationships have the best prospects. Tablet manufacturing itself is not technically difficult, so scale and supply reliability are more important than formulation complexity.
What generic entry scenarios exist for ezetimibe?
United States
The US market is already genericized. The likely scenario is continued price compression, with volume growth concentrated in Medicare, Medicaid, commercial formularies, and mail-order channels. A new standard-tablet entrant would need low manufacturing cost or a differentiated supply strategy.
Europe
European markets are heavily influenced by national reimbursement systems and reference pricing. Ezetimibe has broad access, but prices vary considerably between countries. Combination products may retain higher value than standalone tablets where guidelines or reimbursement favor adherence.
China and other emerging markets
China offers volume growth through hospital procurement, national reimbursement, and increasing cardiovascular screening. However, centralized procurement can produce severe price reductions. Market access depends on local registration, tender participation, and supply commitments.
Specialty and combination products
The strongest launch scenario is a differentiated combination, especially one pairing ezetimibe with another oral nonstatin agent. The opportunity depends on clinical positioning, reimbursement, and patent protection rather than the ezetimibe ingredient.
What patent litigation and settlement issues affect ezetimibe?
Historical litigation centered on ANDA challenges to patents covering Zetia and Vytorin. Those disputes supported generic launch timing but do not create a material current barrier for standard ezetimibe tablets.
Current litigation exposure is more likely to involve:
- Combination patents
- Paragraph IV challenges against newer products
- Patent-term or listing disputes
- Manufacturing-process patents
- Hatch-Waxman litigation involving bempedoic-acid combinations
Settlement agreements involving older standalone ezetimibe products have limited present commercial importance because the market has already transitioned to generic supply.
How does ezetimibe compare with competing LDL-lowering drugs?
| Product class | Typical LDL reduction | Administration | Cost position | Competitive effect |
|---|---|---|---|---|
| High-intensity statins | 50% or more | Oral daily | Lowest | Primary therapy |
| Ezetimibe | 18%-25% alone; higher with statin | Oral daily | Low | Major add-on therapy |
| Bempedoic acid | Approximately 15%-25% | Oral daily | Moderate | Alternative for statin intolerance |
| PCSK9 monoclonal antibodies | Approximately 50%-60% | Injection | High | High-risk patients |
| Inclisiran | Approximately 50% | Infrequent injection | High | Emerging specialty competitor |
| Bile-acid sequestrants | Variable | Oral | Moderate | Limited by tolerability |
Ezetimibe is unlikely to lose its low-cost role even as injectable therapies expand. The primary substitution risk is in very-high-risk patients, not in the broad population receiving inexpensive oral LDL reduction.
What are the commercial risks and revenue opportunities?
Revenue risks
- Generic price erosion
- Payer consolidation and tender pricing
- Substitution by high-intensity statins
- Greater use of PCSK9 therapies in specialty populations
- Limited differentiation among 10 mg tablet suppliers
- Manufacturing interruptions and API concentration
Revenue opportunities
- Fixed-dose combinations
- Emerging-market expansion
- Hospital and government tenders
- Private-label and contract manufacturing
- Ezetimibe/bempedoic-acid combinations
- Adherence-focused combination products
- Distribution in statin-intolerant populations
For investors and licensees, standalone ezetimibe is primarily a volume and supply-chain business. Higher-margin opportunities require a combination product, differentiated formulation, or protected regional market.
Key Takeaways
- Global ezetimibe product sales are estimated at $1.3 billion to $1.7 billion in 2024.
- Base-case global sales reach approximately $1.7 billion by 2029.
- Unit demand should grow, but generic price erosion limits revenue growth.
- US and European markets are mature and heavily genericized.
- Asia-Pacific and other emerging markets offer the strongest volume growth.
- The core ezetimibe patent estate is expired and does not provide meaningful standalone exclusivity.
- Formulation and combination patents remain more commercially relevant than compound patents.
- Ezetimibe has no biosimilar risk because it is a small-molecule drug.
- Generic entry risk is already realized for standard 10 mg tablets.
- The strongest commercial opportunity is in fixed-dose combinations, especially ezetimibe/bempedoic acid.
- Ezetimibe remains strategically important because it provides inexpensive oral LDL reduction before or alongside higher-cost injectable therapies.
FAQs
What is the expected ezetimibe market size in 2030?
A reasonable base-case estimate is approximately $1.7 billion to $2.0 billion globally in 2030, assuming low-single-digit volume growth and continuing generic price erosion.
Is Zetia still commercially protected?
No. Zetia's core US exclusivity ended in the 2016-2017 period, and generic ezetimibe is widely available. Any remaining value is primarily brand, distribution, or regional rather than compound-patent based.
Can a company still patent a new ezetimibe product?
Yes. A company may obtain patents for a novel fixed-dose combination, formulation, manufacturing process, crystalline form, or clinically defined use. A new patent would not restore exclusivity to the basic ezetimibe molecule.
Is Nexlizet a generic competitor to ezetimibe?
Nexlizet is not a direct generic equivalent to ezetimibe alone. It combines bempedoic acid with ezetimibe and competes as a higher-value oral nonstatin product for patients needing additional LDL reduction or unable to tolerate statins.
Does ezetimibe face biosimilar competition?
No. Ezetimibe is a chemically synthesized small molecule regulated through the generic-drug pathway. Competition comes from generic equivalents and combination products, not biosimilars.
References
- U.S. Food and Drug Administration. (2024). Zetia (ezetimibe) prescribing information.
- Grundy, S. M., Stone, N. J., Bailey, A. L., et al. (2019). 2018 AHA/ACC/AACVPR/AAPA/ABC/ACPM/ADA/AGS/APhA/ASPC/NLA/PCNA guideline on the management of blood cholesterol. Circulation, 139(25), e1082-e1143.
- Lloyd-Jones, D. M., Morris, P. B., Ballantyne, C. M., et al. (2022). 2022 ACC expert consensus decision pathway on the role of nonstatin therapies for LDL-cholesterol lowering. Journal of the American College of Cardiology, 80(14), 1366-1418.
- World Health Organization. (2023). Cardiovascular diseases fact sheet.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- Esperion Therapeutics, Inc. (2024). Annual report and product information for Nexletol and Nexlizet.
More… ↓
