Share This Page
Drug Sales Trends for TRUVADA
✉ Email this page to a colleague
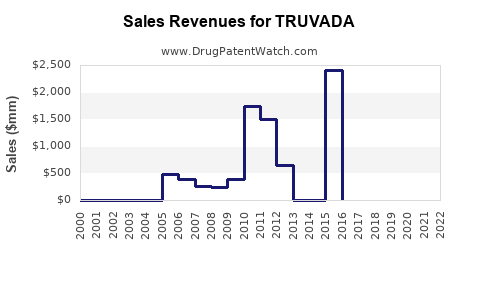
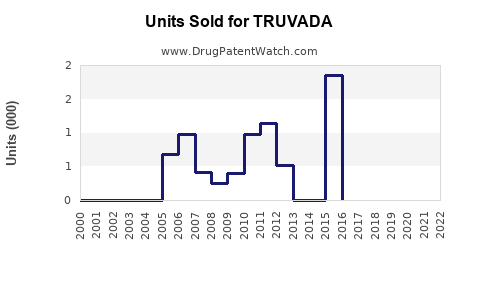
Annual Sales Revenues and Units Sold for TRUVADA
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| TRUVADA | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| TRUVADA | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| TRUVADA | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| TRUVADA | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| TRUVADA | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Truvada Market Analysis and Sales Projections: Patents, Generics, PrEP Demand, and Commercial Outlook
Truvada has transitioned from a premium HIV treatment product into a mature, largely generic medicine. Gilead Sciences’ branded revenue has fallen sharply since generic entry, while demand remains substantial in HIV pre-exposure prophylaxis, or PrEP, and combination antiretroviral therapy. The commercial outlook depends on generic pricing, PrEP diagnosis and testing volumes, public-health procurement, and migration to newer products such as Descovy and long-acting injectable therapies.
Base-case estimates indicate that global Truvada-equivalent sales will remain commercially significant through 2028, but most revenue will accrue to generic manufacturers rather than Gilead. U.S. branded Truvada revenue is expected to remain below $200 million annually, while the broader global TDF/FTC market could remain in the $1.0 billion to $1.5 billion range in 2028.
What is Truvada and how is it used?
Truvada is a fixed-dose combination of tenofovir disoproxil fumarate, or TDF, and emtricitabine, or FTC. Each tablet contains 300 mg of TDF and 200 mg of FTC.
The product has two principal uses:
- Treatment of HIV-1 infection in combination with other antiretroviral agents.
- HIV PrEP for adults and adolescents weighing at least 35 kilograms who are HIV-negative and at risk of infection.
The FDA approved Truvada for HIV treatment in 2004 and expanded its label to PrEP in 2012. The PrEP approval made Truvada a major prevention product and created a second commercial market beyond HIV treatment (U.S. Food and Drug Administration [FDA], 2012).
Truvada is administered once daily. Generic versions have the same active ingredients, strengths, dosage form, and principal approved uses as the reference product.
How large is the Truvada market?
The relevant market is broader than branded Truvada. It includes:
- Branded Truvada sold by Gilead.
- U.S. and international generic TDF/FTC.
- Public-health and donor-funded procurement.
- Combination HIV products that compete with TDF/FTC.
- Newer PrEP products, particularly Descovy and long-acting cabotegravir.
Historical branded sales
Gilead does not always report Truvada revenue as a separately identifiable line item in current filings. Historical sales disclosures and company filings show a steep decline after generic entry and the migration of HIV patients to newer Gilead products.
| Period | Commercial development | Revenue effect |
|---|---|---|
| 2004-2011 | Truvada established in HIV treatment | Rapid branded growth |
| 2012-2016 | FDA PrEP approval expanded the addressable market | Higher demand and greater medical visibility |
| 2017-2019 | Descovy and other newer regimens gained share | Gradual treatment erosion |
| 2020 | U.S. generic entry began under settlement arrangements | Sharp branded revenue decline |
| 2021-2024 | Generic substitution accelerated; PrEP demand remained | Branded product became a niche product |
| 2025-2028 | Mature generic market with continuing prevention demand | Volume stable, prices under pressure |
Gilead’s HIV franchise remains large, but growth is concentrated in Biktarvy, Descovy, and newer products rather than Truvada. Gilead reported total product sales of approximately $27 billion in 2023, with HIV products representing the company’s largest therapeutic franchise (Gilead Sciences, 2024).
What are the Truvada sales projections through 2028?
The following projections cover global sales of Truvada and generic TDF/FTC equivalents. They are market-model estimates rather than company guidance.
| Year | Low case | Base case | High case |
|---|---|---|---|
| 2023 estimated global TDF/FTC market | $1.25 billion | $1.45 billion | $1.65 billion |
| 2024 | $1.18 billion | $1.38 billion | $1.62 billion |
| 2025 | $1.10 billion | $1.32 billion | $1.60 billion |
| 2026 | $1.02 billion | $1.27 billion | $1.58 billion |
| 2027 | $0.95 billion | $1.22 billion | $1.55 billion |
| 2028 | $0.88 billion | $1.18 billion | $1.52 billion |
The base case assumes:
- Annual unit demand grows by 2% to 4%, driven by PrEP expansion and HIV treatment in lower-income markets.
- Average selling prices decline by 5% to 8% annually in competitive generic markets.
- U.S. demand remains stable or increases modestly, but generic substitution keeps revenue low.
- Descovy and injectable PrEP capture a portion of higher-income-market demand.
- TDF/FTC retains a large role in public-health programs because of cost and manufacturing scale.
Under the base case, the global market contracts at approximately 3% to 5% annually in value while remaining comparatively stable in treatment and prevention volume.
U.S. branded Truvada projection
| Year | Estimated U.S. branded revenue |
|---|---|
| 2024 | $100 million-$175 million |
| 2025 | $90 million-$150 million |
| 2026 | $80 million-$140 million |
| 2027 | $70 million-$130 million |
| 2028 | $60 million-$120 million |
The range reflects uncertainty in channel mix, contracting, remaining branded prescriptions, and whether Gilead maintains a material branded presence in specific commercial and government channels.
When did Truvada lose market exclusivity?
Truvada lost effective U.S. commercial exclusivity when generic versions entered the market in 2020. Gilead reached agreements with generic manufacturers that permitted earlier entry than the full expiration of certain patent rights.
Teva announced U.S. availability of an authorized generic version of Truvada in 2020. Other generic manufacturers subsequently competed in the market. The practical result was a rapid reduction in branded pricing power and prescription share.
The key commercial date is therefore 2020, not the later nominal expiration of every patent listed against the product. Patent settlements can establish an authorized launch date before the latest patent expiration date.
What patents protect Truvada?
Truvada’s patent estate was based principally on patents covering tenofovir prodrugs, emtricitabine, combinations, and related pharmaceutical compositions. The most commercially relevant U.S. patents included the following families:
| Patent family or patent | Subject matter | Commercial relevance |
|---|---|---|
| U.S. Patent No. 5,952,375 | Tenofovir prodrug and related compounds | Core TDF protection |
| U.S. Patent No. 6,642,245 | Emtricitabine-related protection | FTC component protection |
| Combination and formulation claims | TDF/FTC compositions and pharmaceutical use | Supported Orange Book and litigation positions |
| Method-of-use claims | HIV treatment and prevention uses | Relevant to PrEP and label carve-outs |
Patent scope and expiration dates varied by jurisdiction, patent-term adjustment, pediatric extensions, and settlement agreements. The commercial impact of the estate declined materially once generic manufacturers received permission to launch.
What is the Orange Book status of Truvada?
Truvada was approved under NDA 021752 and was listed in the FDA Orange Book as a prescription fixed-dose combination product. Orange Book listings historically included patents covering the active ingredients, compositions, and uses.
After generic entry, the Orange Book remained relevant for:
- Abbreviated New Drug Application certifications.
- Paragraph IV patent challenges.
- Labeling and skinny-label strategies.
- Patent litigation and settlement terms.
- Determination of the reference product’s remaining listed protections.
An Orange Book listing does not by itself prevent generic approval. The relevant barrier depends on the patent type, expiration date, certification, litigation, and any regulatory exclusivity.
Which companies challenged Truvada patents?
Generic manufacturers, including Teva and other firms, challenged or negotiated around Truvada-related patents. The main competitive pathway was an ANDA filing with a Paragraph IV certification or a settlement permitting an agreed entry date.
A Paragraph IV certification states that a listed patent is invalid, unenforceable, or will not be infringed by the proposed generic. The filing can trigger patent litigation under the Hatch-Waxman Act. A timely patent lawsuit can create a 30-month stay of FDA approval, subject to statutory exceptions and court developments.
The key commercial result was authorized and licensed generic entry in 2020 rather than a prolonged period of branded exclusivity through the latest possible patent date.
What patent litigation affected Truvada?
Truvada was involved in U.S. patent disputes concerning the validity, enforceability, and scope of Gilead’s TDF/FTC patents. The most important litigation concerned patents associated with HIV treatment and PrEP use.
Gilead also litigated related TDF/FTC patents against the U.S. government. In 2019, the U.S. Department of Health and Human Services sued Gilead, alleging infringement of government-owned patents relating to the use of Truvada and Descovy for PrEP. Gilead disputed the government’s allegations. The dispute remained separate from the generic-entry settlements and concerned patent ownership and infringement rather than FDA approval of Truvada itself (U.S. Department of Health and Human Services, 2019).
The government litigation created legal exposure for Gilead but did not restore branded exclusivity or materially change the generic market structure.
What formulations are protected by Truvada patents?
The principal protected formulation was an oral, immediate-release, fixed-dose tablet containing:
- TDF 300 mg.
- FTC 200 mg.
The commercial value of formulation protection was limited after generic manufacturers developed bioequivalent tablets. Generic applicants generally did not need to reproduce every aspect of Gilead’s manufacturing process. They needed to demonstrate pharmaceutical equivalence and bioequivalence under the ANDA pathway.
Potentially relevant formulation and manufacturing barriers include:
- Control of TDF and FTC particle properties.
- Tablet compression and dissolution performance.
- Stability and impurity specifications.
- High-volume active pharmaceutical ingredient manufacturing.
- Regulatory validation of combination-tablet processes.
These barriers are manageable for established generic manufacturers and do not create a durable barrier comparable to biologic manufacturing complexity.
Does Truvada face biosimilar risk?
No. Truvada is a small-molecule chemical drug, not a biologic. It does not face biosimilar competition under the Public Health Service Act.
Its competitive risk is generic substitution under the Hatch-Waxman Act. Generic manufacturers can rely on the reference product’s FDA safety and efficacy findings while proving bioequivalence.
The relevant competitive threats are:
- Generic TDF/FTC.
- Descovy for PrEP and HIV treatment.
- Apretude, long-acting cabotegravir for PrEP.
- Biktarvy and other single-tablet HIV regimens.
- Alternative TDF- or TAF-based combinations.
How does Truvada compare with Descovy and Apretude?
| Product | Active ingredient or technology | Main commercial advantage | Main limitation |
|---|---|---|---|
| Truvada | TDF/FTC | Low cost, broad treatment and PrEP experience | Renal and bone safety considerations; generic price erosion |
| Descovy | TAF/FTC | Improved renal and bone profile in relevant populations | Higher cost; not approved for receptive vaginal sex at initial label scope |
| Apretude | Long-acting cabotegravir injection | Dosing every two months after initiation | Injection logistics, clinic capacity, adherence to appointments |
| Biktarvy | Bictegravir/FTC/TAF | Strong treatment efficacy and single-tablet convenience | Not a PrEP product |
| Generic TDF/FTC | TDF/FTC | Lowest price and broad access | Lower branded margins and older safety profile |
Descovy is the principal branded PrEP competitor within Gilead’s portfolio. Apretude represents the most important non-oral PrEP competitor because it changes the dosing model rather than simply replacing one oral tablet with another (ViiV Healthcare, 2024).
Truvada retains an advantage in cost-sensitive markets and remains eligible for broad generic procurement. Apretude and Descovy are more likely to compete for commercially insured patients, higher-income markets, and patients with specific tolerability or adherence needs.
What licensing deals affect the Truvada market?
Gilead entered voluntary licensing and access arrangements for certain HIV medicines, including TDF- and FTC-based products, to expand generic supply in lower-income and high-burden countries. The Medicines Patent Pool has supported licensing structures for HIV medicines and broader generic access (Medicines Patent Pool, 2024).
These arrangements increase market volume but reduce average revenue per patient. They also limit the ability of patent holders to maintain premium pricing in licensed territories.
Commercially, the market is divided into:
- Premium branded markets in the United States, Western Europe, Japan, and selected other countries.
- Regulated generic markets with multiple suppliers.
- Donor-funded and public procurement markets.
- Voluntary-license territories with lower prices and larger patient volumes.
What generic launch scenarios exist for Truvada?
Low-price rapid substitution
Multiple suppliers enter, payers mandate generic substitution, and branded Truvada becomes a limited-access product. This scenario produces the fastest revenue decline and the lowest average selling price.
Moderate generic competition
Two to four major suppliers compete, but public-health contracts and supply requirements support stable volumes. Revenue declines gradually while demand remains high.
Supply-constrained generic market
Manufacturing disruptions or limited supplier participation produce temporary pricing increases. This scenario can improve generic revenue but does not materially restore Gilead’s branded position.
The base case is moderate competition with periodic price pressure and stable demand.
How strong is the Truvada patent estate?
The patent estate was commercially strong before generic entry and weak as a current revenue defense.
| Factor | Assessment |
|---|---|
| Composition-of-matter protection | Historically strong |
| Remaining U.S. exclusivity | Limited after 2020 entry |
| Formulation protection | Vulnerable to bioequivalent generic development |
| Method-of-use protection | Legally important but difficult to monetize after entry |
| Manufacturing complexity | Moderate, not biologic-level |
| Generic substitution risk | High |
| Current branded pricing power | Low |
| International protection | Uneven and territory-specific |
Truvada’s strongest defenses were the core TDF and FTC patent families before generic settlement dates. Its current value lies mainly in regulatory approval, physician familiarity, procurement acceptance, and global demand rather than enforceable exclusivity.
What is the FDA regulatory status of Truvada?
Truvada is FDA-approved for HIV-1 treatment in combination with other antiretroviral agents and for HIV PrEP in individuals at risk of acquiring HIV. Generic versions are approved through the ANDA process based on pharmaceutical equivalence and bioequivalence.
PrEP use requires ongoing HIV testing and clinical monitoring. Product selection depends on patient risk profile, renal function, bone considerations, exposure type, adherence, and payer coverage.
The FDA approval of Apretude and the continued availability of Descovy have expanded the competitive PrEP market, but neither product has eliminated the role of generic TDF/FTC.
What is the revenue exposure for Gilead?
Truvada is no longer a material growth driver for Gilead. Its strategic exposure is indirect:
- Generic erosion reduces legacy HIV revenue.
- Truvada establishes a low-cost benchmark for PrEP.
- Descovy must defend share against generic TDF/FTC.
- Newer products must justify premium pricing through tolerability, convenience, or clinical differentiation.
- Public-health policy can expand PrEP use while shifting revenue toward low-cost suppliers.
Gilead’s current HIV growth thesis depends on Biktarvy, Descovy, lenacapavir development, and other next-generation therapies rather than a recovery in branded Truvada sales.
Key Takeaways
- Truvada is a mature TDF/FTC product with substantial generic demand and limited branded pricing power.
- U.S. generic entry began in 2020 and permanently changed the revenue profile.
- Global TDF/FTC market value is projected to decline modestly through 2028, while patient volume remains resilient.
- The base-case global market estimate is approximately $1.18 billion in 2028.
- Generic manufacturers, public-health programs, and licensed suppliers will capture most future volume.
- Descovy and Apretude are the principal branded and technological competitors.
- Truvada has no biosimilar risk because it is a small-molecule drug.
- Current patent strength is materially lower than historical patent strength.
- Gilead’s future HIV revenue depends on newer products, not branded Truvada growth.
FAQs
Is Truvada still profitable for Gilead?
Yes, but its profitability is substantially lower than before generic entry. The product retains residual branded demand, but generic competition has reduced revenue and pricing power.
Is generic Truvada as effective as branded Truvada?
FDA-approved generic TDF/FTC products must demonstrate bioequivalence to the reference product. They contain the same active ingredients and strengths.
Can generic Truvada be used for PrEP?
Yes. FDA-approved generic TDF/FTC products can be used for approved PrEP indications, subject to prescribing information and required HIV testing.
Will Truvada be replaced by long-acting PrEP?
Long-acting cabotegravir will capture some patients, but cost, clinic access, injection logistics, and global procurement needs support continued TDF/FTC use.
What is the biggest commercial risk to Truvada sales?
The largest risk is continued generic price erosion combined with migration to newer branded HIV and PrEP products. Volume may remain stable while revenue declines.
References
Gilead Sciences, Inc. (2024). 2023 annual report. Gilead Sciences.
Medicines Patent Pool. (2024). Licensing and access programs for HIV medicines. Medicines Patent Pool.
U.S. Department of Health and Human Services. (2019). United States v. Gilead Sciences, Inc.: Complaint regarding HIV pre-exposure prophylaxis patents. U.S. Department of Justice.
U.S. Food and Drug Administration. (2012). FDA approves first drug for reducing the risk of sexually acquired HIV infection. FDA.
U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. FDA.
ViiV Healthcare. (2024). Apretude prescribing information. ViiV Healthcare.
More… ↓
