Share This Page
Drug Sales Trends for ROSUVASTATIN CALCIUM
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for ROSUVASTATIN CALCIUM (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
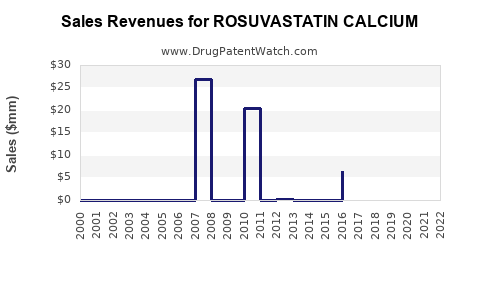
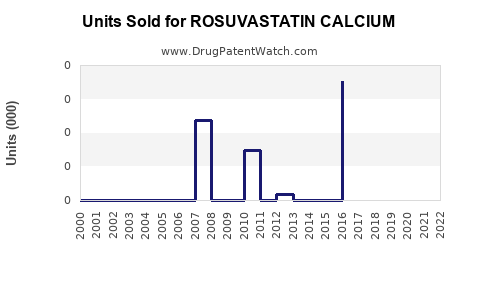
Annual Sales Revenues and Units Sold for ROSUVASTATIN CALCIUM
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| ROSUVASTATIN CALCIUM | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| ROSUVASTATIN CALCIUM | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| ROSUVASTATIN CALCIUM | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| ROSUVASTATIN CALCIUM | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Rosuvastatin Calcium Market Analysis, Patent Status, Competitive Landscape and Sales Projections
Rosuvastatin calcium is a mature, high-volume generic statin with durable demand, broad global access and limited brand pricing power. The commercial market is driven by cardiovascular disease prevalence, generic substitution, guideline-based LDL reduction and expanded primary-prevention use. Global molecule-level sales are estimated at approximately $2.0 billion to $2.5 billion in 2024, with a base-case market value of $2.5 billion to $3.0 billion by 2030. Growth is likely to come from prescription volume rather than price increases.
What is the current market size for rosuvastatin calcium?
Rosuvastatin calcium is the calcium salt of rosuvastatin, a synthetic HMG-CoA reductase inhibitor marketed originally as Crestor by AstraZeneca. It is available primarily as immediate-release oral tablets in 5 mg, 10 mg, 20 mg and 40 mg strengths.
Public market estimates differ because some reports count only branded and generic retail sales, while others include hospital procurement, combination products or active-pharmaceutical-ingredient revenue. A practical 2024 estimate is:
| Market segment | Estimated 2024 value | Commercial condition |
|---|---|---|
| United States generic and authorized-generic sales | $0.6B-$0.9B | High volume, low unit prices |
| Europe | $0.4B-$0.6B | Mature generic market with price controls |
| China and broader Asia-Pacific | $0.5B-$0.7B | Volume growth and expanding diagnosis |
| Latin America, Middle East and Africa | $0.2B-$0.3B | Lower pricing but rising access |
| Global total | $1.7B-$2.5B | Molecule-level estimate |
The estimate excludes unrelated statins and generally excludes fixed-dose combinations unless rosuvastatin sales are separately identifiable.
Rosuvastatin remains commercially relevant because it delivers high-intensity LDL reduction at relatively low daily doses. The American College of Cardiology and American Heart Association classify 20 mg and 40 mg doses as high-intensity statin therapy, subject to patient-specific treatment decisions (Grundy et al., 2019).
How much will rosuvastatin calcium sales grow through 2030?
The base-case forecast assumes low-single-digit annual growth in global revenue, supported by prescription expansion but constrained by generic price erosion.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | $1.7B | $2.1B | $2.5B |
| 2025 | $1.7B | $2.2B | $2.7B |
| 2026 | $1.8B | $2.3B | $2.8B |
| 2027 | $1.8B | $2.4B | $3.0B |
| 2028 | $1.9B | $2.5B | $3.2B |
| 2029 | $1.9B | $2.6B | $3.4B |
| 2030 | $2.0B | $2.7B | $3.6B |
| 2024-2030 CAGR | 2.8% | 4.1% | 6.3% |
The base case assumes:
- Global prescription volume growth of 4% to 6% annually.
- Average selling price declines of 1% to 3% annually.
- Greater use in high-risk primary prevention and diabetes care.
- Continued generic substitution.
- No major safety-related withdrawal or guideline reversal.
- Stable availability of key active pharmaceutical ingredients.
The bull case requires faster diagnosis of dyslipidemia in emerging markets and increased adherence to guideline-recommended statin therapy. The bear case reflects aggressive tender pricing, reimbursement restrictions and substitution toward atorvastatin or low-cost statin combinations.
What drives demand for rosuvastatin calcium?
Cardiovascular disease prevalence
Cardiovascular disease remains the largest source of global mortality, supporting long-term demand for lipid-lowering therapy. The World Health Organization estimates that cardiovascular disease causes about 17.9 million deaths annually, creating a large treatment population for statins and other LDL-lowering drugs (World Health Organization, 2023).
High-intensity statin use
Rosuvastatin 20 mg and 40 mg are widely used when substantial LDL reduction is required. Rosuvastatin is also selected when patients need a potent statin at a lower tablet dose or when clinicians seek an alternative to atorvastatin.
Generic affordability
The U.S. Food and Drug Administration approved the first generic rosuvastatin products in 2016. Generic entry materially reduced prices and expanded payer access. That dynamic increases unit demand but compresses manufacturer revenue.
Expansion in emerging markets
China, India, Southeast Asia and Latin America offer the strongest volume opportunity. Growth depends on reimbursement, local clinical practice, diagnosis rates and the availability of low-cost domestic products.
How does rosuvastatin compare with atorvastatin and other statins?
| Drug | Generic status | Relative LDL-lowering potency | Main commercial position |
|---|---|---|---|
| Rosuvastatin | Broadly generic | High | Premium generic potency and high-intensity use |
| Atorvastatin | Broadly generic | High | Largest and most price-competitive high-intensity statin |
| Simvastatin | Broadly generic | Moderate | Older, lower-cost therapy |
| Pravastatin | Broadly generic | Low to moderate | Tolerability and interaction-sensitive use |
| Pitavastatin | Generic in selected markets | Moderate to high | Smaller specialty and tolerability segment |
Atorvastatin is the principal competitive threat. It has broad dose availability, extensive physician familiarity and aggressive generic pricing. Rosuvastatin retains an advantage in potency and lower-dose high-intensity therapy. Simvastatin and pravastatin compete mainly on cost and prescribing familiarity.
PCSK9 inhibitors, inclisiran and bempedoic acid compete for patients who do not reach LDL targets with statins or cannot tolerate adequate statin doses. These products do not replace most generic rosuvastatin prescriptions because their prices and treatment positioning are materially different.
What patents protect rosuvastatin calcium?
The core U.S. patents covering Crestor and rosuvastatin calcium have expired. The principal composition patent was U.S. Patent No. 6,316,023, assigned to AstraZeneca, with patent protection extending into January 2023 after applicable adjustments and extensions. The FDA Orange Book should be used for the operative listing and any applicable pediatric exclusivity or patent-term adjustments (FDA, 2024a).
| IP category | Historical protection | Current commercial effect |
|---|---|---|
| Rosuvastatin chemical composition | U.S. Patent No. 6,316,023 | Expired |
| Salt and pharmaceutical composition claims | Various historical patents and Orange Book listings | No broad blocking protection |
| Tablet formulation | Product-specific or process-related claims | Limited risk after core expiry |
| Method-of-use claims | Cholesterol reduction and cardiovascular-risk treatment | Generally difficult to enforce against routine generic use |
| Manufacturing process | Supplier-specific process patents | May affect particular manufacturers, not the molecule market |
Patent protection now has limited ability to prevent ordinary generic competition. Remaining formulation, process or jurisdiction-specific patents may affect individual suppliers, but they do not recreate the former Crestor monopoly.
When did rosuvastatin lose exclusivity?
Crestor received FDA approval in August 2003. New chemical entity exclusivity generally expired after five years, subject to applicable regulatory extensions. Generic rosuvastatin products entered the U.S. market in 2016 following patent litigation and settlement arrangements involving AstraZeneca and generic manufacturers.
The effective exclusivity timeline was:
| Event | Date or period |
|---|---|
| U.S. Crestor approval | August 2003 |
| Core NCE exclusivity period | Approximately 2003-2008 |
| First major U.S. generic approvals | 2016 |
| Core composition patent expiry | January 2023 |
| Current status | Broadly generic |
The difference between regulatory exclusivity expiry and actual generic launch reflects patent litigation, settlements and commercial launch agreements.
What is the FDA and Orange Book status of rosuvastatin calcium?
Rosuvastatin calcium tablets are approved under abbreviated new drug applications from multiple manufacturers. Generic products rely on an ANDA pathway and must demonstrate pharmaceutical equivalence and bioequivalence to the reference listed drug.
The FDA Orange Book identifies approved drug products, reference listed drugs and relevant patent or exclusivity information. Crestor is no longer protected by an active market-wide patent barrier capable of preventing routine generic substitution (FDA, 2024a; FDA, 2024b).
Rosuvastatin is a small-molecule drug. Biosimilar competition is therefore not applicable. Competitive entry occurs through generic ANDAs, authorized generics, local registrations and tender participation rather than through the biologics license application pathway.
Which companies sell rosuvastatin calcium?
The market is fragmented across multinational generic companies, regional manufacturers and contract suppliers. Major participants may include:
- Viatris and legacy Mylan products.
- Teva Pharmaceutical Industries.
- Sandoz.
- Sun Pharmaceutical Industries.
- Cipla.
- Dr. Reddy's Laboratories.
- Zydus Lifesciences.
- Lupin.
- Torrent Pharmaceuticals.
- Hikma Pharmaceuticals.
- Chinese domestic manufacturers.
- Regional branded-generic companies in Latin America, Europe and Asia.
AstraZeneca remains the originator of Crestor but no longer controls the generic market. Company-level revenue exposure is difficult to isolate because most manufacturers report statins within broader cardiovascular or generic portfolios.
What licensing deals and settlements affected rosuvastatin?
The key commercial transition involved settlements between AstraZeneca and generic applicants that established launch rights before or around the end of the patent term. These agreements reduced uncertainty for generic manufacturers and allowed staged or authorized-generic market entry.
The main economic effect was not a transfer of long-term market control. It was an acceleration of generic access under agreed launch conditions. Settlement terms typically involved launch dates, patent litigation releases and, in some cases, authorized-generic arrangements. Agreement-specific commercial terms are not consistently disclosed in public filings.
What patent litigation affected Crestor?
Crestor faced patent challenges from generic companies seeking approval before expiration of AstraZeneca's listed patents. The litigation centered on the validity, infringement and scope of rosuvastatin composition or formulation claims.
After generic entry in 2016, litigation ceased to be a material barrier to U.S. market access. Current litigation risk is more likely to involve:
- Product-specific ANDA disputes.
- Manufacturing-process claims.
- Trademark and trade-dress issues.
- Formulation patents in individual jurisdictions.
- Regulatory enforcement involving manufacturing quality or product labeling.
A new Paragraph IV challenge against the original Crestor product would have limited commercial significance because generic entry is already established.
What formulation and manufacturing barriers remain?
Rosuvastatin calcium is commercially accessible, but manufacturers still face technical and operational barriers.
Formulation requirements
The main product is an immediate-release film-coated tablet. Development priorities include:
- Maintaining content uniformity at low-dose strengths.
- Controlling degradation and impurity formation.
- Achieving dissolution comparable to the reference product.
- Managing tablet hardness, coating and stability.
- Supporting multiple strengths with efficient manufacturing.
Manufacturing and supply risks
The active ingredient is produced by a global network of API manufacturers. Risks include:
- API price competition and supply concentration.
- Regulatory inspection findings.
- Nitrosamine or other impurity controls where applicable.
- Delays in facility qualification.
- Tender-driven pressure on finished-dose margins.
- Country-specific registration requirements.
These barriers can remove individual suppliers from the market temporarily but are unlikely to restrict global molecule availability.
What generic launch scenarios exist for rosuvastatin calcium?
United States
The U.S. market is fully genericized. Future growth will come from prescription volume, channel expansion and payer coverage rather than new exclusivity. Manufacturer margins are most exposed to pharmacy-benefit-manager contracting, wholesaler fees and purchasing consolidation.
Europe
European markets have high generic penetration and strong price controls. Volume is stable, but revenue is vulnerable to reference pricing and national tender systems. Companies with local manufacturing and reliable supply have an advantage.
China
China has significant volume potential through centralized procurement. Winning tenders can produce large unit volumes but sharp price reductions. Manufacturers with scale and regulatory readiness are better positioned than smaller suppliers.
India
India remains a large branded-generic market. Rosuvastatin can command higher nominal prices than in tender-driven markets, although physician promotion and local competition remain intense.
Latin America
Brazil, Mexico and Argentina offer prescription growth but face currency volatility, reimbursement variation and regulatory complexity. Branded generics can retain market share despite low-cost unbranded products.
How strong is the rosuvastatin calcium patent estate?
The patent estate is commercially weak as a market-exclusion tool because the core patents have expired and generic competition is established. Its current strength is better characterized as follows:
| Dimension | Assessment |
|---|---|
| Core molecule protection | Expired |
| U.S. generic entry barrier | Low |
| Formulation protection | Narrow and supplier-specific |
| Method-of-use protection | Low practical blocking value |
| Manufacturing IP | Potentially relevant to individual suppliers |
| Biosimilar risk | Not applicable |
| Geographic variation | Some local patent and registration differences |
| Overall market protection | Low |
What revenue exposure does rosuvastatin create for manufacturers?
Rosuvastatin is a volume product rather than a high-margin innovation product. Revenue exposure is highest for companies with:
- Large cardiovascular generic portfolios.
- High U.S. pharmacy distribution.
- China centralized-procurement participation.
- Strong branded-generic positions in India and Latin America.
- Integrated API and finished-dose manufacturing.
Revenue risk comes from price compression, supply interruptions and substitution by atorvastatin. Upside comes from increased diagnosis, combination therapy and movement from moderate- to high-intensity statin treatment.
Key Takeaways
- Global rosuvastatin calcium sales are estimated at $1.7 billion to $2.5 billion in 2024.
- A base-case forecast places the market near $2.7 billion by 2030.
- Growth should be volume-led, with generic pricing limiting revenue expansion.
- The core Crestor patent estate has expired, and U.S. generic entry is established.
- Rosuvastatin has no biosimilar risk because it is a small-molecule drug.
- Atorvastatin is the primary competitive substitute.
- China and other emerging markets offer the strongest prescription-volume growth.
- Manufacturing quality, API supply and tender pricing are more important than patent barriers.
- AstraZeneca's historical Crestor franchise has been replaced by a fragmented generic market.
FAQs
Is rosuvastatin calcium still profitable for generic manufacturers?
Yes, but profitability depends on manufacturing scale, procurement access and supply reliability. U.S. and European prices are heavily compressed, while selected branded-generic markets can support higher margins.
Will rosuvastatin calcium sales decline after 2030?
Unit demand may continue growing, but revenue could decline in some markets if price erosion exceeds prescription growth. New LDL-lowering therapies are more likely to supplement than replace generic statin use.
Is Crestor still protected by patents?
The core patents that blocked broad generic entry have expired. Current patent listings should be checked in the FDA Orange Book and relevant national registers for product-specific issues.
Can a generic company launch a new rosuvastatin formulation?
Yes. A company may develop modified-release, combination or alternative dosage forms, but regulatory requirements and any formulation-specific patent claims must be evaluated separately from the established immediate-release tablet market.
Which market has the highest growth potential for rosuvastatin calcium?
China and other Asia-Pacific markets have the highest prescription-volume potential. The United States remains the largest commercially mature market but offers limited price growth.
References
-
AstraZeneca PLC. (2024). Annual report and form 20-F 2023. AstraZeneca.
-
Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations: Orange Book. U.S. Department of Health and Human Services.
-
Food and Drug Administration. (2024b). Drugs@FDA: FDA-approved drugs. U.S. Department of Health and Human Services.
-
Grundy, S. M., Stone, N. J., Bailey, A. L., et al. (2019). 2018 AHA/ACC/AACVPR/AAPA/ABC/ACPM/ADA/AGS/APhA/ASPC/NLA/PCNA guideline on the management of blood cholesterol. Circulation, 139(25), e1082-e1143.
-
World Health Organization. (2023). Cardiovascular diseases. World Health Organization.
-
U.S. Patent No. 6,316,023. (2001). Trans-6-[2-(substituted pyrrol-1-yl)alkyl]-2,2-dimethyl-1,3-dioxane-4-yl]acetic acid. United States Patent and Trademark Office.
More… ↓
