Share This Page
Drug Sales Trends for OXYBUTYNIN CHLORIDE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for OXYBUTYNIN CHLORIDE (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
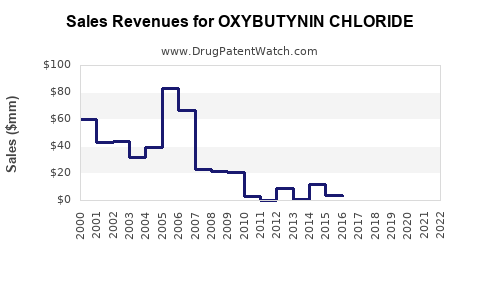
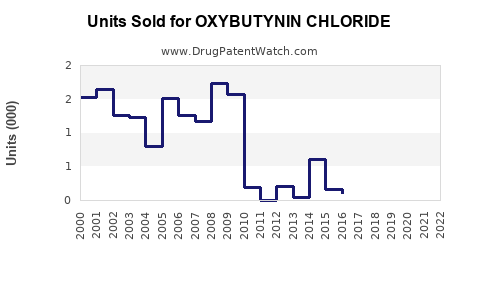
Annual Sales Revenues and Units Sold for OXYBUTYNIN CHLORIDE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| OXYBUTYNIN CHLORIDE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| OXYBUTYNIN CHLORIDE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| OXYBUTYNIN CHLORIDE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| OXYBUTYNIN CHLORIDE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| OXYBUTYNIN CHLORIDE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| OXYBUTYNIN CHLORIDE | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| OXYBUTYNIN CHLORIDE | ⤷ Start Trial | ⤷ Start Trial | 2016 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Oxybutynin Chloride Market Analysis and Sales Projections, 2024-2029
Oxybutynin chloride is a mature, largely generic treatment for overactive bladder, urge urinary incontinence and neurogenic detrusor overactivity. The market is volume-driven, fragmented and price-sensitive. Immediate-release and extended-release tablets account for most prescriptions, while transdermal patches and topical gel occupy smaller, higher-value niches.
Global oxybutynin chloride sales are not separately disclosed by major manufacturers because the product is sold primarily through generic channels. A scenario-based market model places global annual product sales at approximately $400 million to $650 million in 2024, with value declining gradually through 2029 despite stable or modestly increasing prescription volume.
What is the current market size for oxybutynin chloride?
The estimated 2024 global market for oxybutynin chloride products is $400 million to $650 million at manufacturer and channel sales levels. The range includes oral immediate-release tablets, extended-release tablets, transdermal systems and topical formulations.
| Market segment | Estimated 2024 share | Commercial profile |
|---|---|---|
| Immediate-release oral tablets | 45%-55% | Lowest price; high generic penetration |
| Extended-release tablets | 25%-35% | Higher adherence and reimbursement value |
| Transdermal patches | 8%-15% | Smaller volume; differentiated delivery |
| Topical gel and other formulations | 3%-8% | Limited adoption and niche use |
| Institutional and specialty use | 5%-10% | Neurogenic bladder and long-term care demand |
The United States is likely the largest single national market because of its broad generic availability, Medicare coverage and established use in urology and primary care. Europe, Japan and selected Latin American markets contribute significant volume, but pricing is generally lower than in the U.S.
Public financial reporting does not isolate oxybutynin sales for generic manufacturers. The market estimate therefore relies on prescription volume, dosage-form mix, generic pricing and regional reimbursement patterns rather than reported product revenue.
How large is the oxybutynin chloride prescription market?
Oxybutynin remains one of the most widely used antimuscarinic therapies for overactive bladder. Its use has declined in some populations because of anticholinergic adverse effects, particularly dry mouth, constipation, blurred vision and cognitive concerns in older adults.
Demand remains supported by:
- Long clinical history and physician familiarity.
- Low generic acquisition cost.
- Availability in immediate-release and extended-release oral forms.
- Use in pediatric and adult neurogenic bladder.
- Broad pharmacy and hospital distribution.
- Use when newer beta-3 agonists are inaccessible because of price or reimbursement restrictions.
The primary demand constraint is therapeutic substitution. Mirabegron and vibegron offer non-anticholinergic alternatives, while solifenacin, tolterodine, trospium and darifenacin compete within the antimuscarinic class.
U.S. demand drivers
The U.S. market has a large installed base of generic prescriptions. Immediate-release oxybutynin is particularly exposed to low-cost substitution because multiple manufacturers compete on the same dosage strengths.
Extended-release tablets retain more commercial value because they offer once-daily administration and may have better tolerability than immediate-release dosing. Transdermal products reduce gastrointestinal exposure and may be used when oral anticholinergic effects limit adherence.
The U.S. demand profile is divided between:
- Older adults with overactive bladder.
- Adults with urge urinary incontinence.
- Patients with neurogenic detrusor overactivity.
- Pediatric urology patients.
- Long-term-care and institutional populations.
What are the projected oxybutynin chloride sales from 2024 to 2029?
The base-case forecast assumes stable treated prevalence, continued generic price erosion, limited new product investment and gradual substitution toward beta-3 agonists and newer antimuscarinics.
| Year | Global market value, base case | Prescription volume trend | Key market condition |
|---|---|---|---|
| 2024 | $400M-$650M | Baseline | Mature generic market |
| 2025 | $390M-$635M | Stable to +1% | Continued price pressure |
| 2026 | $375M-$620M | Stable | More substitution to newer therapies |
| 2027 | $360M-$605M | -1% to +1% | Oral generic erosion |
| 2028 | $345M-$590M | -1% to +1% | Transdermal and ER products retain value |
| 2029 | $330M-$575M | -2% to 0% | Declining average selling price |
The base case implies a compound annual revenue decline of approximately 2% to 3%. Prescription volume may remain broadly stable because lower prices preserve access, but revenue falls as generic competition reduces average selling prices.
Bull-case scenario
A bull case would produce 2029 sales of approximately $600 million to $750 million. This outcome would require:
- Increased diagnosis and treatment of overactive bladder.
- Greater use in emerging markets.
- Renewed demand for low-cost anticholinergic therapy.
- Delayed switching to beta-3 agonists.
- Supply disruptions affecting competing generic products.
Bear-case scenario
A bear case would reduce 2029 sales to approximately $250 million to $350 million. The main drivers would be:
- Rapid uptake of mirabegron and vibegron.
- Expanded warnings or prescribing restrictions related to anticholinergic burden.
- More aggressive generic price competition.
- Reduced use among older adults.
- Payer preference for alternative antimuscarinics or beta-3 agonists.
How does oxybutynin compare with competing overactive bladder drugs?
Oxybutynin has the lowest unit cost among commonly used overactive bladder medicines but carries a weaker tolerability profile than several alternatives.
| Drug | Class | Generic status | Main commercial advantage | Main limitation |
|---|---|---|---|---|
| Oxybutynin | Antimuscarinic | Widely generic | Low cost and broad availability | Anticholinergic adverse effects |
| Tolterodine | Antimuscarinic | Generic | Established alternative | Generic price pressure |
| Solifenacin | Antimuscarinic | Generic | Once-daily dosing | Higher cost than older generics |
| Trospium | Antimuscarinic | Generic | Lower central nervous system penetration | Dosing and tolerability constraints |
| Mirabegron | Beta-3 agonist | Generic or market-dependent | Non-anticholinergic mechanism | Higher price; blood-pressure considerations |
| Vibegron | Beta-3 agonist | Branded in major markets | Non-anticholinergic profile | Limited price competition in some markets |
Oxybutynin’s main competitive advantage is economic. Its main competitive weakness is tolerability, especially in geriatric populations. The 2023 American Geriatrics Society Beers Criteria identifies oxybutynin as a strong anticholinergic medication of concern in older adults because of its adverse-effect burden [1].
What formulations are protected or commercially differentiated?
Oxybutynin is marketed in several dosage forms:
- Immediate-release tablets.
- Extended-release tablets.
- Transdermal patches.
- Topical gel.
- Oral syrup or solution in some markets.
Immediate-release tablets
Immediate-release oxybutynin is the most commoditized segment. Multiple generic manufacturers can supply common strengths, including 5 mg tablets. Pricing is low, switching costs are minimal and pharmacy substitution is common.
Extended-release tablets
Extended-release products have higher commercial value because once-daily dosing can improve convenience and reduce peak-related adverse effects. The original Ditropan XL intellectual-property estate is no longer a meaningful barrier to generic entry. Generic extended-release products remain subject to formulation and manufacturing requirements, but those requirements do not generally support durable market exclusivity.
Transdermal patches
Transdermal oxybutynin, historically associated with Oxytrol, is differentiated by delivery route. The FDA approved Oxytrol for over-the-counter use in women aged 18 and older with overactive bladder in 2013 [2]. The patch segment has higher unit economics than oral immediate-release tablets but lower volume.
Topical gel
Topical gel formulations seek to provide systemic oxybutynin exposure while avoiding some gastrointestinal effects. Their commercial opportunity is limited by physician familiarity, patient acceptance, application requirements and competition from oral generics.
What is the FDA regulatory status of oxybutynin chloride?
Oxybutynin chloride is an FDA-approved active pharmaceutical ingredient used in prescription oral and transdermal products. The regulatory pathway is mature, with multiple abbreviated new drug applications for generic tablets and extended-release products.
The FDA-approved indications include:
- Relief of symptoms of bladder instability associated with voiding in patients with uninhibited neurogenic or reflex neurogenic bladder.
- Treatment of overactive bladder symptoms, including urge urinary incontinence, urgency and frequency, depending on the dosage form and labeling [3].
Oxytrol became the first overactive bladder treatment approved for nonprescription sale in the United States, although the OTC indication was limited by age and sex requirements [2].
What is the Orange Book status of oxybutynin chloride?
The Orange Book contains reference-listed products and approved generic equivalents for oxybutynin dosage forms. The original innovator exclusivity associated with Ditropan and Ditropan XL has expired. Generic competition is established for immediate-release and extended-release oral products.
The key Orange Book commercial conclusions are:
- No meaningful remaining new-drug exclusivity protects the original oral products.
- Generic approval pathways are available.
- Any remaining listed patents are unlikely to prevent broad generic supply.
- Product-specific formulation patents may affect individual ANDA applicants but do not restore market-wide exclusivity.
- Transdermal products have separate formulation, device and delivery considerations.
Orange Book patent listings should be reviewed at the individual reference-product level before a launch or Paragraph IV filing because listed patents and certifications can change by product and jurisdiction [4].
When did oxybutynin lose exclusivity?
Oxybutynin lost meaningful market exclusivity many years ago. The original oral product has been generic for decades, and extended-release oral competition is also established.
The commercial exclusivity timeline is:
| Milestone | Market effect |
|---|---|
| Original oral approval | Created the initial branded market |
| Introduction of extended-release product | Added once-daily formulation value |
| Expiration of original patents | Opened the market to generic oral products |
| Generic extended-release approvals | Reduced branded pricing power |
| OTC transdermal approval | Created a separate consumer-facing channel |
| Current market | Mature, multi-source generic competition |
There is no broad patent cliff comparable to a recent branded blockbuster. Revenue erosion is gradual and structural rather than concentrated around one upcoming expiration date.
Which companies compete in the oxybutynin chloride market?
Competition is fragmented. Generic manufacturers and contract suppliers may change by country and dosage form. In the United States, oxybutynin products have historically been supplied by companies such as Teva Pharmaceuticals, Sandoz, Mylan or Viatris, Amneal Pharmaceuticals, Lupin, Zydus, Dr. Reddy’s Laboratories, Rising Pharmaceuticals and other ANDA holders.
The branded and specialty history includes:
- Janssen-related commercialization of Ditropan products.
- Merck-related commercialization of Oxytrol before later ownership and commercialization changes.
- Multiple generic suppliers for oral and extended-release products.
Because generic manufacturers generally do not report oxybutynin revenue separately, company-level market shares require commercial prescription or wholesaler datasets.
Are Paragraph IV challenges or oxybutynin patent lawsuits material?
Paragraph IV litigation is not a major current market driver for standard immediate-release oxybutynin. The product has a mature generic base, and the principal litigation risk has shifted from market entry to product-specific issues such as:
- Extended-release release-control technology.
- Transdermal adhesive and delivery systems.
- Manufacturing processes.
- Device design.
- Labeling and inducement theories.
- ANDA formulation equivalence disputes.
No broad, active litigation barrier is expected to restrict ordinary generic oxybutynin supply through the core forecast period. Individual products can still face patent disputes, regulatory deficiencies or supply interruptions.
What generic launch risks exist for oxybutynin?
A new oxybutynin generic would face moderate regulatory risk and high commercial risk.
Regulatory and technical risks
Extended-release products require reliable control of dissolution and drug release. Transdermal products require evidence relating to adhesion, drug delivery, residual drug and patch performance. Topical products require formulation and bioequivalence strategies that may be more complex than standard immediate-release tablets.
Commercial risks
The main launch risks are:
- Excessive price competition.
- Limited pharmacy differentiation.
- Low reimbursement ceilings.
- Wholesaler concentration.
- Established supplier relationships.
- Low switching costs.
- Product recalls caused by manufacturing or dissolution failures.
A conventional immediate-release launch can enter quickly but may generate limited revenue. Extended-release, transdermal and topical products offer better margin potential but require more development capital and carry greater technical execution risk.
What manufacturing and intellectual-property barriers affect the market?
Oxybutynin API production is not generally a strategic barrier. The API is a small-molecule generic ingredient with established manufacturing routes and multiple global suppliers.
The more relevant barriers are dosage-form specific:
| Product type | Main barrier |
|---|---|
| Immediate-release tablet | Cost and scale |
| Extended-release tablet | Release-control formulation and bioequivalence |
| Transdermal patch | Adhesion, permeation and device manufacturing |
| Topical gel | Dose uniformity, application and bioequivalence |
| Pediatric liquid | Stability, taste and dosing accuracy |
Manufacturing economics favor large generic suppliers. Smaller entrants may struggle to achieve competitive costs unless they target a shortage, a difficult formulation or a supply-constrained region.
What is the revenue exposure for manufacturers and investors?
Oxybutynin is more important as a portfolio cash-flow product than as a growth asset. The product can provide stable volume, but pricing power is limited.
| Investment factor | Assessment |
|---|---|
| Revenue growth | Low |
| Margin potential | Low for immediate-release; moderate for differentiated forms |
| Regulatory risk | Low to moderate |
| Patent risk | Low for standard oral products |
| Manufacturing risk | Moderate for transdermal and extended-release products |
| Competitive intensity | High |
| Substitution risk | Moderate to high |
| Strategic value | Portfolio diversification and stable generic volume |
The strongest commercial opportunities are likely to involve differentiated delivery systems, underserved geographies, supply-constrained channels or combination products. A conventional immediate-release tablet is unlikely to support substantial premium pricing.
Key Takeaways
- Oxybutynin chloride is a mature generic market with estimated 2024 global sales of $400 million to $650 million.
- Global revenue is likely to decline approximately 2% to 3% annually through 2029 as generic pricing falls.
- Prescription volume should remain comparatively stable because of low cost and broad availability.
- Immediate-release tablets are highly commoditized.
- Extended-release, transdermal and topical products offer better differentiation but require more complex development and manufacturing.
- Anticholinergic tolerability concerns are the main long-term demand risk.
- Mirabegron and vibegron represent the most important non-anticholinergic competitive threat.
- Original oral-product exclusivity has expired, and no broad patent barrier is expected to constrain generic supply.
- The strongest commercial strategy is cost-efficient supply or differentiated delivery, not a conventional premium-priced tablet launch.
FAQs
Is oxybutynin chloride still commercially attractive for generic manufacturers?
It is attractive as a stable-volume product but generally weak as a high-growth opportunity. Immediate-release tablets offer limited margin, while extended-release and transdermal products may support better economics.
Will mirabegron replace oxybutynin?
Mirabegron will continue to take share in patients who cannot tolerate anticholinergic effects, but oxybutynin’s lower price will preserve substantial use among cost-sensitive patients and in markets with restrictive reimbursement.
Does oxybutynin have biosimilar competition?
No. Oxybutynin is a chemically synthesized small molecule, so competition occurs through generic drug pathways rather than biosimilar regulation.
Which oxybutynin formulation has the highest growth potential?
Transdermal and topical products have greater differentiation potential than immediate-release tablets. Their growth is constrained by manufacturing complexity, patient acceptance and competition from oral generics.
Is oxybutynin subject to an upcoming patent cliff?
No major market-wide patent cliff is expected. The product is already deeply genericized, and future revenue erosion should reflect ongoing price competition and therapeutic substitution rather than a single expiration event.
References
-
American Geriatrics Society Beers Criteria Update Expert Panel. (2023). American Geriatrics Society 2023 updated AGS Beers Criteria for potentially inappropriate medication use in older adults. Journal of the American Geriatrics Society, 71(7), 2052-2081.
-
U.S. Food and Drug Administration. (2013). FDA approves Oxytrol for women over the counter. https://www.fda.gov
-
U.S. Food and Drug Administration. (2023). Oxybutynin chloride prescribing information. https://www.accessdata.fda.gov
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
More… ↓
