Share This Page
Drug Sales Trends for HYDROXYZINE PAMOATE
✉ Email this page to a colleague
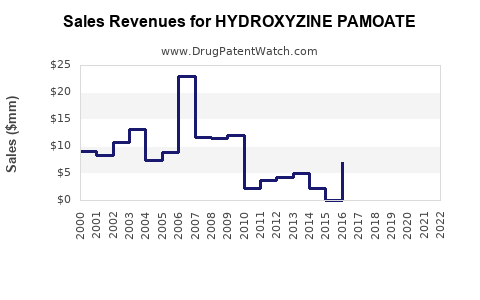
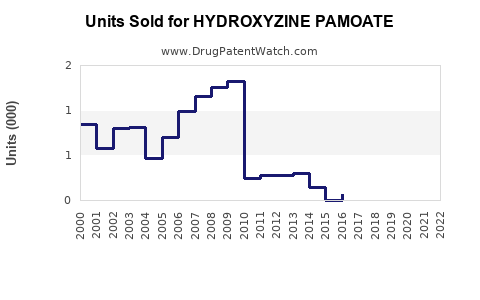
Annual Sales Revenues and Units Sold for HYDROXYZINE PAMOATE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| HYDROXYZINE PAMOATE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| HYDROXYZINE PAMOATE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| HYDROXYZINE PAMOATE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| HYDROXYZINE PAMOATE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| HYDROXYZINE PAMOATE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Hydroxyzine Pamoate Market Analysis and Sales Projections
Hydroxyzine pamoate is a mature, low-cost generic antihistamine and anxiolytic marketed mainly as oral capsules. The U.S. market has limited pricing power, minimal patent protection, and low commercial concentration. Revenue growth is likely to come from prescription volume, supply participation, and minor formulation or channel shifts rather than price increases.
A reasonable U.S. manufacturer-level revenue outlook is:
| Scenario | 2025 estimated market value | 2030 estimated market value | 2025-2030 CAGR |
|---|---|---|---|
| Low | $35 million | $31 million | -2.4% |
| Base | $50 million | $52 million | 0.8% |
| High | $70 million | $82 million | 3.2% |
These are modeled estimates for hydroxyzine pamoate prescription products, not reported industry sales. Public sources generally do not disclose standalone sales for the active ingredient because it is sold through multiple generic manufacturers, distributors and pharmacies.
What is hydroxyzine pamoate used for?
Hydroxyzine pamoate is an oral antihistamine approved for symptomatic relief of anxiety, management of pruritus caused by allergic conditions, and use as a preoperative sedative. Its pharmacological activity is associated with hydroxyzine, while the pamoate salt improves the product’s pharmaceutical presentation.[1]
The product is available primarily in 25 mg and 50 mg capsules, with some markets also carrying 100 mg strengths. Hydroxyzine hydrochloride is a separate salt and is commonly supplied as tablets, capsules or oral solution.
| Product attribute | Hydroxyzine pamoate |
|---|---|
| Active moiety | Hydroxyzine |
| Salt form | Pamoate |
| Primary dosage form | Oral capsule |
| Common strengths | 25 mg, 50 mg, 100 mg |
| Prescription status | Prescription-only in the United States |
| Main uses | Anxiety, pruritus, preoperative sedation |
| Drug class | First-generation antihistamine |
| U.S. market status | Generic, mature market |
| Main competitors | Hydroxyzine hydrochloride, cetirizine, diphenhydramine, buspirone, benzodiazepines and other anxiolytics |
Hydroxyzine pamoate is not a biologic, does not require biosimilar approval, and does not depend on a complex delivery device. Regulatory and manufacturing barriers are relatively low.
How large is the hydroxyzine pamoate market?
The market is best measured through prescription volume rather than branded revenue. Hydroxyzine products have broad clinical use, but hydroxyzine pamoate represents only part of the overall hydroxyzine market because the hydrochloride salt competes for many indications.
A practical U.S. market model estimates annual hydroxyzine pamoate volume at approximately 150 million to 250 million capsules, depending on whether institutional, cash-pay and mail-order dispensing are included. At generic net prices of roughly $0.20 to $0.40 per capsule, the implied manufacturer and channel market value is approximately $35 million to $70 million.
The estimate is sensitive to three variables:
- Whether the measurement includes only retail prescriptions or also institutional distribution.
- Whether revenue is measured at manufacturer, wholesaler or pharmacy level.
- The share of 25 mg, 50 mg and 100 mg capsules in the product mix.
Public prescription databases may report hydroxyzine hydrochloride and hydroxyzine pamoate separately, but they do not always provide consistent product-level net sales. IQVIA and Symphony Health data would provide the most reliable commercial volume estimates, but those datasets are proprietary.
What are the hydroxyzine pamoate sales projections through 2030?
The base-case projection assumes stable prescription demand, gradual erosion in average selling prices, modest population growth and no major supply disruption.
| Year | Base-case U.S. volume | Estimated average manufacturer-equivalent price per capsule | Estimated market value |
|---|---|---|---|
| 2025 | 190 million capsules | $0.26 | $49 million |
| 2026 | 193 million | $0.26 | $50 million |
| 2027 | 195 million | $0.26 | $51 million |
| 2028 | 197 million | $0.26 | $51 million |
| 2029 | 199 million | $0.26 | $52 million |
| 2030 | 201 million | $0.26 | $52 million |
The base case assumes volume growth of approximately 1% annually, offset by generic price competition. A more aggressive volume increase could result from expanded use in outpatient behavioral health and dermatology, but hydroxyzine pamoate faces substitution from non-sedating antihistamines and newer anxiety treatments.
Low-case projection
The low case assumes:
- Continued migration from hydroxyzine to non-sedating antihistamines for allergy-related use.
- Greater use of buspirone and selective serotonin reuptake inhibitors for chronic anxiety.
- Generic price compression of 2% to 4% annually.
- No material supply shortage.
Under this scenario, U.S. market value declines to approximately $31 million by 2030.
High-case projection
The high case assumes:
- Greater use in short-term anxiety and sleep-related prescribing.
- Stable demand for pruritus treatment.
- Periodic shortages among competing generic suppliers.
- Increased prescription volume from low-cost public and institutional channels.
Under this scenario, the market could reach approximately $82 million by 2030, although sustained pricing expansion is unlikely.
When does hydroxyzine pamoate lose exclusivity?
Hydroxyzine pamoate lost meaningful U.S. market exclusivity decades ago. The product is a legacy small-molecule generic with no current New Chemical Entity exclusivity and no commercially relevant patent barrier preventing ANDA competition.
The original branded hydroxyzine products, including Vistaril, are no longer protected by enforceable composition-of-matter exclusivity. Current competition is based on abbreviated new drug applications, manufacturing capacity, distributor contracts and pharmacy purchasing arrangements.
| Exclusivity category | Current status |
|---|---|
| New Chemical Entity exclusivity | Expired |
| Orphan-drug exclusivity | Not applicable |
| Pediatric exclusivity | No relevant current protection |
| Reference-product exclusivity | Expired |
| Patent-based market protection | No material current barrier identified |
| Generic competition | Established |
Hydroxyzine pamoate therefore has no conventional “loss of exclusivity” event ahead. The relevant commercial question is whether existing suppliers retain approval, capacity and competitive pricing.
What patents protect hydroxyzine pamoate?
No active, commercially meaningful U.S. patent estate is generally associated with the basic hydroxyzine pamoate capsule. The active ingredient and conventional capsule formulation are old technologies.
Potentially relevant patent categories would include:
- Salt or polymorph patents.
- Modified-release formulations.
- Combination products.
- Narrow manufacturing-process patents.
- Packaging or stability improvements.
- Delivery systems designed to reduce sedation or alter pharmacokinetics.
These categories have limited relevance to the established immediate-release capsule market unless a company develops and obtains approval for a differentiated product.
The FDA Orange Book is the controlling public source for patents and regulatory exclusivity associated with approved drugs. A conventional generic hydroxyzine pamoate capsule is not normally protected by a current Orange Book patent listing that would block ordinary ANDA competition.[2]
What is the FDA regulatory status of hydroxyzine pamoate?
Hydroxyzine pamoate is approved as a prescription drug in the United States. Generic products are approved through the ANDA pathway, which requires pharmaceutical equivalence and bioequivalence to the reference product rather than independent clinical efficacy trials.[3]
FDA labeling identifies central nervous system depression as a key safety concern. Hydroxyzine is also associated with QT-interval prolongation and torsade de pointes risk, particularly in patients with other risk factors or interacting medicines.[1,4]
The European Medicines Agency recommended restrictions on hydroxyzine exposure because of cardiac rhythm risk. Those restrictions include using the lowest effective dose for the shortest appropriate duration and avoiding use in patients with known risk factors for QT prolongation.[4]
Regulatory safety considerations can affect prescribing, but they are unlikely to produce a substantial change in generic pricing. They may shift demand toward alternatives in elderly patients, patients with cardiovascular risk and patients using other QT-prolonging medicines.
Are there Orange Book patents or Paragraph IV challenges?
Hydroxyzine pamoate is a mature generic market, so Paragraph IV litigation is unlikely to be a significant commercial factor. Paragraph IV certifications matter when an ANDA applicant challenges an unexpired listed patent. That framework has limited relevance when the reference product has no material active patent protection.
A new applicant could still file an ANDA with a Paragraph IV certification if an Orange Book patent were listed against a relevant reference product. In practical terms, the more important regulatory issues are:
- Product-specific bioequivalence.
- Manufacturing compliance.
- Stability data.
- Capsule dissolution performance.
- Labeling consistency.
- Facility inspection status.
- Drug shortage and supply-chain exposure.
Generic applicants typically compete through Paragraph III or “no relevant patent” positions when no unexpired patent blocks approval.
Which companies compete in hydroxyzine pamoate?
Competition is fragmented. Depending on the period and product listing, U.S. suppliers may include large generic manufacturers and specialty generic companies such as:
- Amneal Pharmaceuticals.
- Hikma Pharmaceuticals.
- Rising Pharmaceuticals.
- Wockhardt.
- Major private-label and contract-manufacturing suppliers.
- Regional manufacturers serving institutional and government accounts.
Supplier participation changes over time because generic companies discontinue low-margin products, transfer approvals or reduce production when prices fall below an acceptable return threshold. Product availability should therefore be assessed through current FDA listings and National Drug Code records rather than historical manufacturer lists.[2,5]
No single company is likely to control the full U.S. market. The largest commercial advantage generally belongs to suppliers with:
- Existing oral-solid-dose manufacturing capacity.
- Low-cost active pharmaceutical ingredient sourcing.
- Established wholesaler contracts.
- Reliable regulatory compliance.
- Ability to maintain supply during competitor disruptions.
How strong is the hydroxyzine pamoate patent estate?
The patent estate is weak from a blocking perspective but durable from a manufacturing perspective.
| Commercial protection type | Strength | Market effect |
|---|---|---|
| Composition-of-matter patent | Very low | No meaningful barrier |
| Conventional capsule formulation | Very low | Easily replicated |
| ANDA approval | Moderate | Provides lawful market access |
| Manufacturing scale | Moderate | Can protect supply contracts |
| API sourcing | Moderate | May affect margins and availability |
| Brand recognition | Low to moderate | Limited because prescribing is generic |
| Regulatory compliance | Moderate | Can remove weak suppliers from the market |
The most defensible assets are operational rather than legal. A manufacturer with dependable supply, competitive cost and clean inspection history can maintain share even without patent protection.
What generic entry risks exist?
Generic entry risk is already realized because hydroxyzine pamoate is a generic product. Future entrants can intensify price competition, especially for 25 mg and 50 mg capsules, which account for much of routine prescribing.
The main risks to an incumbent supplier are:
- New ANDA approvals.
- Contract loss to lower-cost manufacturers.
- Wholesaler consolidation.
- Medicaid and institutional reimbursement pressure.
- Product discontinuation by a key API or capsule supplier.
- FDA manufacturing observations.
- Substitution by hydroxyzine hydrochloride.
- Prescriber movement to non-sedating or newer therapies.
The market also has a countervailing supply risk. If several low-margin suppliers exit, remaining companies may gain temporary volume and pricing leverage. That effect is usually short-lived because generic manufacturers can re-enter or expand production when margins improve.
How does hydroxyzine pamoate compare with hydroxyzine hydrochloride?
Hydroxyzine pamoate and hydroxyzine hydrochloride contain the same active moiety but use different salt forms. They are not interchangeable solely because they contain hydroxyzine. Product-specific labeling, dosage form and strength must be considered.
| Attribute | Hydroxyzine pamoate | Hydroxyzine hydrochloride |
|---|---|---|
| Common dosage forms | Capsules | Tablets, capsules, oral solution |
| Main commercial use | Anxiety, pruritus, sedation | Anxiety, pruritus, sedation |
| Prescription competition | High | High |
| Formulation flexibility | Lower | Higher |
| Patient convenience | Moderate | Higher where liquid is needed |
| Patent position | Mature generic | Mature generic |
| Pricing power | Low | Low |
| Substitution risk | High | High |
Hydroxyzine hydrochloride has a broader dosage-form platform because oral solution products can serve pediatric and swallowing-impaired patients. Hydroxyzine pamoate remains commercially relevant where capsule supply, prescribing habits and low acquisition cost drive selection.
What licensing deals and manufacturing barriers affect the market?
No major current licensing transaction is required to commercialize conventional hydroxyzine pamoate in the United States. The product is generally supplied through standard generic manufacturing, contract manufacturing or private-label arrangements.
The main barriers are:
- FDA-compliant oral solid-dose production.
- Qualified hydroxyzine pamoate API supply.
- Stability and dissolution performance.
- Reliable packaging and serialization.
- Wholesaler and pharmacy distribution access.
- Quality-system maintenance.
A company pursuing a differentiated product, such as a modified-release formulation or combination therapy, would face greater development and regulatory costs. That strategy could create new intellectual property but would compete against an inexpensive established generic and would need a clear clinical or adherence advantage.
What litigation affects hydroxyzine pamoate?
Hydroxyzine pamoate does not have a prominent current U.S. patent-litigation profile comparable to newer branded drugs. Litigation risk is more likely to arise from:
- Manufacturing contracts.
- Product liability claims.
- Supply agreements.
- FDA enforcement actions.
- Labeling and pharmacovigilance disputes.
- Patent disputes involving a new formulation rather than the conventional capsule.
The absence of major patent litigation reduces legal barriers to entry. It also limits the ability of a supplier to defend price levels through exclusivity.
What is the commercial outlook for hydroxyzine pamoate?
Hydroxyzine pamoate is a stable but low-value generic market. Its commercial profile is more attractive for an established generic manufacturer than for a company seeking a high-growth branded asset.
| Factor | Outlook |
|---|---|
| Prescription demand | Stable to modest growth |
| Pricing | Flat to declining |
| Patent protection | Minimal |
| Regulatory complexity | Low to moderate |
| Manufacturing complexity | Low |
| Competition | High |
| Shortage upside | Possible but temporary |
| Branded launch opportunity | Limited |
| Licensing value | Low for conventional product |
| Investment case | Operational efficiency, not IP-driven growth |
Revenue upside is strongest for companies that can consolidate fragmented supply, win institutional contracts or maintain availability when competitors exit. A stand-alone branded investment would have weak economics unless paired with a differentiated formulation, new delivery system or broader product portfolio.
Key Takeaways
- Hydroxyzine pamoate is a mature generic prescription market with minimal patent protection.
- Estimated U.S. market value is approximately $35 million to $70 million annually at the manufacturer and channel level.
- A base-case forecast reaches about $52 million by 2030, implying less than 1% annual growth.
- No meaningful future loss-of-exclusivity event is expected because the product lost exclusivity decades ago.
- Paragraph IV litigation and Orange Book patent barriers are unlikely to materially affect conventional capsules.
- Hydroxyzine hydrochloride is the principal salt-form competitor and has a broader dosage-form portfolio.
- Commercial value depends on supply reliability, manufacturing cost, distribution access and regulatory compliance.
- Biosimilar risk is not applicable because hydroxyzine pamoate is a small-molecule drug.
- The strongest investment thesis is low-cost generic supply, not branded pricing or patent monetization.
FAQs About Hydroxyzine Pamoate Market Size and Exclusivity
Is hydroxyzine pamoate still profitable for generic manufacturers?
Yes, but profitability depends on manufacturing cost, product volume and supply reliability. The product has limited pricing power, so smaller suppliers may face weak margins.
Does hydroxyzine pamoate have a branded version?
Vistaril is the historical branded product associated with hydroxyzine pamoate. Current U.S. prescriptions are predominantly supplied through generic products.
Can a new company obtain FDA approval for hydroxyzine pamoate?
Yes. A company can pursue an ANDA for a therapeutically equivalent product if it satisfies FDA requirements for pharmaceutical equivalence, bioequivalence, manufacturing quality and labeling.
Is hydroxyzine pamoate subject to biosimilar competition?
No. Hydroxyzine pamoate is a chemically synthesized small-molecule drug. Competition occurs through generic drug applications, not the biosimilar pathway.
Could hydroxyzine pamoate sales increase during a drug shortage?
Yes. A shortage affecting competing hydroxyzine suppliers or alternative sedating antihistamines could temporarily increase demand and improve pricing. The effect would likely decline as supply normalizes.
References
-
U.S. Food and Drug Administration. (2023). Hydroxyzine pamoate capsule prescribing information. FDA labeling database.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
-
U.S. Food and Drug Administration. (2024). Abbreviated new drug application (ANDA) process. FDA.
-
European Medicines Agency. (2015). Hydroxyzine-containing medicines: Referral procedure and restrictions to minimize cardiac risk. EMA.
-
U.S. Food and Drug Administration. (2024). National Drug Code Directory. FDA.
More… ↓
