Share This Page
Drug Sales Trends for HORIZANT
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for HORIZANT (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
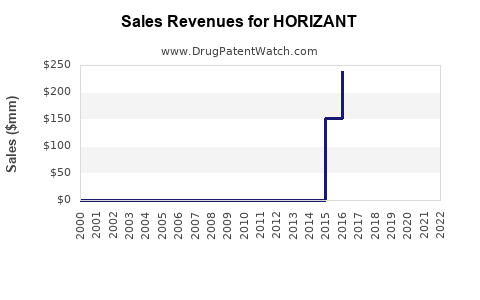
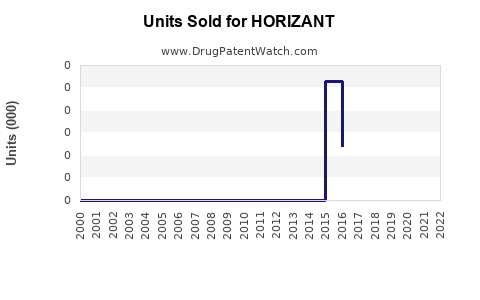
Annual Sales Revenues and Units Sold for HORIZANT
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| HORIZANT | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| HORIZANT | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| HORIZANT | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Horizant Market Analysis and Sales Projections: Gabapentin Enacarbil
Horizant is a U.S. niche branded drug with two approved uses: moderate-to-severe primary restless legs syndrome (RLS) and postherpetic neuralgia (PHN). Its commercial opportunity is constrained by competition from low-cost generic gabapentin, pregabalin, dopamine agonists, and nonprescription RLS treatments. The product can retain meaningful specialty-pharmacy revenue while patent and regulatory barriers delay generic substitution, but it lacks the scale of a mass-market neuropathic-pain medicine.
A base-case model estimates U.S. net sales of approximately $115 million in 2025, rising modestly to $125 million to $135 million through 2027 before declining as generic-entry risk increases. A downside scenario places sales below $75 million by 2028. An upside scenario reaches $160 million if the product maintains favorable reimbursement, expands RLS diagnosis and treatment, and avoids an earlier generic launch.
What is Horizant and which patients does it treat?
Horizant contains gabapentin enacarbil, a prodrug of gabapentin formulated as an extended-release tablet. The FDA approved Horizant in 2011 for moderate-to-severe primary RLS and in 2013 for PHN in adults [1].
| Product attribute | Horizant |
|---|---|
| Active ingredient | Gabapentin enacarbil |
| Dosage form | Extended-release tablet |
| Strengths | 300 mg and 600 mg |
| FDA-approved uses | Primary RLS; PHN |
| RLS dose | 600 mg once daily at approximately 5 p.m. |
| PHN dose | 600 mg twice daily |
| Administration | With food |
| U.S. drug class | Prescription, non-opioid CNS medicine |
| Main substitutes | Generic gabapentin, pregabalin, pramipexole, ropinirole, rotigotine |
| Primary commercial market | United States |
Gabapentin enacarbil was designed to improve the absorption and pharmacokinetic consistency of gabapentin. That differentiation has clinical and commercial value, but it does not eliminate payer pressure. Most insurers place generic gabapentin and pregabalin ahead of Horizant in step-therapy protocols.
How large is the Horizant market?
Horizant operates in two markets with different commercial economics.
Restless legs syndrome market
RLS is the larger strategic opportunity because Horizant has a labeled indication and a relatively differentiated once-daily evening regimen. Treatment demand is driven by:
- Greater recognition of moderate-to-severe RLS in primary care and sleep medicine.
- Increased use of alpha-2-delta ligands following concern about augmentation with dopamine agonists.
- Persistent undertreatment among patients with sleep disruption and painful sensory symptoms.
- Specialist prescribing in patients who do not respond adequately to generic gabapentin or dopamine agonists.
The RLS market remains price sensitive. Generic gabapentin, pregabalin, pramipexole, ropinirole, and rotigotine are available at lower cost. Horizant’s commercial position depends on patients who value dosing consistency, branded support services, or a product-specific reimbursement pathway.
Postherpetic neuralgia market
PHN is a smaller and more competitive opportunity. Generic gabapentin and pregabalin are established standards, while lidocaine patches, tricyclic antidepressants, and topical therapies compete for treatment share. Horizant’s twice-daily dosing for PHN provides less differentiation than its RLS regimen.
PHN prescriptions can generate higher initial treatment volume after shingles, but persistence is limited because some patients recover over time. This limits recurring revenue and reduces the value of PHN as a long-term growth engine.
What are Horizant’s historical sales and current revenue drivers?
Product-level sales are not consistently disclosed in public filings by the private companies associated with Horizant commercialization. The following figures are an analyst model rather than reported audited revenue.
The model assumes U.S. net sales, excluding gross-to-net deductions, channel inventory distortion, and any undisclosed licensing payments.
| Year | Base-case U.S. net sales | Low case | High case |
|---|---|---|---|
| 2023 | $105 million | $95 million | $120 million |
| 2024 | $110 million | $95 million | $130 million |
| 2025 | $115 million | $90 million | $140 million |
| 2026 | $120 million | $82 million | $150 million |
| 2027 | $130 million | $75 million | $160 million |
| 2028 | $105 million | $55 million | $145 million |
| 2029 | $70 million | $30 million | $120 million |
| 2030 | $45 million | $15 million | $90 million |
The base case assumes low-single-digit prescription growth through 2027, partly offset by higher rebates and payer restrictions. Revenue then declines as generic entry becomes more likely.
The main revenue drivers are:
- Branded net price and rebate retention.
- Prescription volume in RLS rather than PHN.
- Duration of therapy among chronic RLS patients.
- Access to commercial insurance and Medicare Part D formularies.
- Timing and scope of any generic gabapentin enacarbil launch.
- Prescriber adoption after dopamine-agonist treatment failure.
- Pharmacy substitution rules and Orange Book listings.
When does Horizant lose exclusivity?
Horizant’s commercial exclusivity depends on both FDA regulatory exclusivity and patent protection. FDA approval exclusivity has expired for the original indications. The remaining protection is primarily patent-based and depends on the specific Orange Book-listed patents and any later-issued or pediatric patents.
FDA product exclusivity for a small-molecule drug typically does not provide a durable barrier after the initial approval period. A generic applicant can seek approval through an abbreviated new drug application and challenge listed patents through Paragraph IV certification [2].
The practical loss-of-exclusivity date is therefore determined by the latest enforceable patent that covers the approved product, formulation, or method of use, not by the 2011 or 2013 approval dates alone.
Patent and generic-entry risk
Potential generic applicants may challenge:
- The extended-release formulation.
- The gabapentin enacarbil active ingredient or prodrug form.
- Manufacturing or processing limitations.
- Method-of-use claims for RLS.
- Method-of-use claims for PHN.
- Dosage and administration limitations.
A generic company does not need to reproduce the branded commercial strategy. It needs FDA approval for a therapeutically equivalent product that can be substituted at the pharmacy level where state law permits.
What is the Orange Book status of Horizant?
Horizant is listed in the FDA Approved Drug Products with Therapeutic Equivalence Evaluations, commonly called the Orange Book. The Orange Book identifies reference-listed-drug status and any patents or exclusivity information reported by the sponsor [3].
Orange Book status matters because:
- Listed patents can trigger a 30-month stay after a Paragraph IV notice and timely patent litigation.
- A generic applicant may file a Paragraph III certification and wait for patent expiry.
- A Section viii statement may omit a patented method of use if the proposed label excludes that use.
- A formulation patent can be more commercially important than a narrow method-of-use patent if it supports automatic substitution.
The strength of the estate depends on claim scope, patent-term adjustment, prosecution history, prior art, and whether a generic product can design around the asserted claims. A current transaction, litigation, or generic filing could change the commercial timeline.
Which companies are challenging Horizant?
No broadly disclosed, high-volume generic challenge has established a public market launch date comparable to major blockbuster products. The likely challengers are generic manufacturers with experience in CNS products and extended-release formulations.
Potential participants include large generic companies such as Teva, Viatris, Sandoz, Amneal, Lupin, and Dr. Reddy’s, although a company’s presence in the gabapentin market does not establish a Horizant-specific filing or challenge.
The commercial risk increases materially if:
- A Paragraph IV ANDA is publicly disclosed.
- The sponsor files patent litigation within the statutory period.
- Multiple generic applicants enter simultaneously.
- The first filer receives 180-day exclusivity.
- A court invalidates or narrows the principal formulation patent.
What generic launch scenarios exist for Horizant?
Scenario 1: No generic launch through 2027
The branded product retains its niche, and sales grow modestly through specialist prescribing. This scenario supports the $125 million to $160 million high-case range.
Scenario 2: First generic launch in 2028
Horizant experiences a rapid decline in prescription volume and net price. A 50% to 70% first-year revenue reduction is plausible if substitution is allowed and multiple manufacturers launch.
Scenario 3: Authorized generic or negotiated entry
The brand owner licenses or supplies an authorized generic. Brand revenue falls, but combined franchise economics improve relative to an uncoordinated generic launch. This strategy can preserve manufacturing utilization and generate royalty or supply income.
Scenario 4: Narrow label carve-out
A generic enters with one indication removed through a Section viii statement. The impact depends on pharmacy substitution practices and whether the remaining indication represents most prescriptions. A carve-out may reduce but not eliminate brand erosion.
How strong is the Horizant patent estate?
Horizant’s patent estate is commercially meaningful but not inherently strong enough to guarantee long-term protection. Its value rests on the interaction of formulation claims, active-ingredient claims, method-of-use claims, and regulatory listing strategy.
The formulation is the most important protection if the claims cover the release profile and dosage form required for therapeutic equivalence. Method-of-use patents are more vulnerable commercially because generic applicants may omit protected indications from their labeling.
Patent strength is reduced by:
- The age of the underlying product.
- Extensive prior art involving gabapentin and prodrug chemistry.
- The ability to design alternative extended-release formulations.
- Potential obviousness challenges.
- The limited number of approved indications.
- Low revenue relative to the cost of patent litigation.
Patent strength is improved by:
- Claims covering the commercial dosage form.
- Multiple unexpired patents with distinct claim scope.
- FDA-recognized listing that supports a statutory litigation stay.
- Clinical or pharmacokinetic differences that make design-around difficult.
- A narrow but defensible formulation claim set.
How does Horizant compare with generic gabapentin and pregabalin?
| Factor | Horizant | Generic gabapentin | Generic pregabalin |
|---|---|---|---|
| Active ingredient | Gabapentin enacarbil | Gabapentin | Pregabalin |
| Formulation | Extended release | Immediate or extended release, depending on product | Immediate release; extended-release options exist |
| RLS approval | Yes | No branded RLS indication | No branded RLS indication in many markets |
| PHN approval | Yes | Widely used off-label and in approved pain indications | Yes |
| Cost | High | Very low | Low to moderate |
| Payer position | Often restricted | Preferred | Preferred or step-therapy |
| Main advantage | Labeled RLS use and pharmacokinetic design | Price and familiarity | Efficacy, dosing, and broad use |
| Main weakness | Brand price and access barriers | Variable absorption and off-label use | Cost and adverse effects |
Horizant’s primary competitive advantage is not low cost. It is a branded, FDA-approved extended-release option for RLS with a defined evening dosing schedule.
What regulatory and commercial risks affect Horizant?
FDA regulatory risk is moderate because the product has long-established approvals and no new indication is required for the base business. The principal risks are commercial:
- Formulary exclusion or unfavorable tier placement.
- Prior authorization and step edits.
- Rebate escalation.
- Generic approval.
- Reduced treatment persistence.
- Safety concerns associated with gabapentinoids, including sedation, dizziness, respiratory depression risk in susceptible patients, and misuse concerns [1, 4].
- Declining prescriber willingness to use branded gabapentinoids.
The product has no biosimilar risk. Horizant is a small-molecule drug, so competitive entry would occur through the generic ANDA pathway rather than the biosimilar pathway.
What manufacturing and intellectual-property barriers exist?
Manufacturing barriers are meaningful but manageable. A generic applicant must reproduce the active pharmaceutical ingredient, extended-release performance, stability profile, tablet characteristics, and bioequivalence required by FDA. Extended-release products can create development and scale-up challenges, particularly if the release mechanism is difficult to replicate.
These barriers can delay entry but rarely prevent it permanently. The commercial value of the barrier depends on the remaining patent term and the number of potential generic manufacturers willing to invest in development.
Geographic protection is concentrated in the United States. The product’s value is primarily tied to U.S. patents, FDA approval, payer access, and American specialty-pharmacy distribution. International revenue is unlikely to materially change the overall valuation unless separate national approvals and patent rights exist.
What is the investment outlook for Horizant?
Horizant is best viewed as a mature specialty-pharma cash-flow asset rather than a growth product. The investment case depends on three variables:
- The duration of patent-protected or practically protected sales.
- Net price after rebates and patient-support costs.
- The probability and timing of generic substitution.
At a $115 million base-case revenue level, a mature branded product could generate attractive operating margins if promotional spending remains controlled. The valuation should apply a steep discount to revenue expected after the first credible generic challenge.
A strategic buyer would likely focus on:
- RLS prescription growth.
- Payer concentration.
- Gross-to-net trends.
- Patient persistence.
- Orange Book patent status.
- Paragraph IV litigation exposure.
- The ability to launch or license an authorized generic.
- Manufacturing cost per tablet.
- Exposure to Medicare Part D redesign and specialty-pharmacy fees.
Key Takeaways
- Horizant is a branded gabapentin enacarbil product approved for RLS and PHN.
- RLS is the stronger commercial indication because of the product’s once-daily evening regimen and labeled use.
- Generic gabapentin and pregabalin impose persistent pricing and formulary pressure.
- A base-case model estimates U.S. net sales of $115 million in 2025 and a peak of $125 million to $135 million in 2027.
- Revenue could fall below $75 million by 2028 if a generic launches and achieves pharmacy substitution.
- Horizant has no biosimilar risk because it is a small-molecule drug.
- The principal strategic asset is its formulation and regulatory position, not broad market size.
- Any Paragraph IV filing, patent settlement, authorized-generic agreement, or Orange Book change could materially alter the forecast.
FAQs
Is Horizant stronger than gabapentin for restless legs syndrome?
Horizant has an FDA-approved RLS indication and an extended-release pharmacokinetic design. Generic gabapentin is cheaper and widely used, but its RLS use is generally off-label.
Can a generic company substitute gabapentin for Horizant?
No. Generic gabapentin is not automatically therapeutically substitutable for Horizant solely because both deliver gabapentin-related activity. A generic version of gabapentin enacarbil would be required for direct product substitution.
Does Horizant have biosimilar competition?
No. Horizant is a small-molecule drug. Any competing product would generally follow the generic ANDA pathway rather than the FDA biosimilar pathway.
What indication contributes most to Horizant sales?
RLS is expected to contribute most of the commercial value because Horizant has a differentiated once-daily evening dose and a specific FDA-approved indication. PHN is more exposed to low-cost generic competition.
What would happen to Horizant sales after generic entry?
A first generic launch could reduce branded revenue by roughly 50% to 70% in the first year, with steeper erosion if several manufacturers enter and pharmacy substitution is widespread.
References
-
U.S. Food and Drug Administration. (2023). Horizant (gabapentin enacarbil) extended-release tablets: Prescribing information. https://www.accessdata.fda.gov/drugsatfda_docs/label/
-
U.S. Food and Drug Administration. (2024). Abbreviated new drug application approvals and patent certifications. https://www.fda.gov/drugs/abbreviated-new-drug-application-anda/anda-submissions
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, Orange Book. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (2019). FDA warns about serious breathing problems with gabapentin and pregabalin. https://www.fda.gov/drugs/drug-safety-and-availability/fda-warns-about-serious-breathing-problems-gabapentin-and-pregabalin‑<|end|>
More… ↓
