Share This Page
Drug Sales Trends for GENTAMICIN SULFATE
✉ Email this page to a colleague
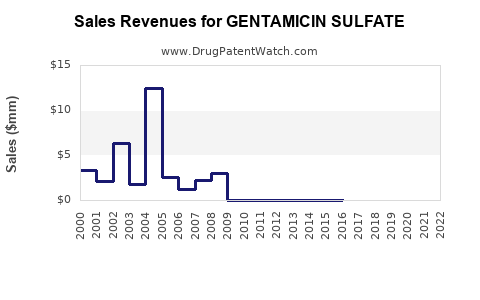
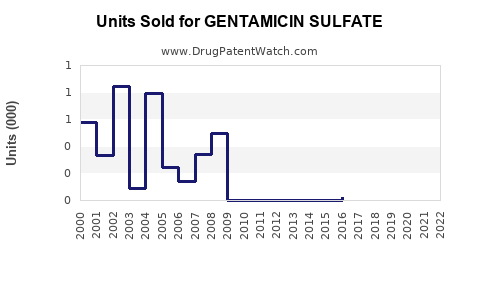
Annual Sales Revenues and Units Sold for GENTAMICIN SULFATE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| GENTAMICIN SULFATE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| GENTAMICIN SULFATE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| GENTAMICIN SULFATE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| GENTAMICIN SULFATE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Gentamicin Sulfate Market Analysis and Sales Projections, 2025-2030
Gentamicin sulfate is a mature, low-cost aminoglycoside antibiotic with no meaningful originator-brand franchise. Its commercial market is fragmented across injectable, ophthalmic, otic, topical, and veterinary products. Demand is supported by hospital use, essential-medicine procurement, and low-cost access in emerging markets. Revenue growth is constrained by generic price competition, antimicrobial stewardship, toxicity monitoring, and substitution by newer antibiotics.
Public sources do not report a consolidated global revenue figure for gentamicin sulfate across all manufacturers, dosage forms, countries, and human and veterinary channels. The most defensible forecast is therefore a volume-led model using a 2025 revenue index of 100.
What is the current market status of gentamicin sulfate?
Gentamicin sulfate is a generic active pharmaceutical ingredient marketed primarily as:
| Product segment | Main use | Commercial position |
|---|---|---|
| Injectable solution | Severe gram-negative infections, sepsis, endocarditis combination therapy | Largest human pharmaceutical segment |
| Ophthalmic solution or ointment | Bacterial conjunctivitis and ocular infections | Mature, low-priced segment |
| Otic products | Bacterial external ear infections | Small human segment |
| Topical cream or ointment | Localized skin infections | Commodity segment |
| Veterinary injection and formulations | Livestock, companion animals, aquaculture | Material but separately regulated market |
The injectable segment has the highest clinical and procurement value because gentamicin remains useful against susceptible aerobic gram-negative organisms and in selected combination regimens. Its use is limited by nephrotoxicity and ototoxicity, which require dose adjustment and therapeutic monitoring, particularly in patients with renal impairment.
In the United States, gentamicin sulfate products are approved as generic prescription medicines. FDA labeling identifies uses that include serious infections caused by susceptible organisms and combination treatment for selected gram-positive infections such as enterococcal endocarditis. Product labeling also warns about nephrotoxicity, ototoxicity, neuromuscular blockade, and the need for monitoring (U.S. Food and Drug Administration [FDA], 2024a; National Library of Medicine, 2024).
How large is the gentamicin sulfate market?
The market is commercially significant in aggregate but not concentrated in a single branded product. Public company filings generally do not disclose gentamicin sulfate revenue separately. Manufacturers report it within broader generic injectable, hospital, ophthalmic, topical, or animal-health categories.
The commercial market has five defining characteristics:
- Generic competition is extensive.
- Product prices are low relative to newer antibiotics.
- Hospital contracts and government tenders have a major effect on volume.
- Manufacturing reliability matters more than brand differentiation.
- Human and veterinary demand follow different regulatory and procurement cycles.
A reasonable strategic classification is:
| Market attribute | Assessment |
|---|---|
| Product maturity | Mature |
| Generic competition | Very high |
| Pricing power | Low |
| Supply-chain sensitivity | Moderate to high |
| Clinical differentiation | Limited |
| Regulatory barrier | Low for established products; higher for new facilities or formulations |
| Revenue growth driver | Volume and geographic expansion |
| Main commercial risk | Price erosion and substitution |
The injectable market is more defensible than topical products because hospital procurement requires validated sterile manufacturing, quality systems, pharmacopoeial compliance, and reliable supply. The barrier is still lower than for complex biologics or novel sterile products.
What are the main demand drivers for gentamicin sulfate?
Hospital and institutional procurement is the primary demand driver for injectable gentamicin sulfate. The drug remains included in many national and institutional formularies because it is inexpensive, familiar to clinicians, and active against a range of gram-negative pathogens.
Hospital and sepsis treatment
Gentamicin may be used empirically or definitively when local susceptibility patterns support its use. It is also used in combination regimens for selected infections. The growth of hospital admissions, intensive-care capacity, and surgical procedures can increase unit demand, although stewardship programs may reduce routine aminoglycoside use.
Essential-medicine procurement
Gentamicin is included in the World Health Organization Model List of Essential Medicines in injectable and other formulations, supporting procurement in public-health systems and lower-income countries (World Health Organization, 2023). Essential-medicine status improves baseline demand but does not create pricing power.
Veterinary applications
Veterinary gentamicin products represent a separate demand pool. Use includes companion-animal treatment and selected livestock or aquaculture applications. Regulatory restrictions on antimicrobial use in food-producing animals can reduce volume in some jurisdictions, while companion-animal demand is more stable.
Ophthalmic and topical use
Ophthalmic gentamicin remains available for susceptible bacterial eye infections, but it competes with other topical antibiotics and combination products. Topical demand is relatively stable and highly price sensitive.
What factors could reduce gentamicin sulfate sales?
The largest headwinds are clinical substitution, antimicrobial stewardship, and generic price pressure.
| Risk factor | Effect on sales |
|---|---|
| Nephrotoxicity and ototoxicity | Reduces use in high-risk patients |
| Therapeutic drug monitoring requirements | Limits convenience versus some alternatives |
| Antimicrobial stewardship | Reduces unnecessary aminoglycoside exposure |
| Resistance | Erodes use against resistant organisms |
| Broad-spectrum alternatives | Shifts treatment toward newer agents |
| Tender price reductions | Lowers revenue even when unit volume is stable |
| Manufacturer exits | Can create shortages but may also concentrate supply |
| Veterinary restrictions | Reduces some animal-health applications |
Gentamicin is not a suitable substitute for newer agents active against many multidrug-resistant pathogens. Its clinical role depends on susceptibility, infection site, renal function, and the availability of safer alternatives.
What are the 2025-2030 sales projections for gentamicin sulfate?
The base-case forecast is for declining nominal revenue in mature markets, offset partly by volume growth in emerging markets and periodic supply-driven price increases. The projection uses 2025 as an index of 100 rather than an unsupported global dollar estimate.
| Year | Base-case revenue index | Downside index | Upside index |
|---|---|---|---|
| 2025 | 100 | 100 | 100 |
| 2026 | 99 | 95 | 103 |
| 2027 | 98 | 90 | 106 |
| 2028 | 97 | 86 | 109 |
| 2029 | 96 | 82 | 112 |
| 2030 | 95 | 78 | 115 |
Base-case assumptions
The base case assumes:
- Mature-market unit volume declines by approximately 1% to 2% annually.
- Emerging-market unit volume grows by approximately 2% to 4% annually.
- Average selling prices decline by approximately 2% to 4% annually in competitive generic channels.
- Sterile injectable products perform better than topical products.
- Veterinary demand remains broadly stable, with regional variation.
- Shortages create temporary price increases but do not permanently expand the market.
Under this model, global revenue is broadly flat to modestly lower through 2030. The base-case revenue compound annual growth rate is approximately negative 1% over 2025-2030.
Downside scenario
The downside case assumes faster substitution by beta-lactam, fluoroquinolone, glycopeptide, and newer resistant-pathogen therapies; continued reduction in aminoglycoside use under stewardship programs; and aggressive tender pricing. Revenue would decline approximately 5% annually.
Upside scenario
The upside case requires a combination of hospital supply shortages, expanded procurement in lower-income markets, increased veterinary volume, and stable demand for low-cost injectable antibiotics. The upside case is more likely to produce temporary revenue spikes than sustained structural growth.
Which dosage forms have the strongest commercial prospects?
Injectable gentamicin sulfate
Injectable products have the strongest long-term commercial position. Sterile manufacturing, hospital qualification, and procurement relationships create more operational barriers than those in creams or basic ophthalmic products. The segment remains vulnerable to price erosion but benefits from recurring institutional demand.
Injectable products are most attractive for manufacturers with:
- Existing sterile-fill capacity
- Hospital and government tender access
- Validated gentamicin API supply
- Low-cost packaging and distribution
- A portfolio of complementary injectable antibiotics
Ophthalmic products
Ophthalmic gentamicin has moderate commercial stability but limited growth potential. The segment is exposed to substitution by other topical antibiotics and fixed-dose combinations. Prescribers may select products based on tolerability, availability, and local resistance rather than brand identity.
Topical products
Topical cream and ointment products have the weakest pricing position. They are easy to substitute and compete with numerous branded and generic anti-infective products. The segment can generate steady retail volume but is unlikely to support meaningful pricing expansion.
Veterinary products
Veterinary products can provide geographic diversification. The segment carries regulatory and reputational risk because governments are tightening controls on antimicrobial use in food-producing animals. Companion-animal products have a more stable demand profile than food-animal applications.
What is the FDA regulatory status of gentamicin sulfate?
Gentamicin sulfate is an established FDA-approved generic drug active ingredient. FDA-approved products include injectable and topical or ophthalmic presentations, depending on the applicant and dosage form. Product-specific approval status, labeling, manufacturing site, and marketing status must be checked in Drugs@FDA and FDA’s Orange Book because generic products may be approved, discontinued, or listed under different application numbers (FDA, 2024b).
Gentamicin sulfate is a small-molecule generic, not a biologic. Biosimilar competition is therefore not relevant. Competition occurs through abbreviated new drug applications, generic drug approvals, private-label supply, hospital contracts, and veterinary approvals.
What is the Orange Book status of gentamicin sulfate?
The Orange Book is relevant primarily to approved prescription drug applications and listed therapeutic equivalents. Gentamicin sulfate products are generally mature generic products without a commercially meaningful remaining originator patent estate. Orange Book listings can vary by dosage form, strength, route of administration, and applicant.
Key implications are:
- No major branded gentamicin sulfate exclusivity period drives the market.
- Generic approval is the main competitive pathway.
- Listed patents, if any, are product-specific rather than a broad market barrier.
- Older injectable and topical products are generally exposed to multiple approved suppliers.
- Orange Book status does not capture all procurement, manufacturing, or supply-chain advantages.
A manufacturer evaluating entry should review the current Orange Book entry for the exact dosage form and strength, along with FDA approval letters and discontinued-product records.
Are there Paragraph IV challenges involving gentamicin sulfate?
Paragraph IV litigation is not a central market issue for legacy gentamicin sulfate products. The drug has been marketed for decades, and the principal products are generic rather than protected by an active, high-value originator patent estate.
Any Paragraph IV filing would need to be evaluated against the specific reference-listed drug, strength, dosage form, and listed patent. The commercial importance of such a filing would likely be limited unless it involved a differentiated formulation, delivery system, or combination product.
The more relevant risks are:
- ANDA approval timing
- FDA complete-response letters
- Manufacturing-site inspection outcomes
- Sterile-product quality findings
- Drug-shortage events
- Hospital contract awards
- API supply disruption
What patent protection covers gentamicin sulfate?
The core gentamicin sulfate molecule is not a strong patent-protected asset in the modern market. Potentially relevant intellectual property may instead concern:
- Novel ophthalmic delivery systems
- Sustained-release ocular formulations
- Combination products
- Device-assisted administration
- Stabilization or packaging systems
- Manufacturing or purification processes
- Veterinary delivery formulations
- Specific dosing methods or treatment protocols
A formulation patent would need a meaningful clinical or manufacturing advantage to support premium pricing. A standard injectable vial, ampoule, topical cream, or ophthalmic solution generally has limited patent-based differentiation because multiple generic suppliers can produce comparable products under established specifications.
How strong is the commercial patent estate for gentamicin sulfate?
| Patent category | Commercial strength |
|---|---|
| Core active ingredient | Very weak or exhausted |
| Standard injectable formulation | Weak |
| Standard ophthalmic solution | Weak |
| Topical cream or ointment | Weak |
| Novel sustained-release delivery | Potentially moderate |
| Combination product | Product-specific |
| Manufacturing process | Moderate if difficult to design around |
| Device or packaging system | Moderate if clinically integrated |
The strongest defensibility is operational rather than patent-based. A supplier with dependable sterile manufacturing, regulatory history, low failure rates, and hospital contracts may outperform a patent holder without manufacturing scale.
Which companies compete in the gentamicin sulfate market?
Competition is distributed across generic pharmaceutical companies, contract manufacturers, hospital suppliers, ophthalmic companies, and animal-health manufacturers. The precise supplier set varies by country and product form.
The competitive landscape includes:
- Large generic injectable manufacturers
- Regional hospital-drug suppliers
- Ophthalmic generic companies
- Contract development and manufacturing organizations
- API producers in China and India
- Veterinary pharmaceutical companies
- Government-qualified tender suppliers
Company-level sales comparisons are difficult because gentamicin revenue is normally bundled into broader portfolios. The relevant competitive metrics are product availability, approved manufacturing sites, shortage history, tender participation, API qualification, and sterile capacity.
What licensing deals affect gentamicin sulfate?
Large licensing transactions centered solely on conventional gentamicin sulfate are uncommon. Commercial agreements generally involve:
- Private-label supply
- Contract manufacturing
- API supply
- Regional distribution
- Hospital or government tenders
- Veterinary product licensing
- Combination or delivery-system rights
The value of a gentamicin agreement depends more on territory, dosage form, regulatory ownership, minimum purchase commitments, and manufacturing responsibility than on the active ingredient itself.
What generic launch scenarios exist for gentamicin sulfate?
Standard injectable launch
This is the most credible entry route for a manufacturer with sterile capacity. The launch can win share through competitive pricing, reliable supply, and hospital contracts. Revenue growth is usually volume-driven and margins are limited.
Ophthalmic private-label launch
This route requires less differentiation and may reach retail or institutional channels quickly. Competition is intense, and customer acquisition costs can erode margins.
Shortage-entry strategy
A supplier may enter or expand during a market shortage. This can create temporary pricing power, but FDA quality requirements and sterile manufacturing timelines limit the speed of response.
Veterinary expansion
Veterinary products can support geographic diversification and increase total volume. The strategy requires country-specific registrations and compliance with antimicrobial-use restrictions.
How does gentamicin sulfate compare with competing antibiotics?
| Attribute | Gentamicin sulfate | Newer broad-spectrum antibiotics |
|---|---|---|
| Price | Very low | Moderate to high |
| Generic competition | Extensive | Varies |
| Renal toxicity risk | Material | Often lower, product dependent |
| Monitoring burden | Higher | Often lower |
| Resistance coverage | Limited by susceptibility | Often broader for resistant pathogens |
| Hospital role | Selected serious infections | Wider use in resistant infections |
| Patent position | Mostly exhausted | May include active patents or exclusivity |
| Revenue growth | Volume-led, limited | Can be stronger before generic entry |
Gentamicin retains value where low acquisition cost and known susceptibility outweigh monitoring and toxicity concerns. It is less attractive when clinicians need broad empiric coverage or when renal safety is a priority.
What geographic markets offer the strongest opportunities?
Emerging markets offer the greatest unit-growth potential, particularly where hospital infrastructure is expanding and low-cost injectable antibiotics remain important. Mature markets offer lower growth but stronger regulatory predictability and established procurement systems.
| Region | Market outlook |
|---|---|
| United States | Stable to declining volume; intense generic competition |
| Western Europe | Stable to declining; stewardship pressure |
| Central and Eastern Europe | Moderate institutional demand |
| China | Large manufacturing and hospital market; high price competition |
| India | Strong production base and domestic demand |
| Latin America | Tender-driven growth with currency and procurement risk |
| Middle East and Africa | Volume opportunity through public procurement; supply reliability is critical |
| Veterinary global market | Stable to moderate growth, subject to regulatory controls |
What is the investment outlook for gentamicin sulfate?
Gentamicin sulfate is better viewed as a portfolio and supply-chain asset than as a high-growth pharmaceutical opportunity. Attractive investments are likely to involve:
- Sterile injectable manufacturing
- Reliable API integration
- Government and hospital procurement
- Multi-country registration
- Veterinary distribution
- Shortage-resilient supply chains
- Differentiated delivery systems
A standalone investment based on premium pricing, patent exclusivity, or rapid revenue growth is less compelling. The product’s economic value is strongest when bundled with a broader generic injectable or anti-infective portfolio.
Key Takeaways
- Gentamicin sulfate is a mature generic antibiotic with fragmented human and veterinary demand.
- Injectable products have the strongest commercial position because sterile manufacturing and hospital procurement create operational barriers.
- The core molecule has little meaningful modern patent protection.
- Biosimilar risk is irrelevant because gentamicin sulfate is a small-molecule drug.
- Paragraph IV litigation is unlikely to be a major market driver for conventional products.
- Publicly reported product-level revenue is not available across the global market.
- The base-case 2025-2030 outlook is broadly flat to modestly negative, with a projected revenue-index CAGR of about negative 1%.
- Emerging markets and veterinary products provide the strongest volume opportunities.
- Generic price erosion, antimicrobial stewardship, toxicity concerns, and substitution by newer agents limit revenue growth.
- Manufacturing reliability, tender access, and regulatory compliance are more valuable than conventional patent ownership.
FAQs
Is gentamicin sulfate still commercially viable?
Yes. It remains commercially viable as a low-cost injectable and ophthalmic antibiotic, particularly in hospital, government, and emerging-market procurement. It is not a high-growth branded opportunity.
Does gentamicin sulfate have biosimilar competition?
No. Gentamicin sulfate is a small-molecule generic drug, so competition occurs through generic approvals rather than biosimilar applications.
Which gentamicin sulfate product has the highest sales potential?
Injectable gentamicin sulfate has the highest sales potential because hospital and institutional demand is more recurring than demand for topical products. The segment also has greater manufacturing and procurement barriers.
Can a new gentamicin sulfate formulation obtain patent protection?
Yes, a genuinely novel formulation, delivery device, combination product, or manufacturing process may be patentable. Standard solutions, creams, and ophthalmic products have limited patent-based differentiation.
What is the main risk to gentamicin sulfate revenue through 2030?
The main risk is continued substitution and price erosion. Antimicrobial stewardship, renal-toxicity concerns, newer antibiotics, and aggressive generic tenders can reduce both unit demand and average selling prices.
References
-
National Library of Medicine. (2024). Gentamicin sulfate injection prescribing information. DailyMed. https://dailymed.nlm.nih.gov/
-
U.S. Food and Drug Administration. (2024a). Gentamicin sulfate injection labeling. Drugs@FDA. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2024b). Approved drug products with therapeutic equivalence evaluations. Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
-
World Health Organization. (2023). WHO model list of essential medicines: 23rd list. https://www.who.int/publications/i/item/WHO-MHP-HPS-EML-2023.02
More… ↓
