Last updated: October 7, 2026
Uroxatral is the U.S. brand name for alfuzosin hydrochloride extended-release tablets, a prescription alpha-1 adrenergic antagonist used to treat the signs and symptoms of benign prostatic hyperplasia (BPH). The product lost its principal U.S. market protection years ago. Generic alfuzosin extended-release products now determine pricing, access, and market size.
Sanofi, the original commercial sponsor, does not report Uroxatral as a separate revenue line. The brand’s commercial value declined sharply after generic entry, while the underlying alfuzosin market continued as a low-cost, mature BPH therapy. Current commercial risks are generic price erosion, substitution by tamsulosin and other alpha blockers, and limited differentiation of the 10 mg extended-release formulation.
What is Uroxatral and how is it used?
Uroxatral contains alfuzosin hydrochloride in a 10 mg extended-release tablet. The FDA approved the product for the treatment of signs and symptoms of BPH in adult men. The recommended dose is 10 mg once daily after the same meal each day. The tablet must be swallowed whole rather than crushed, chewed, or divided because of its extended-release design. [1]
| Attribute |
Uroxatral |
| Active ingredient |
Alfuzosin hydrochloride |
| Dosage form |
Extended-release tablet |
| Strength |
10 mg |
| Therapeutic area |
Benign prostatic hyperplasia |
| Drug class |
Alpha-1 adrenergic antagonist |
| Original U.S. sponsor |
Sanofi-aventis |
| FDA pathway |
New Drug Application |
| U.S. application |
NDA 021287 |
| Prescription status |
Prescription drug |
| Biosimilar exposure |
None |
| Principal competitive products |
Generic tamsulosin, silodosin, doxazosin, terazosin, dutasteride combinations |
Alfuzosin relaxes smooth muscle in the prostate and bladder neck, improving urinary flow and reducing BPH symptoms. Its clinical positioning is similar to other alpha blockers, but prescribing decisions are influenced by tolerability, orthostatic hypotension risk, drug interactions, formulary status, and physician familiarity.
When did Uroxatral lose exclusivity?
Uroxatral lost meaningful U.S. exclusivity after expiration of its primary patent and regulatory exclusivity period. Generic alfuzosin extended-release tablets subsequently entered the U.S. market, eliminating the brand’s ability to maintain premium pricing.
The relevant commercial sequence was:
| Period |
Market event |
Commercial effect |
| 2002 |
FDA approval of Uroxatral |
Sanofi obtained U.S. commercial rights for alfuzosin ER |
| Early 2000s |
Brand-only market |
Uroxatral carried branded pricing and physician promotion |
| Late 2000s to early 2010s |
Patent and regulatory protection ended |
ANDA competition became possible |
| 2010 onward |
Generic alfuzosin ER approvals |
Pharmacy substitution and price erosion accelerated |
| Current mature phase |
Generic-dominated market |
Brand demand is limited and manufacturer economics are volume-driven |
The FDA Orange Book is the primary source for listed patents, exclusivity periods, and approved generic competition. Current commercial analysis should distinguish between historical Orange Book protection and patents that remain enforceable or commercially relevant today. [2]
What patents protected Uroxatral?
Uroxatral’s protection centered on the alfuzosin extended-release formulation and related pharmaceutical composition technology. The commercially important protection was directed to controlled release of alfuzosin hydrochloride in an oral tablet rather than to a new molecular entity with long remaining life.
The patent estate had limited long-term durability because:
- Alfuzosin was an established active ingredient before the U.S. Uroxatral launch.
- Formulation protection generally expires earlier than a later-filed new chemical entity patent would.
- Generic applicants could challenge listed patents through abbreviated new drug applications.
- The product had no biologic manufacturing platform or complex delivery device that would create a substantial post-expiry barrier.
The Orange Book, FDA Drugs@FDA records, and original Uroxatral prescribing information should be used together when evaluating historical patent scope. The public record does not support treating Uroxatral as a product with a currently valuable, broad patent estate. [1,2,3]
What is the Orange Book status of Uroxatral?
Uroxatral is associated with an FDA-approved NDA for alfuzosin hydrochloride extended-release tablets. The relevant market status is mature and genericized rather than protected.
An Orange Book review should examine:
- Whether the brand NDA remains listed as active or discontinued.
- Whether any patent is currently listed against the 10 mg extended-release product.
- Whether generic products are approved under ANDAs referencing the Uroxatral NDA.
- Whether any pediatric exclusivity or other regulatory exclusivity remains.
- Whether an applicant submitted a Paragraph IV certification against a listed patent.
For a product approved more than two decades ago with multiple generic entrants, current regulatory value is normally concentrated in the approved label, manufacturing know-how, supplier relationships, and distribution economics rather than in active market exclusivity.
Were there Paragraph IV challenges to Uroxatral?
Generic alfuzosin applicants were able to use the ANDA pathway after the relevant Uroxatral protections expired or were challenged. A Paragraph IV certification would assert that a listed patent is invalid, unenforceable, or not infringed. Such a filing can trigger patent litigation and a potential 30-month stay of FDA approval under the Hatch-Waxman framework.
The public commercial record does not identify Uroxatral as a product with an ongoing, high-value Paragraph IV dispute comparable to major blockbuster medicines. Any historical litigation would have been tied to generic entry and the finite life of formulation patents. The relevant risk has therefore shifted from patent litigation to ordinary generic competition.
What is the FDA regulatory status of alfuzosin?
The FDA-approved product is an oral extended-release tablet indicated for BPH. FDA labeling warns about postural hypotension, syncope, interactions with strong CYP3A4 inhibitors, and use in patients with certain hepatic impairment. The label also warns against use with potent CYP3A4 inhibitors such as ketoconazole because of potential increases in alfuzosin exposure. [1]
Generic alfuzosin products rely on the same reference-product standards for active ingredient, dosage form, strength, route of administration, and bioequivalence. The FDA’s Approved Drug Products with Therapeutic Equivalence Evaluations, commonly called the Orange Book, is the principal source for therapeutic-equivalence ratings. [2]
There is no biosimilar pathway for Uroxatral because alfuzosin is a small-molecule drug. Competitive entry occurs through ANDAs, not through the Public Health Service Act biosimilar framework.
How large is the Uroxatral market?
Uroxatral is a small, mature market relative to newer urology products. Its addressable population is large because BPH is common among older men, but alfuzosin competes in a crowded class with inexpensive generic substitutes.
The market has four structural characteristics:
Generic substitution dominates
Generic tamsulosin is generally the strongest commercial comparator. It has broad physician familiarity, substantial historical use, and low acquisition cost. Generic alfuzosin competes primarily on clinical fit and formulary placement rather than brand differentiation.
The BPH population is stable but treatment is price-sensitive
Population aging supports underlying demand for BPH medicines. That demand does not translate into strong Uroxatral revenue because payers and pharmacies generally prefer low-cost generics.
Medical differentiation is limited
Alfuzosin is an alpha blocker, like tamsulosin, but the products differ in receptor selectivity, labeling, tolerability, and dosing considerations. Those differences can preserve prescribing in selected patients but are insufficient to support a durable branded premium after generic entry.
Combination therapy shifts value elsewhere
Patients with larger prostates or higher progression risk may receive a 5-alpha-reductase inhibitor such as finasteride or dutasteride, alone or with an alpha blocker. This reduces the strategic importance of any single alpha blocker in long-term BPH treatment.
What was Uroxatral’s financial trajectory?
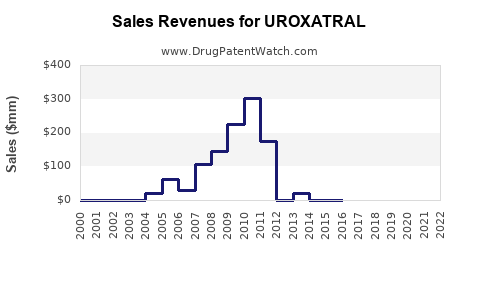
Sanofi does not publicly report Uroxatral revenue as a separately disclosed product line in its principal annual-report financial statements. Standalone historical sales figures therefore cannot be treated as audited public company data.
The financial trajectory is nevertheless clear:
| Commercial phase |
Revenue pattern |
Margin profile |
| Brand launch |
Prescription growth supported by promotion and market development |
High branded gross margin |
| Pre-generic maturity |
Volume stabilized as BPH use expanded |
Strong but increasingly competitive |
| Generic entry |
Rapid brand volume and price decline |
Margin compression |
| Post-generic phase |
Residual branded demand and generic market sales |
Low brand economics; manufacturing efficiency becomes decisive |
The greatest financial exposure occurred before and around generic entry, when Uroxatral competed as a branded prescription product. After generic substitution, the economic value of the molecule migrated from Sanofi’s brand to generic manufacturers, wholesalers, pharmacies, and payers.
Sanofi’s current financial exposure is unlikely to be material at group level. Uroxatral is not identified as a major growth product or separately reported revenue driver in the company’s public financial disclosures. [4]
Which companies compete with Uroxatral?
Competition comes from both direct alfuzosin suppliers and substitute BPH therapies.
| Competitor |
Ingredient |
Competitive position |
| Generic alfuzosin ER |
Alfuzosin |
Direct substitution for Uroxatral |
| Flomax and generic tamsulosin |
Tamsulosin |
Major alpha-blocker competitor |
| Rapaflo and generic silodosin |
Silodosin |
Selective alpha-blocker alternative |
| Cardura and generic doxazosin |
Doxazosin |
Older alpha blocker, broader blood-pressure effects |
| Hytrin and generic terazosin |
Terazosin |
Older alpha blocker |
| Avodart and generic dutasteride |
Dutasteride |
Prostate-shrinking therapy, often used in combination |
| Proscar and generic finasteride |
Finasteride |
Alternative 5-alpha-reductase inhibitor |
| Cialis |
Tadalafil |
BPH option with erectile-dysfunction overlap |
Tamsulosin is the most important direct commercial benchmark. Its large generic base and established prescribing position create a persistent ceiling on alfuzosin pricing.
What generic entry risks exist for Uroxatral?
Generic entry risk is no longer a forward-looking patent event. It is the central condition of the market.
The principal commercial risks are:
- Continued price reductions among generic alfuzosin suppliers.
- Pharmacy substitution away from the Uroxatral brand.
- Formulary exclusion or higher patient copay for the brand.
- Supply interruptions that shift volume between generic manufacturers.
- Prescriber preference for generic tamsulosin.
- Reduced promotional support for alfuzosin.
- Manufacturing concentration in active pharmaceutical ingredient and finished-dose suppliers.
For generic manufacturers, the risk is margin erosion rather than patent exclusion. Entry economics depend on supplier count, annual prescription volume, FDA compliance, product availability, and the ability to compete in pharmacy benefit manager and wholesaler channels.
What formulation and manufacturing barriers remain?
The 10 mg extended-release tablet is less complex than an injectable, inhaled product, or modified-release drug with a difficult bioequivalence profile. It still requires controlled release, acceptable dissolution performance, content uniformity, and reliable tablet manufacturing.
The remaining barriers are operational:
- Bioequivalence demonstration against the reference product.
- Controlled-release dissolution matching.
- Stable sourcing of alfuzosin hydrochloride.
- FDA-compliant manufacturing.
- Consistent supply through wholesalers and retail pharmacies.
- Managing low unit prices while maintaining quality systems.
These barriers can cause temporary supply constraints but do not create durable exclusivity comparable to a novel formulation patent.
Is there meaningful licensing or settlement value?
No major current licensing platform or strategic partnership gives Uroxatral substantial standalone value. The product is a mature small molecule with extensive generic competition and limited remaining patent leverage.
Historical commercialization was associated with Sanofi’s branded portfolio rather than with a continuing royalty-heavy licensing model. Any settlement agreements connected to generic entry would have been relevant primarily during the patent-challenge period. They do not appear to support a current premium valuation for Uroxatral.
How strong is the Uroxatral patent estate?
The current patent estate is weak from a commercial-exclusivity perspective.
| Factor |
Assessment |
| Active-ingredient exclusivity |
Expired |
| New chemical entity protection |
No current protection |
| Extended-release formulation protection |
Historically important, now expired or commercially exhausted |
| Generic availability |
Established |
| Biosimilar barrier |
Not applicable |
| Manufacturing complexity |
Moderate to low |
| Litigation leverage |
Limited |
| Current brand pricing power |
Low |
The product may retain intellectual-property relevance in historical formulation disclosures, manufacturing processes, or foreign jurisdictions. Those rights do not restore U.S. brand exclusivity once approved generic products have established therapeutic substitution.
What are the likely generic launch scenarios?
The U.S. market is already in the post-launch generic phase.
Base case
Generic alfuzosin remains available at low prices, with the brand retaining minimal residual demand. Volume tracks the overall BPH treatment population but shifts among generic suppliers.
Downside case
Additional suppliers enter or existing suppliers reduce prices. Generic margins decline, and the Uroxatral brand becomes commercially negligible.
Supply-constrained case
A manufacturing or compliance problem removes one or more suppliers. Prices may temporarily rise, but replacement supply is likely because the product is an established oral generic with no meaningful patent barrier.
Substitution case
Prescribers and payers continue shifting patients to generic tamsulosin, silodosin, or combination therapy. Alfuzosin volume declines even if the broader BPH market grows.
How does Uroxatral compare with tamsulosin?
Tamsulosin has the stronger commercial position because it has broader generic penetration, extensive prescribing familiarity, and strong formulary acceptance. Alfuzosin may remain clinically useful for patients who respond poorly to alternatives or who are managed under a physician’s preferred alpha-blocker strategy.
| Metric |
Uroxatral/alfuzosin |
Generic tamsulosin |
| Market maturity |
Mature |
Mature |
| Generic competition |
High |
Very high |
| Brand pricing power |
Minimal |
Minimal |
| Prescriber familiarity |
Established |
Very strong |
| Differentiation |
Limited clinical and dosing distinctions |
Strong class familiarity |
| Patent value |
Historical only |
Historical only |
| Current investment appeal |
Low |
Low at molecule level |
Neither molecule has the characteristics of a high-growth branded asset. Value resides in manufacturing scale, reliable supply, portfolio breadth, and channel execution.
Key Takeaways
- Uroxatral is the former Sanofi brand for alfuzosin hydrochloride 10 mg extended-release tablets.
- The product lost meaningful U.S. exclusivity years ago and is now part of a genericized BPH market.
- Generic alfuzosin, especially generic tamsulosin, determines pricing and market access.
- Sanofi does not separately disclose Uroxatral revenue, preventing a reliable standalone financial series from public company filings.
- No biosimilar risk exists because alfuzosin is a small-molecule drug.
- The patent estate has limited current commercial strength, and formulation protection no longer supports branded market power.
- Current risks are price erosion, substitution, supplier competition, and manufacturing reliability.
- Uroxatral has limited standalone licensing, litigation, or investment value in the U.S. market.
FAQs
Is Uroxatral still sold in the United States?
Uroxatral has been commercially displaced to a large extent by generic alfuzosin extended-release tablets. Prescription availability can vary by pharmacy, wholesaler, and payer.
Is alfuzosin the same as Uroxatral?
Yes. Uroxatral is the brand name, while alfuzosin hydrochloride is the active ingredient. Generic alfuzosin extended-release tablets are intended to provide the same active drug and dosage form.
Does Uroxatral have an active U.S. patent?
The historical U.S. patent protection associated with the product no longer provides meaningful market exclusivity. Generic products are established in the market.
Is Uroxatral protected by a formulation patent?
The product’s historical protection included extended-release formulation technology. That protection was relevant to generic entry but does not currently prevent broad generic competition.
What is the main commercial competitor to Uroxatral?
Generic tamsulosin is the principal commercial comparator. Silodosin, doxazosin, terazosin, finasteride, dutasteride, and tadalafil also compete in the BPH treatment market.
References
-
U.S. Food and Drug Administration. (2016). Uroxatral prescribing information: Alfuzosin hydrochloride extended-release tablets. https://www.accessdata.fda.gov/drugsatfda_docs/label/2016/021287s015lbl.pdf
-
U.S. Food and Drug Administration. (n.d.). Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
-
U.S. Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
Sanofi. (2023). Universal registration document and annual financial report 2023. https://www.sanofi.com/en/investors/financial-results-and-events/annual-reports