Last updated: July 21, 2026
STRATTERA (atomoxetine) Market Dynamics and Financial Trajectory (US and Major Markets): Demand Drivers, Competitive Pressure, and Exclusivity-Driven Revenue Outlook
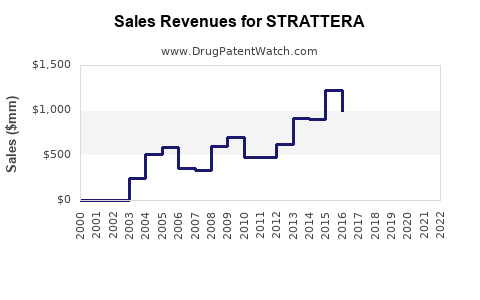
Executive summary. STRATTERA (atomoxetine hydrochloride), a non-stimulant ADHD medicine marketed by Eli Lilly in the US, tracks a mature but stable revenue profile driven by guideline positioning for patients who do not tolerate stimulants or have comorbidities that favor non-stimulant therapy. Market dynamics are shaped by (1) long-term off-patent generic penetration dynamics in the US and (2) competitive share pressure from stimulant classes and newer ADHD agents (including non-stimulant adjuncts and alpha-2 agonists). Financial trajectory depends more on class-level ADHD demand, persistence/retention, and formulary placement than on patent-driven exclusivity in most geographies, with the US now largely dominated by generic availability for atomoxetine products.
What drives STRATTERA (atomoxetine) sales in ADHD and where is demand strongest?
STRATTERA is positioned for attention-deficit/hyperactivity disorder (ADHD) in children, adolescents, and adults. Demand is influenced by:
- Non-stimulant preference and clinician guardrails. Atomoxetine is used when stimulants are less suitable due to side-effect profiles, diversion concerns, cardiovascular risk screening, comorbid anxiety, or patient/parent preference.
- Behavioral persistence. Non-stimulants often perform well for adherence when patients have stable dosing patterns and fewer “peaks and troughs” compared with some immediate-release stimulant regimens, which can affect persistence and repeat prescribing.
- Guideline alignment. Major ADHD guideline algorithms frequently include atomoxetine as a first-line option in specific patient subsets or after stimulant intolerance.
- Formulary access and payer management. Net pricing and utilization hinge on preferred brand/generic status, tiering, prior authorization requirements, and substitution rules.
Featured snippet answer: STRATTERA’s demand is driven less by patent exclusivity and more by persistent ADHD pharmacotherapy needs and non-stimulant prescribing behavior, with sales strongest where formularies keep atomoxetine accessible relative to stimulant alternatives.
Where are the main demand pockets (US vs. EU vs. ex-US)?
- United States: Market is characterized by generic availability for atomoxetine, typically compressing price and shifting revenue from branded to generic channel economics.
- Europe (major markets): Brand presence can persist longer in some countries due to different generic entry timing and tendering dynamics, but overall substitution usually limits brand revenue growth.
- Rest of world: State tenders, reimbursement rules, and regulatory listing breadth often govern penetration more than clinical differentiation.
How has generic competition changed STRATTERA’s revenue trajectory after exclusivity?
STRATTERA’s financial trajectory in the US is dominated by atomoxetine genericization. In practice, generic entry causes:
- Branded net sales decline driven by formulary substitution and pharmacist-level interchange.
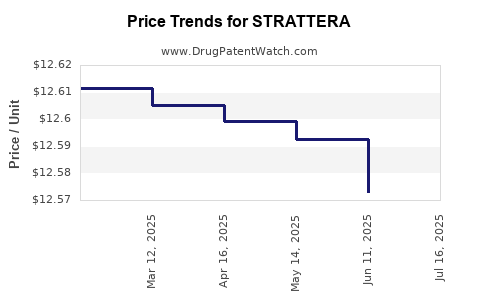
- Lower realized prices even when branded remains listed due to payer pressure.
- Channel migration toward generics and parallel importer flows, depending on country-specific regulatory frameworks.
Featured snippet answer: Generic substitution is the primary revenue headwind for STRATTERA in the US; long-term branded growth is structurally constrained once atomoxetine generics become preferred.
What is the competitive structure post-generic entry?
Atomoxetine in many markets has a typical pattern:
- Multiple generic manufacturers compete on price and supply continuity.
- Branded manufacturer marketing shifts toward maintaining differentiated contracting where possible, often via bundled coverage, prescriber education, or patient support programs, though substitution limits impact.
How does switching behavior affect volume vs. pricing?
- Volume stability can mask revenue compression. Even when prescriptions for atomoxetine persist, revenue shifts from the original brand to generics.
- Clinical inertia supports class longevity. Patients do not always switch away from atomoxetine quickly once stabilized, sustaining overall atomoxetine share even as brand revenue declines.
What is STRATTERA’s competitive landscape versus stimulants and newer ADHD therapies?
STRATTERA competes indirectly with stimulant classes (methylphenidate and amphetamine derivatives) and indirectly with other non-stimulant ADHD options such as alpha-2 agonists.
Key competitive vectors
- Efficacy and onset expectations. Many prescribers select stimulants when rapid symptom control is a priority.
- Tolerability profiles. Atomoxetine can be favored for patients where stimulant-related anxiety, insomnia, or cardiovascular effects are a concern.
- Dosing convenience and regimen design. The availability of once-daily formulations and titration patterns affects prescriber and patient adoption.
- Comorbidity fit. Atomoxetine is often used when comorbid anxiety or lack of response to stimulants drives reconsideration.
How does STRATTERA compare to stimulant economics?
- Stimulants often command strong early-line use, which pressures non-stimulant utilization.
- After generic entry, relative economics improve for atomoxetine since payer reimbursement and patient cost-sharing can make atomoxetine competitive on net basis, even if onset differentiation exists.
What is the FDA regulatory and Orange Book status impact on STRATTERA market access?
For US-specific market access dynamics, the FDA Orange Book framework governs generic entry risks and availability. The market impact can be summarized by:
- When atomoxetine patents and exclusivities expire, generics can seek approvals with Paragraph IV certifications for unexpired claims.
- Once generic entry is achieved, branded sales typically trend down as formulary substitution increases.
Featured snippet answer: The US market for STRATTERA is largely post-exclusivity and structured around Orange Book-driven generic entry that shifts revenue from brand to atomoxetine generics.
What FDA pathway mechanics matter commercially?
- NDA listing and reference product status: Atomoxetine is an established small-molecule therapy, which means generic approvals are the dominant near-term regulatory pathway for new entrants.
- Pediatric exclusivity or listed exclusivities (if applicable): Such elements can delay generic competition for certain claim sets, but once generics are on market, commercial pricing becomes the main battlefield.
Which patent expirations and exclusivity timelines historically shaped STRATTERA’s branded period?
Financial trajectory is typically defined by:
- Composition-of-matter expiration for atomoxetine (active)
- Formulation and method-of-use expirations for specific dosing regimens and indications
- Any regulatory exclusivities that extended market exclusivity beyond the primary patent term
Featured snippet answer: STRATTERA’s branded revenues are mostly a function of when composition, formulation, and regulatory exclusivities cleared; post-clearance generic entry drove the long-term revenue compression.
How to think about exclusivity vs. generic substitution
- Even with remaining patents, generics can enter if they design around method claims or use non-infringing formulations, depending on how claims are structured and enforced.
- After multiple generic competitors enter, the market becomes price-led and branded differentiation becomes limited to contracting and patient-level switching.
What generic entry risks exist for STRATTERA and how do Paragraph IV challenges affect pricing?
For a small-molecule drug already widely genericized, Paragraph IV events mainly affect:
- Timing of additional generic entrants
- Speed to price erosion
- Settlement-driven launch delays (where they occur)
Featured snippet answer: For STRATTERA, the market effect is already realized via broad generic availability; incremental Paragraph IV events primarily accelerate subsequent generic penetration and deepen price compression.
Commercial impact pattern
- Early entrants capture share at higher initial net prices.
- Later entrants force further down-tiers.
- Payers often shift atomoxetine to lower tiers once multiple equivalents exist.
What formulations and dosing strengths matter for STRATTERA market dynamics?
STRATTERA is prescribed across pediatric and adult populations and uses dosing titration. Commercially, differentiation is less about novelty and more about:
- Availability across strengths enabling prescriber titration without disruption.
- Dispensing convenience and adherence support through consistent supply.
Featured snippet answer: In practice, STRATTERA’s market dynamics depend on continuity of supply and access across required dosing strengths, rather than on formulation novelty.
Dosage-strength accessibility and substitution effects
- When dosing strengths are inconsistently stocked, prescribers can pause therapy or increase switching, which affects utilization.
- Availability across immediate and maintenance phases supports persistence, helping stabilize total atomoxetine utilization even as branded pricing declines.
How does STRATTERA’s revenue trajectory look versus other ADHD brands?
Across ADHD:
- Stimulants can maintain higher prescription volumes due to clinician preference and rapid symptom control expectations.
- Non-stimulant brands tend to retain share in tolerant patient segments but face structural pressure once generics enter and payers standardize.
Featured snippet answer: STRATTERA tends to show a mature, share-stable but revenue-compressed profile compared with patent-protected ADHD brands; growth is more sensitive to class demand than to brand switching.
Relative financial sensitivity
- Branded peak-to-decline: Most pronounced around generic milestones.
- Class-demand resilience: ADHD prevalence and persistence support overall utilization.
- Share shifts: Occur with stimulants and with payer initiatives steering to preferred molecules.
What does the competitive landscape imply for future STRATTERA profitability and market share?
If atomoxetine is fully genericized in many markets, the long-run economics likely follow:
- Low gross margin for branded products that remain listed.
- Ongoing demand at lower net prices reflecting chronic therapy patterns.
- Competitive intensity from multiple generic suppliers requiring robust manufacturing scale and quality compliance.
Featured snippet answer: Future STRATTERA profitability is constrained by generic pricing pressure; the major opportunity is maintaining utilization within the atomoxetine segment via supply reliability and formulary positioning rather than expecting premium pricing.
Business scenarios that commonly determine trajectory
- Scenario A: stable utilization, falling net price. Brand revenue declines while total prescriptions persist.
- Scenario B: consolidation among suppliers. Pricing can stabilize if supply tightens.
- Scenario C: class-level headwinds. Shifts toward other non-stimulants or stimulant intensification can reduce atomoxetine share.
Key Takeaways
- STRATTERA’s market dynamics are driven primarily by ADHD prescribing behavior for non-stimulant patients and by payer formulary access, not by premium patent pricing power in most established markets.
- Generic competition is the central determinant of branded financial decline in the US and price compression in other geographies.
- Competitive pressure from stimulant classes limits incremental share growth, but atomoxetine maintains a stable utilization base among patients who do not respond well to stimulants or tolerate them poorly.
- Future trajectory depends on supply continuity, contracting/formulary tiering, and class-level shifts within ADHD therapy.
FAQs
- Why do payers prefer generic atomoxetine over STRATTERA branded products?
- How does atomoxetine persistence differ from stimulant discontinuation patterns in ADHD?
- What happens to STRATTERA utilization during stimulant supply or formulary disruptions?
- Do patient assistance programs materially affect STRATTERA brand share in a generic market?
- How do alpha-2 agonists and other non-stimulants affect atomoxetine share over time?
References
- FDA. Orange Book: Approved Drug Products with Therapeutic Equivalence Evaluations (atomoxetine and STRATTERA listings). US Food and Drug Administration.
- Eli Lilly and Company. STRATTERA (atomoxetine hydrochloride) prescribing information and market materials.
- Peer-reviewed ADHD treatment guideline publications (US and EU) addressing non-stimulant positioning for atomoxetine.