Last updated: October 19, 2026
Amitiza, the brand name for lubiprostone, is a mature gastrointestinal drug facing generic competition, declining commercial relevance, and limited remaining patent leverage. Its principal market value has shifted from branded sales to lifecycle management, authorized-generic economics, and potential use in combination or niche gastrointestinal treatment strategies.
Lubiprostone is approved in the United States for chronic idiopathic constipation, irritable bowel syndrome with constipation in adult women, and opioid-induced constipation in adults with chronic non-cancer pain. The drug is marketed in 8-mcg and 24-mcg soft-gel capsules. Takeda Pharmaceuticals holds the U.S. and Canadian Amitiza rights, while the original development and commercial history is associated with Sucampo Pharmaceuticals.[1][2]
What is Amitiza and how large is its target market?
Amitiza is a chloride channel activator that increases intestinal fluid secretion and improves stool passage. It competes primarily with prescription secretagogues and prokinetic agents rather than with a single direct substitute.
| Market segment |
Amitiza dose |
Principal competitors |
Commercial status |
| Chronic idiopathic constipation |
24 mcg twice daily |
Linzess, Trulance, Motegrity, generic laxatives |
Large but highly competitive |
| IBS with constipation in adult women |
8 mcg twice daily |
Linzess, Trulance, OTC products |
Narrower labeled population |
| Opioid-induced constipation |
24 mcg twice daily |
Movantik, Relistor, Symproic |
Competitive specialty market |
The largest patient pool is chronic idiopathic constipation. The market includes substantial use of polyethylene glycol, stimulant laxatives, fiber products, and other low-cost over-the-counter therapies. Prescription products command higher revenue but face payer step edits and substitution pressure.
Linzess, marketed by AbbVie and Ironwood Pharmaceuticals, has had stronger commercial momentum and broader prescribing visibility. Trulance, marketed by Salix Pharmaceuticals, competes directly in chronic idiopathic constipation and IBS with constipation. Motegrity, marketed by Takeda, gives Takeda an internal competitor in the broader constipation portfolio.
When did Amitiza lose exclusivity?
Amitiza's commercial exclusivity eroded before the product lost all practical market protection. The relevant distinction is between patent expiry, Paragraph IV settlements, FDA approval of abbreviated new drug applications, and actual generic commercialization.
Amitiza exclusivity timeline
| Date |
Event |
Commercial effect |
| January 2006 |
FDA approved Amitiza for chronic idiopathic constipation |
Initial U.S. launch |
| 2008 |
FDA expanded approval to IBS with constipation in adult women |
Broader branded market |
| 2013 |
FDA approved Amitiza for opioid-induced constipation in adults with chronic non-cancer pain |
Added prescription segment |
| 2015-2017 |
Patent litigation and settlement activity involving generic applicants |
Delayed or controlled generic entry |
| 2018 |
Takeda acquired U.S. and Canadian Amitiza rights from Sucampo |
Takeda became the principal North American commercial holder |
| 2021 onward |
Contractual and legal barriers to generic entry began to weaken |
Increased launch risk |
| 2022-2024 |
FDA approvals and commercial activity involving generic lubiprostone products |
Accelerating price and volume pressure |
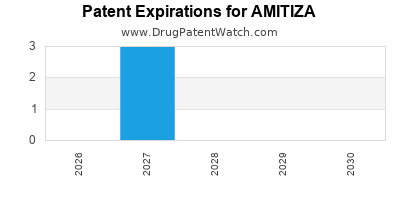
The core composition and use patents did not create a durable barrier comparable with the patent estates of newer branded gastrointestinal products. Generic entry was shaped by litigation settlements and regulatory timing, not by a long remaining period of uncontested exclusivity.
What patents protect Amitiza?
Amitiza's patent protection has centered on lubiprostone composition claims, pharmaceutical compositions, and methods of treating constipation-related disorders.
Publicly associated U.S. patents include:
| Patent |
General subject matter |
Status assessment |
| U.S. Patent No. 6,583,174 |
Lubiprostone and related prostaglandin compounds |
Expired or commercially exhausted as a primary barrier |
| U.S. Patent No. 7,795,312 |
Lubiprostone formulations or therapeutic use claims |
Historically relevant to Orange Book and litigation strategy |
| U.S. Patent No. 8,338,435 |
Additional lubiprostone use or formulation protection |
Limited remaining practical blocking value after generic settlements and approvals |
Patent status must be evaluated against the FDA Orange Book, patent-term adjustment, pediatric exclusivity, terminal disclaimers, and any delisting or litigation outcome. Patent numbers alone do not establish an enforceable current barrier.
The strongest historical protection was the combination of an approved product, limited competition, and patent litigation against ANDA applicants. The estate is materially weaker now because:
- Lubiprostone is a small molecule with no biologic manufacturing barrier.
- The core product has been commercially available for almost two decades.
- Generic manufacturers have pursued ANDA pathways.
- Several use claims are vulnerable to skinny-label strategies.
- Formulation differences are unlikely to support premium pricing without meaningful clinical or regulatory differentiation.
What is the Orange Book status of Amitiza?
Amitiza has historically been listed in the FDA Orange Book with patents associated with lubiprostone capsules and approved indications. Orange Book listings can delay ANDA approval if a listed patent remains unexpired and the applicant does not prevail in a Paragraph IV challenge.
The practical Orange Book question is no longer whether Amitiza has any listed patent history. It is whether a listed patent can prevent an approved generic from entering the market. For a mature product such as Amitiza, the answer depends on:
- Whether the patent remains unexpired.
- Whether the patent covers the generic's proposed product or only a labeled use.
- Whether the generic applicant filed Paragraph IV or Paragraph III certifications.
- Whether the patent holder filed suit within 45 days.
- Whether a settlement established a licensed entry date.
- Whether the generic received tentative or final FDA approval.
The Orange Book does not itself determine the commercial launch date. Litigation settlements, supply agreements, court judgments, and regulatory approval status also control entry.
Which companies challenged Amitiza patents?
Amitiza faced generic challenges from multiple ANDA applicants, including major generic manufacturers associated with U.S. patent litigation involving Sucampo and related rights holders. Publicly reported challengers included Par Pharmaceutical, Mylan, Teva, and Dr. Reddy's Laboratories.[3][4]
These cases followed the standard Hatch-Waxman structure:
- A generic company filed an ANDA with a Paragraph IV certification.
- The brand holder sued for patent infringement.
- The lawsuit triggered a statutory stay of FDA approval, generally for up to 30 months.
- The parties negotiated settlement terms or continued litigation.
- The generic applicant obtained approval and entered under the applicable settlement or court outcome.
Settlements often provide a defined future entry date without requiring the generic company to wait for every patent to expire. The economic result can be less severe than immediate multi-source generic competition but still materially reduce branded pricing power.
What formulation patents protect Amitiza?
Amitiza is supplied as a soft-gel capsule containing a low dose of lubiprostone. Formulation protection has focused on the composition, delivery of the active ingredient, capsule presentation, and methods of administration.
Formulation patents are commercially weaker than composition patents when:
- The ANDA applicant can use a different inactive-ingredient profile.
- The proposed product demonstrates pharmaceutical equivalence without copying a protected formulation.
- The patent claims are narrow or vulnerable to invalidity challenges.
- The approved labeling does not require the patented administration method.
A generic capsule does not need to duplicate every manufacturing process used by the brand. It generally must demonstrate pharmaceutical equivalence and bioequivalence, while complying with applicable quality and stability requirements. That limits manufacturing-related barriers.
Does Amitiza face biosimilar risk?
Amitiza does not face biosimilar risk because lubiprostone is a chemically synthesized small molecule, not a biologic. The relevant threat is conventional generic substitution through the ANDA pathway.
This distinction matters commercially:
| Risk type |
Amitiza exposure |
| Biosimilar substitution |
None |
| ANDA generic substitution |
High |
| Authorized generic competition |
Possible and commercially relevant |
| OTC substitution |
High |
| Formulary exclusion |
High |
| Manufacturing complexity |
Low to moderate |
The absence of biosimilar complexity makes generic entry structurally easier than competition against a biologic. The remaining commercial defense is brand loyalty, physician familiarity, payer positioning, supply reliability, and any differentiated indication or formulation.
How has Amitiza's financial trajectory changed?
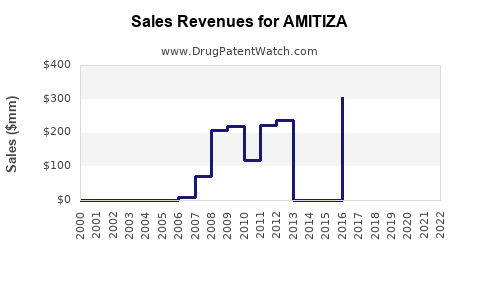
Amitiza generated meaningful revenue during its protected-branded period, but its financial trajectory has followed the standard mature-product pattern: initial adoption, indication expansion, portfolio transfer, plateau, and erosion from generic and therapeutic competition.
Sucampo reported Amitiza as its principal commercial product before the rights transaction with Takeda. The transfer gave Takeda North American control while providing Sucampo with upfront and contingent economic consideration.[2] After Takeda's acquisition of Shire, Takeda continued to report Amitiza within its gastrointestinal and mature-product portfolio.
Takeda does not consistently disclose Amitiza as a separate material revenue line in its recent annual reporting. The company reports larger products individually and groups smaller or declining products within broader categories. This prevents a reliable current-year Amitiza revenue calculation from public company filings alone.[5]
Financial trajectory by phase
| Phase |
Revenue drivers |
Margin profile |
| 2006-2012 |
First-mover position and limited prescription competition |
High branded margin |
| 2013-2017 |
Opioid-induced constipation indication and broader awareness |
Higher volume, increasing competitive pressure |
| 2018-2020 |
Takeda rights ownership and portfolio integration |
Mature-product cash generation |
| 2021-2022 |
Generic-entry preparation and payer pressure |
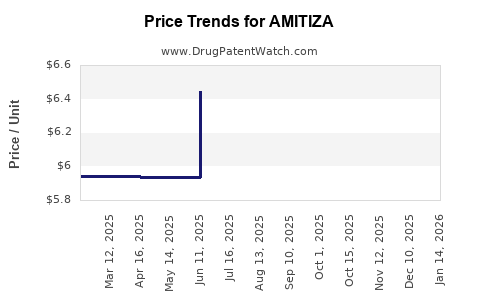
Declining net price |
| 2023 onward |
Generic substitution, lower reimbursement, and competitive switching |
Reduced branded contribution |
The financial exposure is meaningful at the product level but not central to Takeda's consolidated value after the company's post-Shire portfolio reshaping. Amitiza is unlikely to drive Takeda's valuation in the same way as Entyvio, Takhzyro, Trintellix, or other larger products.
For generic manufacturers, the opportunity is more attractive as a volume product than as a high-margin launch. The drug has established demand, multiple approved indications, and relatively straightforward dosage forms. The main risks are low net pricing, incumbent generic competition, channel concentration, and limited differentiation.
How does Amitiza compare with Linzess, Trulance, and Motegrity?
| Product |
Active ingredient |
Main mechanism |
Primary commercial strength |
| Amitiza |
Lubiprostone |
Chloride channel activation |
Long market history and multiple indications |
| Linzess |
Linaclotide |
Guanylate cyclase-C agonist |
Strong brand growth and broad constipation positioning |
| Trulance |
Plecanatide |
Guanylate cyclase-C agonist |
Direct prescription competition in CIC and IBS-C |
| Motegrity |
Prucalopride |
Selective 5-HT4 agonist |
Prokinetic positioning and Takeda commercial access |
Amitiza's advantages are clinical familiarity, multiple indications, and a long-established prescribing base. Its disadvantages are generic exposure, twice-daily administration, soft-gel manufacturing requirements, and competition from newer agents with stronger promotional support.
Linzess has generally been the more commercially powerful branded competitor. Trulance and Motegrity increase payer negotiating leverage against Amitiza. OTC laxatives constrain pricing across the entire category.
What generic launch scenarios exist for Amitiza?
The likely launch scenarios are:
Single-generic or limited-source entry
A first approved generic may capture substantial volume while preserving some branded demand. This scenario produces moderate price erosion and allows the first entrant to earn above-commodity margins temporarily.
Multi-generic competition
Several approved suppliers can rapidly reduce wholesale acquisition cost and net pricing. Pharmacy substitution generally accelerates once multiple manufacturers are available.
Authorized-generic strategy
The brand owner or a commercial partner may supply an authorized generic to retain part of the value chain. This can protect volume but usually accelerates market-wide price compression.
Brand retention in protected niches
Amitiza may retain use among patients stabilized on the product, prescribers with long experience, or plans that do not impose aggressive substitution. The retained segment is unlikely to offset broad generic erosion.
What patent litigation and settlements affect Amitiza?
Amitiza litigation has primarily involved ANDA applicants challenging patents covering lubiprostone products and approved uses. The commercial importance of the litigation was highest before generic approval and launch. Once multiple generic products receive FDA approval, the value of additional litigation declines unless a remaining patent covers a commercially necessary formulation or indication.
Settlement agreements can affect:
- Earliest permitted generic entry.
- Royalty payments.
- Authorized-generic rights.
- Supply arrangements.
- Restrictions on launch timing.
- Treatment of different dosage strengths.
- Resolution of damages claims.
A settlement does not necessarily confirm patent validity. It reflects the parties' assessment of litigation cost, expected launch timing, settlement economics, and regulatory strategy.
What FDA regulatory status applies to Amitiza?
The FDA approved Amitiza in 2006 and later expanded its label to include IBS with constipation and opioid-induced constipation.[1] Generic lubiprostone products require ANDA approval and must demonstrate pharmaceutical equivalence and bioequivalence to the relevant reference-listed drug.
The key regulatory issues are:
- Approval of both 8-mcg and 24-mcg strengths.
- Indication-specific labeling.
- Bioequivalence for soft-gel capsules.
- Manufacturing compliance and supply continuity.
- Pediatric exclusivity and labeling obligations.
- Orange Book patent certifications.
Because Amitiza is a small-molecule drug with an established reference product, the regulatory pathway is substantially less complex than a biologic license application or biosimilar application.
How strong is the Amitiza patent estate?
The Amitiza patent estate is weak to moderate as a current commercial defense and stronger as a historical litigation asset.
| Factor |
Assessment |
| Core composition protection |
Largely exhausted or commercially weakened |
| Formulation protection |
Potentially relevant but narrow |
| Method-of-use protection |
Vulnerable to skinny-label strategies |
| Manufacturing protection |
Limited barrier for standard generic capsules |
| Regulatory exclusivity |
Expired |
| Generic litigation risk |
High |
| Biosimilar risk |
Not applicable |
| Geographic protection |
Strongest in the U.S. during the branded period; variable elsewhere |
The estate can still support settlement value where claims remain listed or where a generic applicant faces litigation cost. It is unlikely to support durable premium pricing against multiple approved generic suppliers.
What is Amitiza's commercial outlook and revenue exposure?
Amitiza's forward outlook is defensive rather than growth-oriented. The brand's value depends on:
- Retaining a stable prescriber base.
- Maintaining reimbursement for patients who do not switch.
- Avoiding supply interruptions.
- Managing generic competition.
- Preserving selected indication-specific demand.
- Controlling manufacturing and distribution costs.
For Takeda, Amitiza represents a mature-product revenue stream with limited strategic importance relative to the company's growth portfolio. For generic manufacturers, it offers a conventional post-exclusivity opportunity with established demand but limited long-term pricing power.
The most likely financial trajectory is continued branded decline, partial volume retention, and compression of net price. A sharp recovery would require a new formulation, a materially differentiated delivery system, a new indication, or a commercial transaction that changes channel economics.
Key Takeaways
- Amitiza is lubiprostone, a mature small-molecule treatment for chronic idiopathic constipation, IBS with constipation, and opioid-induced constipation.
- Takeda controls the U.S. and Canadian rights, following its transaction with Sucampo.
- The product's regulatory exclusivity has expired, and generic competition is the principal commercial threat.
- Amitiza faces conventional ANDA competition, not biosimilar competition.
- Its patent estate has historical litigation value but limited ability to sustain long-term branded pricing.
- Linzess is the strongest branded competitive benchmark, while Trulance, Motegrity, and OTC laxatives add pressure.
- Takeda does not separately disclose current Amitiza revenue in a way that supports a reliable product-level forecast.
- The expected financial trajectory is declining branded revenue, lower net pricing, and reduced strategic importance.
FAQs About Amitiza Patents, Generics, and Market Value
Is Amitiza still a branded drug?
Yes. Amitiza remains the branded reference product for lubiprostone, but its commercial position is reduced by generic availability and mature-market competition.
Can pharmacies automatically substitute generic lubiprostone for Amitiza?
Substitution depends on state pharmacy law, payer rules, product equivalence, and whether the prescription permits substitution. FDA therapeutic-equivalence designations and payer formulary policies influence actual dispensing.
Does Amitiza have pediatric exclusivity?
Amitiza's principal commercial indications are adult indications. Any historical pediatric exclusivity or pediatric labeling period must be evaluated against the applicable FDA approval and Orange Book records rather than assumed from the current label.
Is lubiprostone difficult for generic manufacturers to produce?
The drug is not subject to biologic manufacturing complexity, but soft-gel capsule production, low-dose uniformity, stability, dissolution, and quality-control requirements still create operational obligations.
Could Amitiza regain growth through a new indication?
Growth would require a clinically meaningful new indication, differentiated formulation, or improved administration profile. Expansion within the existing constipation market would likely shift prescribing rather than create a large new market.
References
-
U.S. Food and Drug Administration. (2006). Amitiza (lubiprostone) prescribing information. FDA.
-
Sucampo Pharmaceuticals, Inc. (2018). Agreement with Takeda Pharmaceuticals for U.S. and Canadian Amitiza rights. Company disclosure.
-
U.S. District Court for the District of Delaware. (2015-2017). Sucampo Pharmaceuticals, Inc. v. Par Pharmaceutical, Inc., Mylan Pharmaceuticals Inc., Teva Pharmaceuticals USA, Inc., and related cases. Court records.
-
U.S. Food and Drug Administration. (2022-2024). Approved drug products with therapeutic equivalence evaluations: Lubiprostone capsules. FDA Orange Book.
-
Takeda Pharmaceutical Company Limited. (2019-2024). Annual report and integrated report. Tokyo: Takeda Pharmaceutical Company Limited.