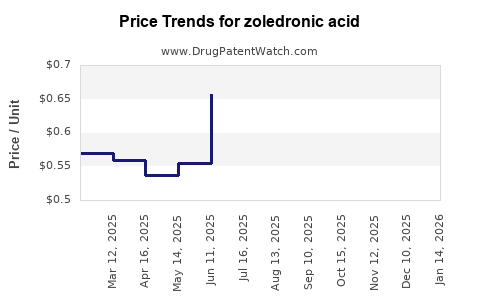
Last updated: October 30, 2026
Zoledronic acid is a mature, multisource injectable bisphosphonate with declining branded revenue, persistent clinical demand, and low average selling prices. The molecule is marketed primarily as Zometa for oncology indications and Reclast for osteoporosis, alongside numerous generic products. Its commercial value has shifted from brand pricing and patent protection to hospital contracts, supply reliability, manufacturing efficiency, and indication-specific volume.
What is the current market position of zoledronic acid?
Zoledronic acid remains one of the most widely used intravenous bisphosphonates. It is administered as an intravenous infusion and is used in two major commercial segments:
| Segment |
Principal brand |
Main indications |
Typical administration |
| Oncology |
Zometa |
Hypercalcemia of malignancy; multiple myeloma; bone metastases from solid tumors |
Repeated intravenous dosing |
| Osteoporosis |
Reclast |
Postmenopausal osteoporosis, male osteoporosis, glucocorticoid-induced osteoporosis, Paget's disease |
Usually once yearly or once per treatment course |
| Generic market |
Zoledronic acid injection |
Same FDA-approved indications, depending on labeling |
Hospital, infusion-center, and outpatient use |
Novartis developed and commercialized Zometa and Reclast. The products are now exposed to generic competition in the United States and other major markets. FDA-approved generic zoledronic acid injections have replaced much of the branded volume in price-sensitive channels.[1]
The market is no longer a conventional branded pharmaceutical growth market. It is a mature injectable-generic market with stable medical need, recurring osteoporosis dosing, oncology utilization, and significant price competition.
How large is the zoledronic acid market?
Published market estimates vary because analysts define the market differently. Some include only branded and generic zoledronic acid products. Others combine all bisphosphonates, oncology bone-modifying agents, or osteoporosis therapies. A single global figure therefore has limited analytical value.
The more useful market view is segment-based:
| Market driver |
Effect on zoledronic acid |
| Generic entry |
Reduces price and branded revenue |
| Annual osteoporosis dosing |
Supports recurring outpatient volume |
| Oncology bone metastasis treatment |
Maintains hospital and infusion-center demand |
| Multiple myeloma treatment |
Sustains use, although denosumab and modern oncology regimens compete |
| Denosumab |
Limits growth in cancer and osteoporosis indications |
| Hospital purchasing |
Rewards low acquisition cost and reliable supply |
| Renal monitoring requirements |
Restricts use in some patients |
| Long treatment intervals |
Supports adherence but limits prescription frequency |
| Drug shortages |
Can temporarily improve demand for alternative suppliers |
Zoledronic acid’s market value is concentrated in the United States, Europe, Japan, China, and other countries with established oncology and osteoporosis treatment infrastructure. Emerging markets add volume but generally produce lower revenue per dose.
The product’s financial profile is therefore more closely tied to treated-patient volume and tender share than to prescription growth alone.
What is the financial trajectory of Zometa and Reclast?
The branded financial trajectory has followed a conventional loss-of-exclusivity pattern.
Zometa
Zometa became a major oncology product after its FDA approval in 2001. It replaced or supplemented pamidronate in the treatment of hypercalcemia of malignancy and skeletal complications associated with multiple myeloma and solid-tumor bone metastases.[2]
Sales expanded before generic competition because the drug offered:
- Potent inhibition of osteoclast-mediated bone resorption
- Shorter infusion time than pamidronate in many treatment settings
- Broad oncology adoption
- Use across multiple tumor types
- Integration into supportive-care protocols
Generic competition materially changed the economics. Once regulatory exclusivity and key patent protection ended, hospitals and distributors had multiple sources for the same active ingredient. Novartis could no longer preserve premium pricing across the full oncology market.
Reclast
Reclast entered the osteoporosis market as a once-yearly intravenous bisphosphonate. Its commercial proposition was different from Zometa: the product reduced dosing frequency and avoided daily or weekly oral administration.[3]
Reclast remained commercially relevant because it addresses patients who:
- Have difficulty adhering to oral therapy
- Have gastrointestinal intolerance to oral bisphosphonates
- Prefer annual administration
- Have contraindications or practical barriers to oral treatment
- Are treated through infusion centers or specialty practices
Generic entry reduced the value of the brand, but the annual dosing model supports recurring utilization. Generic manufacturers can compete for volume without needing to build a differentiated clinical franchise.
Financial progression
| Period |
Commercial condition |
Revenue implication |
| 2001-2008 |
Zometa expands in oncology; Reclast establishes osteoporosis position |
Strong branded growth |
| 2009-2012 |
Broader use but increasing patent and generic pressure |
Peak or near-peak brand economics |
| 2013 onward |
Generic zoledronic acid expands in major markets |
Sharp branded price and share erosion |
| Current market |
Mature generic injectable with residual branded use |
Low brand growth; stable or modestly growing unit demand |
Novartis no longer presents Zometa and Reclast as major standalone growth drivers in the way it reports its leading innovative medicines. This reflects product maturity, generic substitution, and portfolio prioritization rather than the disappearance of clinical demand.[4]
The overall zoledronic acid market can still produce meaningful aggregate revenue across manufacturers. That revenue is distributed across multiple suppliers and is substantially lower per dose than during the branded period.
When did zoledronic acid lose exclusivity?
Zoledronic acid lost effective market exclusivity in the United States through the expiration of core patent and regulatory protections followed by generic approvals. The exact timing differed by product, indication, formulation, and jurisdiction.
| Protection category |
Current status |
| Active-ingredient patent protection |
Expired |
| Original NDA exclusivity |
Expired |
| Pediatric exclusivity |
Expired |
| U.S. generic entry |
Established |
| European market protection |
Expired or no longer commercially decisive |
| Patent-based branded pricing |
No longer material |
| Regulatory exclusivity for new indications |
Expired for original indications |
The relevant commercial event is not only the legal expiration date. Generic price erosion depends on the number of approved suppliers, hospital formulary adoption, distribution arrangements, and supply reliability.
For zoledronic acid, generic erosion has been established for years. Any remaining branded sales are associated with physician familiarity, institutional contracts, reimbursement dynamics, patient continuity, or manufacturer-specific distribution rather than meaningful patent exclusivity.
What patents protect zoledronic acid?
The original zoledronic acid patent estate protected the active compound and related pharmaceutical uses. Those protections are no longer a significant barrier to generic entry in the major markets.
The commercially important intellectual-property categories were:
- The zoledronic acid chemical compound.
- Pharmaceutical compositions containing zoledronic acid.
- Treatment of hypercalcemia and skeletal complications.
- Osteoporosis and Paget's disease treatment methods.
- Dosing schedules and infusion-related use.
- Manufacturing and formulation processes.
Method-of-use patents historically extended commercial protection around specific indications and dosing regimens. They did not preserve broad market exclusivity once the principal compound and product protections had expired.
Are formulation patents still important?
Formulation and manufacturing patents can matter to individual suppliers, but they do not recreate broad exclusivity for zoledronic acid. The product is an aqueous sterile injectable with established formulation requirements. A generic manufacturer can generally avoid a narrow formulation claim through a non-infringing composition or process.
Potentially relevant technical barriers include:
- Sterile manufacturing capacity
- Aseptic filling
- Control of particulate matter
- pH and stability management
- Container-closure integrity
- Compatibility with infusion systems
- Control of degradation products
- Validated production of low-concentration presentations
These requirements create execution risk, but they are not equivalent to patent protection for the molecule.
What is the Orange Book status of zoledronic acid?
The FDA Orange Book lists approved drug products and patent information for approved products. Zometa and Reclast are associated with FDA-approved new drug applications, while generic products are approved through abbreviated new drug applications.
The principal U.S. regulatory identifiers are:
| Product |
Sponsor/originator |
FDA application |
Dosage form |
| Zometa |
Novartis |
NDA 021223 |
Intravenous injection/infusion |
| Reclast |
Novartis |
NDA 021817 |
Intravenous infusion |
Current commercial analysis should distinguish between:
- Originator NDA listings
- Generic ANDA approvals
- Any remaining listed patents
- Patent delistings or expired entries
- Indication-specific labeling
- Product-specific approval status
There is no meaningful current Orange Book patent barrier preventing generic zoledronic acid entry. The central commercial issue is generic competition, not Paragraph IV litigation against an unexpired composition patent.
Have generic manufacturers filed Paragraph IV challenges?
Paragraph IV certifications are most important before or during the initial generic-entry period, when an ANDA applicant challenges an unexpired listed patent. For zoledronic acid, the market is already mature and generic supply is established.
The principal commercial conclusion is:
- Paragraph IV litigation is not the current market-control mechanism.
- The major originator patents no longer support a protected branded market.
- Generic manufacturers compete through approval timing, price, supply, and contracting.
- Any later patent dispute would more likely concern a narrow formulation, manufacturing process, or specific product presentation.
The absence of a current broad Paragraph IV barrier means generic manufacturers can participate without waiting for a future patent cliff. Market share depends on procurement and supply execution.
What is the FDA regulatory status of zoledronic acid?
Zoledronic acid is FDA-approved for multiple indications, but dosing and patient selection differ materially by product and disease.
Zometa indications
The FDA label includes:
- Hypercalcemia of malignancy
- Multiple myeloma
- Bone metastases from solid tumors, including breast and prostate cancer settings under the approved labeling framework[2]
Reclast indications
The FDA label includes:
- Treatment and prevention of postmenopausal osteoporosis
- Osteoporosis in men
- Glucocorticoid-induced osteoporosis
- Paget's disease of bone[3]
Renal safety is a central regulatory and commercial consideration. Creatinine clearance assessment, hydration, infusion parameters, and contraindications are important components of the product labels. Reclast carries a contraindication for patients with creatinine clearance below the specified threshold in the FDA labeling.[3]
These requirements limit substitution into some patient populations and increase the value of clinical workflow familiarity.
How does zoledronic acid compare with denosumab?
Denosumab is the most important modern competitor in the bone-health market. It is marketed as Prolia for osteoporosis and Xgeva for oncology-related skeletal events.
| Attribute |
Zoledronic acid |
Denosumab |
| Drug class |
Bisphosphonate |
RANK ligand inhibitor |
| Administration |
Intravenous infusion |
Subcutaneous injection |
| Osteoporosis schedule |
Usually once yearly |
Usually every six months |
| Oncology schedule |
Periodic intravenous dosing |
Usually every four weeks, with some de-escalation schedules |
| Generic competition |
Extensive |
Limited or absent in major markets for many uses |
| Renal considerations |
Important; dosing and eligibility constraints |
Different renal and hypocalcemia risk profile |
| Acquisition cost |
Generally low after generic entry |
Generally higher |
| Administration burden |
Infusion-center visit |
Injection or office administration |
| Patent strength |
Weak for market exclusion |
Stronger current branded protection |
| Commercial strategy |
Low-cost, high-volume |
Differentiated branded therapy |
Zoledronic acid has a cost advantage, particularly in institutional settings. Denosumab has advantages in patients for whom intravenous bisphosphonate treatment is unsuitable and in certain oncology treatment pathways. Clinical selection depends on renal function, fracture risk, tumor type, prior therapy, hypocalcemia risk, treatment duration, and payer policy.
Which companies are challenging the zoledronic acid market?
The market includes the originator and multiple generic suppliers. The supplier set varies by country and may change because of discontinuations, acquisitions, and shortages.
Generic competition has historically included large multinational and specialty injectable manufacturers such as:
- Teva
- Fresenius Kabi
- Hikma
- Dr. Reddy's Laboratories
- Sandoz
- Sun Pharmaceutical
- Accord Healthcare
- Other regional injectable manufacturers
The relevant competitive metrics are:
- Number of active approved suppliers.
- National and regional wholesaler coverage.
- Contract access to hospitals and group purchasing organizations.
- Ability to maintain sterile supply.
- Strength of regulatory compliance history.
- Product presentation and vial availability.
- Price competitiveness.
- Ability to support oncology and infusion-center demand.
A manufacturer with a lower list price but unreliable supply can lose share to a higher-priced supplier. Injectable markets place a premium on continuity because hospitals may have limited substitutes during a shortage.
What manufacturing and intellectual-property barriers affect zoledronic acid?
Zoledronic acid is chemically mature, but sterile injectable production has operational barriers. The key risks are manufacturing rather than molecule-level IP.
Manufacturing barriers
- Reliable API sourcing
- Sterile formulation and filling
- Validation of aseptic processes
- Low particulate burden
- Shelf-life stability
- Inspection readiness
- Capacity for multiple vial sizes
- Quality control for infusion products
- Distribution under controlled storage conditions
The product does not require biologic manufacturing, cell culture, cold-chain complexity comparable to monoclonal antibodies, or device-enabled delivery. This keeps the technical barrier below that of biologics and complex injectables.
IP barriers
Remaining IP risk is more likely to arise from:
- Process claims
- Specific concentrations
- Container systems
- Manufacturing improvements
- Narrow dosing methods
- Jurisdiction-specific patent rights
Those rights can affect an individual generic manufacturer but are unlikely to restore originator-wide exclusivity.
What generic launch scenarios exist for zoledronic acid?
Because generic entry is already established, future scenarios concern market reshaping rather than a single launch event.
| Scenario |
Market outcome |
| Stable multisource supply |
Continued low pricing and gradual volume growth |
| Supplier consolidation |
Higher shortage risk and potential price stabilization |
| Manufacturing disruption |
Temporary price increases and share shifts |
| Increased osteoporosis infusion use |
Higher unit volume, limited revenue growth |
| Greater denosumab adoption |
Reduced oncology and osteoporosis share |
| Payer-driven generic substitution |
Further branded erosion |
| New dosing evidence |
Possible shift in treatment intervals and utilization |
| Regulatory or safety changes |
Potential restriction in renal-risk populations |
The most likely base case is stable or modestly increasing volume with flat-to-declining market value per dose. Revenue growth would require either increased treatment volume, supply disruption among competitors, or expansion into underpenetrated markets.
What is the revenue exposure for manufacturers?
Zoledronic acid revenue exposure differs sharply by business model.
Originator exposure
Novartis has low strategic dependence on zoledronic acid relative to its current oncology, immunology, cardiovascular, and neuroscience portfolio. Zometa and Reclast remain recognized brands but are no longer central growth assets.
Generic manufacturer exposure
For generic companies, zoledronic acid is typically a portfolio product rather than a major standalone franchise. Profitability depends on:
- Manufacturing cost
- Contract price
- Market concentration
- Procurement discounts
- Inventory turnover
- Shortage conditions
- Regulatory compliance costs
Generic revenues can be attractive when a supplier has limited competition or reliable capacity. They can become unattractive when several manufacturers compete for the same hospital contracts.
Health-system exposure
Hospitals and infusion centers generally benefit from generic availability because acquisition cost is lower than branded alternatives. However, switching costs arise from:
- Formulary review
- Pharmacy-and-therapeutics approval
- Inventory qualification
- Administration protocols
- Supplier continuity
- Reimbursement coding and billing
How strong is the zoledronic acid patent estate?
The current patent estate is weak as a market-exclusion tool and strong only in a historical sense.
| Patent-estate factor |
Assessment |
| Compound protection |
Expired |
| Broad product exclusivity |
Expired |
| Method-of-use exclusivity |
No longer commercially decisive |
| Formulation protection |
Narrow and supplier-specific |
| Generic entry barrier |
Low |
| Biosimilar barrier |
Not applicable |
| Manufacturing complexity |
Moderate |
| Litigation risk |
Low for broad market access |
| Pricing power |
Minimal for the originator |
| Long-term commercial durability |
Dependent on volume and supply |
Zoledronic acid remains commercially durable because demand persists after patent expiry. That durability should not be confused with strong exclusivity. The molecule has clinical utility but limited ability to command premium pricing.
Is there biosimilar risk for zoledronic acid?
No. Zoledronic acid is a small-molecule bisphosphonate, not a biologic. Its competitive threat comes from conventional generic drugs approved through the ANDA pathway, not biosimilars under the Public Health Service Act.
This distinction has practical consequences:
- Generic approval is generally simpler than biosimilar approval.
- Interchangeability and substitution rules differ.
- Manufacturing requirements are less complex than for biologics.
- Price erosion can occur more rapidly after multisource entry.
- Originator lifecycle-management options are limited.
What licensing deals affect zoledronic acid?
No current licensing transaction appears to control the global commercial market for zoledronic acid. The original commercial rights were associated with Novartis and its predecessor companies. Later commercial activity has primarily involved generic manufacturing, distribution, and regional commercialization arrangements.
Licensing is therefore less important than:
- ANDA ownership
- Contract manufacturing
- Regional marketing rights
- Wholesaler access
- Hospital tenders
- Supply agreements
A new licensing deal would likely concern a regional generic, a specialty injectable portfolio, or a manufacturing arrangement rather than a breakthrough platform or exclusivity transfer.
What patent litigation affects zoledronic acid?
The principal historical legal disputes involved patent protection, generic entry, and indication-specific use. The current market does not depend on an unresolved, broad patent dispute that could reestablish Zometa or Reclast exclusivity.
Current litigation risk is more likely to involve:
- Product liability
- Renal safety
- Osteonecrosis of the jaw
- Manufacturing quality
- Labeling
- Distribution contracts
- Procurement disputes
- Supply obligations
Osteonecrosis of the jaw and renal impairment remain important risk-management issues in oncology and osteoporosis use. These issues can affect prescribing and monitoring but do not create patent-based competitive protection.
Key Takeaways
- Zoledronic acid is a mature, multisource injectable generic.
- Zometa and Reclast have lost their historical branded pricing power.
- The market has persistent demand in oncology and osteoporosis.
- Generic competition, hospital tenders, and supply reliability determine commercial performance.
- The current patent estate does not provide broad market exclusivity.
- Formulation and manufacturing IP may protect individual suppliers but does not block generic access.
- Denosumab is the principal branded competitor.
- Zoledronic acid has no biosimilar pathway because it is a small molecule.
- Revenue is likely to remain stable to modestly declining in value, even where unit volume is stable or rising.
- The strongest commercial opportunity is in efficient sterile manufacturing and reliable institutional supply, not patent-based pricing.
FAQs
Is zoledronic acid still profitable after generic entry?
Yes, but profitability depends on manufacturing efficiency, hospital contracts, supplier concentration, and supply reliability. Margins are generally lower than during the branded period.
Does Reclast still have market exclusivity?
No broad market exclusivity remains. Generic zoledronic acid products compete with Reclast in the applicable approved indications.
Can zoledronic acid replace denosumab?
Not universally. The products differ in mechanism, administration, renal considerations, hypocalcemia risk, dosing schedules, and patient selection.
Is zoledronic acid a high-growth pharmaceutical product?
No. It is a mature product with stable clinical demand, recurring osteoporosis use, and limited pricing growth.
Which market has greater commercial value for zoledronic acid, oncology or osteoporosis?
Oncology historically generated the stronger branded franchise through Zometa. Osteoporosis provides recurring annual treatment volume through Reclast and generic products. Current value depends on local reimbursement and institutional purchasing conditions.
References
-
U.S. Food and Drug Administration. (n.d.). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2023). Zometa (zoledronic acid) prescribing information. Novartis Pharmaceuticals Corporation.
-
U.S. Food and Drug Administration. (2023). Reclast (zoledronic acid) prescribing information. Novartis Pharmaceuticals Corporation.
-
Novartis AG. (2013). Annual report 2013. https://www.novartis.com/investors/financial-data/annual-reporting
-
Novartis AG. (2015). Annual report 2015. https://www.novartis.com/investors/financial-data/annual-reporting