Last updated: September 7, 2026
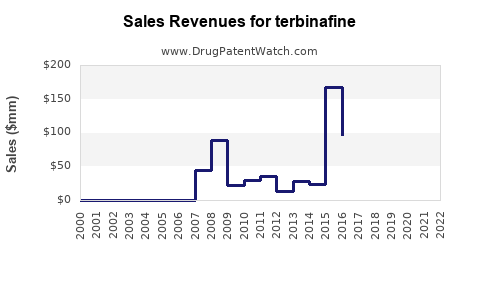
Terbinafine is a mature, low-cost antifungal with limited remaining pharmaceutical exclusivity. The original Lamisil franchise generated more than $1 billion annually at its peak, but revenue shifted sharply after generic entry for oral tablets and the expansion of low-priced topical products. Current value is concentrated in high-volume generic tablets, over-the-counter topical creams and sprays, private-label products, and regional brands rather than in the original innovator franchise.
The commercial outlook is stable but low growth. Oral terbinafine remains a standard treatment for onychomycosis and dermatophyte infections, while topical terbinafine competes in a fragmented antifungal market. Patent risk is low in the United States for the active ingredient. Manufacturing scale, retail distribution, brand recognition, and regulatory compliance are more important barriers than enforceable molecule patents.
What is terbinafine and which products generate revenue?
Terbinafine is an allylamine antifungal that inhibits squalene epoxidase, disrupting fungal cell membranes. It is marketed in oral and topical forms, principally as terbinafine hydrochloride.
| Product category |
Common dosage form |
Principal use |
Market position |
| Oral terbinafine |
250 mg tablet |
Onychomycosis and severe dermatophyte infections |
Prescription generic |
| Topical terbinafine |
1% cream, gel, solution or spray |
Tinea pedis, tinea corporis and tinea cruris |
Generic, OTC and private label |
| Original brand |
Lamisil |
Oral and topical antifungal treatment |
Mature or discontinued innovator franchise in many markets |
| Combination products |
Creams and dermatology formulations |
Fungal infections with additional active ingredients |
Regionally variable |
The U.S. Food and Drug Administration approved Lamisil tablets for oral treatment of toenail and fingernail fungal infections in 1996. The approved oral dose is generally 250 mg once daily, with treatment duration depending on the infected nail and clinical indication (FDA, 2023).
Topical terbinafine is sold under multiple brands and store labels. In the United States, most topical products are positioned through prescription generic channels or OTC retail channels. In Europe and other markets, the Lamisil name has remained commercially relevant in topical products even after loss of prescription exclusivity.
When did terbinafine lose exclusivity?
Terbinafine’s core compound and original product exclusivity expired years ago. Generic oral products entered the U.S. market in the 2000s, eliminating the original brand’s ability to sustain premium pricing for tablets.
The key commercial sequence was:
| Period |
Event |
Commercial effect |
| 1996 |
FDA approval of Lamisil tablets |
Creation of the original oral franchise |
| Late 1990s to early 2000s |
Expansion of oral and topical use |
Rapid prescription and consumer adoption |
| Early to mid-2000s |
Expiration of core patent and regulatory protections |
Generic development became commercially viable |
| 2007 onward |
Broad generic availability in the United States |
Major price compression for oral tablets |
| 2010s |
Expansion of private-label and OTC topical products |
Further fragmentation of brand demand |
| 2020s |
Mature generic and consumer-health market |
Stable unit demand with limited pricing power |
The exact effective date of generic entry differed by product, jurisdiction and dosage form. Pediatric exclusivity, patent-term adjustments and regulatory exclusivity can affect individual products, but they did not preserve a material long-term monopoly for oral terbinafine.
What patents protect terbinafine products?
The original patent estate covered the terbinafine compound, related allylamine chemistry, pharmaceutical compositions and methods of treating fungal infections. Those rights were filed primarily in the 1980s and early 1990s and have expired in the principal commercial markets.
Current U.S. commercial protection is not based on an active compound patent. Generic manufacturers can market terbinafine hydrochloride tablets after satisfying FDA approval requirements, including demonstration of pharmaceutical equivalence and bioequivalence.
What is the Orange Book status of terbinafine?
The FDA Orange Book historically listed Lamisil as the reference product for oral terbinafine tablets. Generic manufacturers relied on abbreviated new drug applications referencing the branded product. The relevant patents are no longer a meaningful barrier to ordinary generic entry.
For current diligence, the commercially important Orange Book questions are:
- Whether the reference product remains listed as active or has been discontinued.
- Which ANDAs remain approved.
- Whether any formulation or method-of-use patent is listed against a specific branded presentation.
- Whether the intended generic has a therapeutic-equivalence rating of AB.
For standard 250 mg oral tablets, the commercial market is overwhelmingly generic. Orange Book status does not create a practical barrier comparable with an active patent estate for a recently launched drug (FDA, 2024a).
How many patents cover terbinafine today?
No active U.S. patent portfolio materially protects the basic terbinafine molecule. Historical patents covered:
- The terbinafine active ingredient and related chemical compounds.
- Pharmaceutical compositions containing terbinafine.
- Oral tablet formulations.
- Topical creams and dermatological delivery systems.
- Methods for treating fungal infections.
Any surviving jurisdiction-specific rights would need to be evaluated by product, country and claim scope. They do not change the broad market conclusion: terbinafine is an off-patent small molecule with a mature generic supply base.
What formulations are protected by terbinafine patents?
Historical formulation claims could cover excipient combinations, topical vehicles, particle characteristics, delivery systems or specific manufacturing methods. These claims have limited current commercial importance because generic manufacturers can use non-infringing formulations and because the core therapeutic ingredient is widely available.
A company seeking to launch a differentiated terbinafine product could pursue protection for:
- Extended-release oral dosage forms.
- Improved topical penetration systems.
- Nail-lacquer or film-forming delivery systems.
- Combination antifungal products.
- Reduced-duration treatment regimens.
- Formulations designed to reduce systemic exposure.
These products would face a higher regulatory and clinical burden than a conventional generic tablet or cream.
Are there Paragraph IV challenges to terbinafine?
Paragraph IV litigation is no longer a central market issue for conventional terbinafine tablets. The principal patent barriers expired before the current mature generic market developed, reducing the value of challenging a live patent estate.
Historical ANDA applicants may have used Paragraph IV certifications against listed patents, but the competitive outcome is now determined by approval status, manufacturing economics and channel access. New entrants are more likely to rely on Paragraph III or no-challenge strategies where no enforceable listed patent blocks approval.
The absence of material current Paragraph IV activity does not eliminate product liability, labeling or regulatory risks. Oral terbinafine has important safety considerations, including hepatotoxicity warnings and drug-interaction concerns, which can affect prescribing and monitoring requirements (FDA, 2023).
Which companies compete in the terbinafine market?
The market is fragmented across generic pharmaceutical companies, consumer-health companies, specialty dermatology suppliers and regional distributors. Competition varies by geography and dosage form.
Oral tablet competition
Generic oral terbinafine is supplied by manufacturers that compete primarily on:
- FDA approval and manufacturing reliability.
- Wholesale acquisition cost and contract pricing.
- Pharmacy benefit manager access.
- Availability during supply disruptions.
- Tablet quality and packaging.
- Distribution through wholesalers and retail pharmacies.
Because the active ingredient is mature and clinically familiar, physician demand is less sensitive to brand. Pharmacies typically dispense the lowest-cost therapeutically equivalent product available under payer and inventory rules.
Topical competition
Topical terbinafine competes with clotrimazole, miconazole, butenafine, tolnaftate and prescription formulations of other antifungals. Lamisil retains brand recognition, but generic creams and store brands place a ceiling on price.
Consumer-health competition depends on shelf placement, digital retail visibility, packaging, advertising and the perceived speed of symptom relief. The active ingredient alone does not create durable pricing power.
What is the financial trajectory of terbinafine?
Terbinafine followed the standard lifecycle of a high-value branded drug:
- Rapid growth after launch.
- Expansion into multiple indications and dosage forms.
- Peak revenue during the branded period.
- Sharp erosion after generic entry.
- Stable, high-volume, low-price maturity.
Novartis reported Lamisil as a major pharmaceutical product during the brand’s peak period. Historical annual reports placed Lamisil among the company’s billion-dollar products, supported by oral treatment of onychomycosis and strong global brand recognition (Novartis, 2003).
After generic entry, the financial model changed. Brand revenue declined as payers and pharmacies substituted generic tablets. Topical products retained some consumer value because brand recognition and retail presentation can support a premium, but that premium is narrower than the original prescription franchise.
| Financial phase |
Revenue driver |
Margin profile |
| Branded launch |
Prescription growth and physician adoption |
High |
| Brand expansion |
Global sales, new formulations and consumer recognition |
High |
| Generic entry |
Volume retained, price reduced |
Falling |
| Mature generic phase |
Manufacturing scale and contracts |
Low to moderate |
| Mature OTC phase |
Brand, distribution and shelf presence |
Variable |
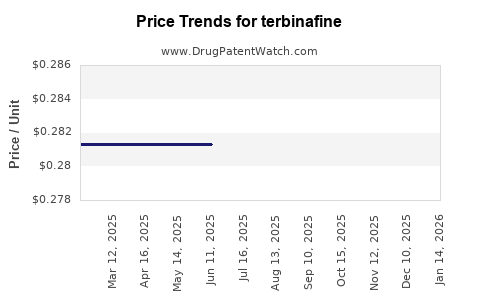
Current molecule-level revenue is difficult to isolate because terbinafine is sold under multiple generic labels, private-label products and regional brands. Public company filings generally report broader portfolios rather than terbinafine-specific sales. The original Lamisil revenue stream therefore should not be treated as a proxy for current terbinafine market value.
What is the current generic launch opportunity?
A conventional terbinafine tablet launch has low clinical risk but limited pricing power. The main opportunity is operational rather than scientific.
A viable entrant must secure:
- An approved ANDA or equivalent national authorization.
- Qualified active pharmaceutical ingredient supply.
- Validated manufacturing capacity.
- Stable packaging and serialization systems.
- Wholesale and pharmacy distribution.
- Competitive contracts with payers or purchasing groups.
- Pharmacovigilance and labeling controls.
Generic launch economics depend heavily on the number of approved suppliers. A market with many active manufacturers produces rapid price erosion. A shortage, plant closure or API disruption can temporarily improve pricing, but such gains are difficult to sustain.
Topical launches can generate better gross margins than tablets when the product has strong packaging, retail placement or a differentiated delivery format. The market remains crowded, and consumer acquisition costs can absorb much of the available margin.
What generic entry risks exist for terbinafine?
The principal risks are commercial and operational:
| Risk |
Impact |
| Price competition |
Limits gross margin and contract leverage |
| API concentration |
Creates supply disruption exposure |
| Regulatory inspection failure |
Can interrupt supply or delay approval |
| Product recalls |
Damages pharmacy and retailer relationships |
| OTC shelf competition |
Raises marketing and distribution costs |
| Safety-related labeling issues |
Can affect prescribing and consumer demand |
| Low market differentiation |
Makes switching easy for wholesalers |
| Small product scale |
Increases unit manufacturing cost |
The absence of meaningful patent barriers increases competition. It does not guarantee attractive returns. A manufacturer with excess capacity may enter the market, but durable profitability requires scale, dependable supply and access to high-volume channels.
How does terbinafine compare with competing antifungals?
| Drug |
Primary channel |
Main advantage |
Main competitive limitation |
| Terbinafine |
Generic prescription and OTC |
Strong efficacy for dermatophytes; oral option |
Systemic safety monitoring and generic price erosion |
| Itraconazole |
Prescription |
Broader antifungal spectrum |
Drug interactions and monitoring complexity |
| Fluconazole |
Prescription |
Familiar dosing and broad availability |
Variable effectiveness for certain nail infections |
| Clotrimazole |
OTC and prescription |
Low price and broad retail availability |
Often requires longer topical treatment |
| Miconazole |
OTC and prescription |
Strong retail presence |
Heavy commoditization |
| Butenafine |
OTC or prescription, market-dependent |
Topical alternative |
Smaller commercial footprint |
Terbinafine remains particularly competitive in dermatophyte infections because oral therapy can provide a defined treatment course for onychomycosis. Topical products face stronger substitution because consumers can choose among several low-cost antifungals.
Does terbinafine face biosimilar competition?
No. Terbinafine is a chemically synthesized small molecule, not a biologic. It faces generic competition under abbreviated drug-approval pathways rather than biosimilar competition under the Public Health Service Act.
This distinction matters commercially. Generic applicants generally rely on pharmaceutical equivalence and bioequivalence. They do not need to reproduce a biologic manufacturing process or conduct the type of analytical comparability program associated with biosimilars.
What is the geographic coverage of terbinafine?
Terbinafine is marketed across North America, Europe, Asia-Pacific and other regions, but product status differs by country.
- The United States has a mature generic prescription market and established OTC topical channels.
- Europe has strong pharmacy and consumer-health distribution, with Lamisil retaining regional brand relevance.
- Emerging markets often have multiple local manufacturers and lower unit prices.
- Regulatory requirements, trademark ownership and approved indications vary by jurisdiction.
- Manufacturing and API supply are frequently concentrated in Asian production networks.
International growth is therefore more likely to come from volume expansion, local registration, private-label supply and regional distribution than from premium pricing.
What licensing deals and commercial transactions affect terbinafine?
The major commercial transition was the movement of Lamisil from an innovative prescription franchise into a consumer-health and generic market. Novartis built the original global franchise and later transferred substantial consumer-health assets through its transaction with GlaxoSmithKline in 2015. GSK’s consumer-health business later became part of Haleon after the 2022 separation from GSK (GSK, 2015; Haleon, 2023).
These transactions affected ownership and distribution of consumer brands, not the underlying generic terbinafine opportunity. Current commercial rights must be assessed separately by country, dosage form and trademark. Generic tablets are generally independent of consumer-brand ownership.
What is the current litigation status?
Terbinafine does not present a major active U.S. patent-litigation profile comparable with recently launched branded therapies. Litigation exposure is more likely to involve:
- Product liability claims relating to oral safety warnings.
- Trademark or trade-dress disputes involving topical products.
- ANDA disputes for particular formulations or branded combinations.
- Manufacturing, supply and commercial-contract disagreements.
- Regulatory enforcement involving labeling or quality systems.
The strategic litigation value of the original molecule patents has largely ended. For investors and generic manufacturers, quality systems, supply continuity and channel contracts are more material than patent enforcement.
How strong is the terbinafine patent estate?
The patent estate is weak as a current exclusivity asset and strong only as historical evidence of a successful product lifecycle.
| Patent-estate factor |
Current assessment |
| Core compound protection |
Expired |
| Oral tablet protection |
Expired or commercially immaterial |
| Topical formulation protection |
Limited and product-specific |
| Method-of-use protection |
No material broad monopoly |
| Generic entry barrier |
Low |
| Biosimilar barrier |
Not applicable |
| Manufacturing know-how |
Potentially relevant but nonexclusive |
| Trademark value |
Still relevant for consumer products |
The remaining defensible assets are brand equity, regulatory files, manufacturing know-how, distribution relationships and differentiated delivery systems. Those assets can support a product but do not recreate the original Lamisil monopoly.
Key Takeaways
- Terbinafine is a mature, off-patent antifungal with low patent risk and high generic competition.
- Lamisil generated more than $1 billion annually during its branded peak, but that revenue was heavily eroded after generic oral entry.
- Oral terbinafine remains commercially important because of its role in onychomycosis treatment.
- Topical terbinafine retains consumer-health value but competes with several inexpensive antifungals.
- No biosimilar pathway applies because terbinafine is a small-molecule drug.
- Current returns depend on manufacturing scale, API supply, pharmacy access, retail distribution and private-label execution.
- Conventional generic tablets offer volume but limited pricing power.
- Differentiated topical delivery systems and combination products offer more potential margin, with higher regulatory and commercial costs.
- The current patent estate does not create a meaningful U.S. barrier to ordinary generic entry.
FAQs
Is terbinafine still profitable for generic manufacturers?
It can be profitable at scale, but conventional tablets are exposed to intense price competition. Profitability depends on manufacturing cost, supply reliability and distribution volume.
Does Lamisil still have patent protection?
The core patents protecting terbinafine and the original Lamisil products have expired in the main commercial markets. Trademark and brand rights can remain active even when patent rights have ended.
Can a company launch a new terbinafine cream without a patent license?
A company may be able to launch a non-infringing generic or OTC product without a license to expired core patents. It must still satisfy applicable FDA or national regulatory requirements and avoid active formulation, trademark or trade-dress rights.
Is oral terbinafine more valuable than topical terbinafine?
Oral terbinafine has greater clinical importance in onychomycosis but lower pricing power because the tablet market is heavily generic. Topical products can support higher retail margins when differentiated by brand, packaging or delivery technology.
What would increase the value of a new terbinafine product?
The strongest opportunities are shorter treatment courses, improved nail penetration, film-forming formulations, lower systemic exposure, combination therapy and well-positioned OTC products. Any premium product would need clinical or consumer benefits beyond standard terbinafine cream or tablets.
References
Food and Drug Administration. (2023). Lamisil (terbinafine hydrochloride) tablets prescribing information. U.S. Department of Health and Human Services.
Food and Drug Administration. (2024a). Approved drug products with therapeutic equivalence evaluations. U.S. Department of Health and Human Services.
GlaxoSmithKline. (2015). GSK and Novartis transaction: Consumer healthcare joint venture and business updates. GlaxoSmithKline plc.
Haleon. (2023). Annual report and financial statements 2022. Haleon plc.
Novartis. (2003). Annual report 2003. Novartis AG.