Last updated: September 6, 2026
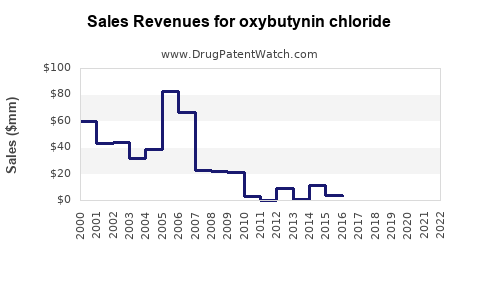
Oxybutynin chloride is a mature, predominantly generic antimuscarinic used for overactive bladder, urge urinary incontinence and neurogenic detrusor overactivity. Its originator economics have largely disappeared after loss of exclusivity for immediate-release and extended-release products. Current revenue is concentrated in low-cost generics, extended-release tablets, transdermal systems and the U.S. over-the-counter Oxytrol patch.
The market is declining in value relative to newer branded therapies, although prescription volume remains material. Pricing pressure, anticholinergic safety concerns, generic substitution and competition from beta-3 agonists have limited growth. Commercial opportunities remain in adherence-oriented formulations, transdermal delivery and low-cost treatment in price-sensitive markets.
What is the current market position of oxybutynin chloride?
Oxybutynin chloride is a legacy treatment for overactive bladder and related urinary disorders. It is available in several dosage forms:
| Product type |
Typical route |
Market status |
Commercial position |
| Immediate-release tablets |
Oral |
Generic |
Lowest-cost and most price-sensitive segment |
| Extended-release tablets |
Oral |
Generic and authorized-generic equivalents |
Retains demand where once-daily dosing is preferred |
| Oral solution or syrup |
Oral |
Generic, availability varies |
Used in pediatric and selected neurogenic-bladder settings |
| Transdermal patch |
Skin |
Generic and branded/OTC versions |
Differentiated by reduced first-pass metabolism and convenience |
| Topical gel |
Skin |
Limited market presence |
Niche alternative to oral dosing |
| Oxytrol for Women |
Skin |
FDA-approved OTC product in the U.S. |
Consumer-health segment with limited scale |
The drug’s core demand comes from chronic treatment. Patients often remain on therapy for extended periods, but discontinuation is common because of dry mouth, constipation, blurred vision, urinary retention and other anticholinergic effects. These tolerability issues reduce persistence and create switching opportunities for newer treatments.
How large is the oxybutynin chloride market?
A single, transparent global market figure for oxybutynin chloride is not publicly reported across all generic manufacturers and dosage forms. The product is supplied by numerous companies, and generic sales are often embedded in broader portfolios rather than disclosed as individual-product revenue.
The economic profile is clear:
- Unit volume remains meaningful because oxybutynin is inexpensive and widely prescribed.
- Revenue per prescription is low in the immediate-release generic segment.
- Extended-release and transdermal products command higher prices than immediate-release tablets.
- Branded revenue is a small share of the historical market.
- Net sales are fragmented across manufacturers, wholesalers, pharmacies and private-label distributors.
The U.S. market has shifted from originator-led revenue to commodity-style generic competition. That transition typically produces a sharp decline in branded sales after generic entry, followed by a lower but more stable volume market. The remaining value is linked to manufacturing efficiency, supply reliability, formulation differentiation and payer access rather than broad patent exclusivity.
What products compete with oxybutynin chloride?
Oxybutynin competes with both other antimuscarinics and beta-3 adrenergic agonists.
Antimuscarinic competitors
The main pharmacologic competitors include:
- Tolterodine, marketed historically as Detrol and Detrol LA
- Solifenacin, marketed as Vesicare
- Darifenacin, marketed as Enablex
- Fesoterodine, marketed as Toviaz
- Trospium, marketed in immediate-release and extended-release forms
These products have also experienced substantial generic erosion. Solifenacin, tolterodine and trospium compete most directly on oral chronic therapy.
Beta-3 adrenergic competitors
Mirabegron, marketed as Myrbetriq, and vibegron, marketed as Gemtesa, provide non-anticholinergic alternatives. Their commercial positioning relies on lower anticholinergic burden, although they carry their own safety, access and pricing considerations.
| Attribute |
Oxybutynin chloride |
Mirabegron |
Vibegron |
| Drug class |
Antimuscarinic |
Beta-3 agonist |
Beta-3 agonist |
| Generic availability |
Broad |
Emerging or limited by jurisdiction and patent status |
Limited by jurisdiction and patent status |
| Price position |
Low |
Higher |
Higher |
| Anticholinergic adverse effects |
Present |
Not typical |
Not typical |
| Main commercial advantage |
Cost and long market experience |
Non-anticholinergic mechanism |
Non-anticholinergic mechanism |
| Main commercial weakness |
Tolerability and cognitive-risk concerns |
Price and blood-pressure considerations |
Price and restricted formulary access |
Oxybutynin remains competitive when a prescriber or payer prioritizes low acquisition cost. Newer drugs are stronger competitors when treatment persistence, tolerability or anticholinergic avoidance drives product selection.
When did oxybutynin chloride lose exclusivity?
Immediate-release oxybutynin has been off patent for decades. Generic competition became established well before the modern Orange Book patent litigation framework became commercially important for the product.
Extended-release oxybutynin, including Ditropan XL, also lost meaningful exclusivity years ago. The product’s commercial protection depended on formulation and delivery patents rather than the active ingredient alone. Once generic extended-release products entered, the originator’s U.S. revenue declined materially.
The transdermal segment had a later commercial cycle. Transdermal oxybutynin products were protected by formulation, device and delivery-system patents, but those protections have not prevented broad generic and alternative-product competition from becoming the dominant market force.
What is the Orange Book status of oxybutynin chloride?
FDA Orange Book treatment varies by specific new drug application, dosage form and listed product. The active ingredient is not protected by a current composition-of-matter patent that supports branded exclusivity.
The relevant regulatory distinctions are:
- Immediate-release tablets are established generic products.
- Extended-release products may have separate ANDA approvals and therapeutic-equivalence designations.
- Transdermal systems may require formulation, adhesive, delivery-rate and device comparability.
- OTC Oxytrol has a separate regulatory and commercial history from prescription oral tablets.
- Orange Book listings for individual brand and generic products must be reviewed by application number and dosage form.
The practical consequence is that oxybutynin chloride is a mature generic market, not a patent-protected branded franchise. Any remaining patent value is product-specific and generally relates to delivery technology, formulation or device implementation.
What formulations are protected or commercially differentiated?
The active molecule provides little current exclusivity. Commercial differentiation comes from the dosage form.
Extended-release oral tablets
Extended-release oxybutynin reduces dosing frequency compared with immediate-release tablets. The formulation can improve convenience but does not eliminate systemic anticholinergic exposure. Generic manufacturers compete on bioequivalence, manufacturing yield, supply continuity and pharmacy substitution.
Transdermal patches
The transdermal route avoids first-pass hepatic metabolism and can reduce exposure to the active metabolite associated with some oral adverse effects. Patch products compete on:
- Drug-release consistency
- Adhesion
- Skin tolerability
- Application frequency
- Patch size
- Patient persistence
- Manufacturing cost
The patch remains the most commercially differentiated oxybutynin format. Its market is smaller than oral therapy but can support higher prices and better gross margins than immediate-release tablets.
Topical gel
Topical oxybutynin gel offers another non-oral delivery option. Its commercial position is constrained by patient acceptance, prescription access and competition from patches and oral generics.
What is the FDA regulatory status of oxybutynin chloride?
Oxybutynin chloride is FDA-approved for:
- Symptoms of urge urinary incontinence
- Urgency and frequency associated with overactive bladder
- Neurogenic detrusor overactivity in selected patients
FDA-approved forms include oral immediate-release tablets, extended-release tablets, oral solution and transdermal systems. Oxytrol for Women became the first nonprescription treatment for overactive bladder symptoms approved by FDA through an OTC switch in 2013. The OTC product is intended for women aged 18 years and older who meet the product’s labeling criteria.[1]
FDA approval does not create current commercial exclusivity for the active ingredient. The key regulatory barriers for new entrants are ANDA development, bioequivalence, manufacturing validation, transdermal performance and supply-chain execution.
How strong is the patent estate for oxybutynin chloride?
The broad patent estate is weak from a current revenue-protection perspective.
| Patent category |
Current relevance |
| Active ingredient composition |
Minimal; long expired |
| Immediate-release formulation |
Minimal; generic competition established |
| Extended-release formulation |
Historical importance; current blocking value limited |
| Transdermal delivery |
Most relevant surviving technology category, but mature |
| Device and adhesive systems |
May support narrow claims, but rarely supports broad market control |
| Method-of-use claims |
Limited commercial value where the product is already widely used |
| Manufacturing patents |
Potentially relevant to cost and supply, not usually market exclusivity |
Patent strength should be assessed at the product level rather than for oxybutynin chloride as a molecule. A narrow transdermal or manufacturing patent can affect a specific supplier without restoring originator-level pricing power.
Which companies manufacture or commercialize oxybutynin chloride?
Supply is distributed across generic manufacturers and specialty pharmaceutical companies. Historical originator and branded rights have involved companies including Alza, Janssen and later commercial partners, while generic supply has been associated with large U.S. and international manufacturers.
The competitive field commonly includes companies such as:
- Teva Pharmaceutical Industries
- Mylan, now part of Viatris
- Actavis, now associated with Teva
- Dr. Reddy’s Laboratories
- Endo and Par Pharmaceutical
- Rising Pharmaceuticals
- Sandoz
- Amneal Pharmaceuticals
- Cipla and other international suppliers
Manufacturer participation varies by dosage form, market and time. Many companies supply tablets without participating in transdermal systems, where technical manufacturing requirements are higher.
Which companies are challenging oxybutynin patents?
Oxybutynin is not currently characterized by a major active patent challenge comparable to high-value branded drugs approaching first generic entry. Most meaningful challenges occurred during the historical loss-of-exclusivity period for extended-release and transdermal products.
The commercial issue now is less Paragraph IV litigation than continued ANDA competition and generic price compression. Paragraph IV certifications may still arise for individual listed patents or specific products, but they do not define the current market.
What patent litigation affects oxybutynin chloride?
Historical litigation involving extended-release or transdermal oxybutynin focused on formulation, delivery and product-specific patents. The commercial effect was temporary protection or delayed entry for certain products rather than durable protection for the entire active-ingredient market.
No broad, current litigation framework is generally associated with oxybutynin chloride as a whole. Litigation exposure is more likely to arise from:
- A new transdermal delivery system
- A modified-release matrix
- A patch adhesive or reservoir
- A device component
- A narrow manufacturing process
- Trade-secret or supply disputes
Generic manufacturers must still manage product-specific patent certifications and litigation risk when filing ANDAs, but the market has already moved beyond the originator’s main exclusivity period.
Are there biosimilar risks for oxybutynin chloride?
No. Oxybutynin chloride is a small-molecule drug, not a biologic. Biosimilar regulation is irrelevant. Competition occurs through the generic-drug pathway, principally abbreviated new drug applications and therapeutic-equivalence determinations.
This distinction matters commercially because generic competition can be broader and faster than biosimilar competition once patents and regulatory exclusivities expire. The main constraints are bioequivalence, formulation complexity and manufacturing capacity.
What is the financial trajectory for oxybutynin chloride?
The financial trajectory has four phases.
1. Originator growth
The initial commercial period was driven by oral prescription adoption for overactive bladder and urinary incontinence. Revenue was supported by branded pricing and physician familiarity.
2. Extended-release expansion
Extended-release and transdermal forms increased convenience and allowed manufacturers to segment the market. These products temporarily supported higher prices than immediate-release tablets.
3. Generic erosion
Generic entry reduced branded market share, prescription reimbursement and average selling price. Immediate-release tablets became highly commoditized. Extended-release products also experienced substantial price erosion after multiple generic suppliers entered.
4. Mature generic stabilization
The current market is characterized by high volume, low pricing and fragmented supply. Revenue depends on:
- Prescription volume
- Generic market share
- Product availability
- Contract pricing
- Formulation mix
- Pharmacy substitution
- Manufacturing utilization
- Shortages or supplier exits
The highest relative margin potential is in transdermal and other differentiated delivery systems. The lowest is in immediate-release tablets, where competition is largely price-based.
What revenue exposure do manufacturers have?
Oxybutynin is unlikely to represent a material revenue driver for diversified pharmaceutical companies. It is more relevant to generic manufacturers with large portfolios, contract manufacturers and companies operating in specialty dosage forms.
Revenue exposure is generally:
| Company type |
Exposure |
| Diversified branded pharmaceutical company |
Low |
| Large generic manufacturer |
Low on a company-wide basis, but recurring |
| Specialty transdermal manufacturer |
Potentially meaningful |
| Contract manufacturer |
Dependent on supply agreements |
| Retail pharmacy or distributor |
Low margin, high volume |
| Consumer-health company |
Limited to OTC patch activity |
A product-level sales estimate should not be inferred from company-wide filings because most manufacturers do not report oxybutynin revenue separately. The absence of product disclosure reflects the drug’s mature generic status, not the absence of demand.
What generic launch scenarios exist?
Three launch scenarios are commercially relevant.
Immediate-release tablet launch
This is the lowest-risk scenario from a technical standpoint but offers limited upside. Multiple suppliers and automatic substitution place rapid pressure on price.
Extended-release tablet launch
This requires more complex formulation and bioequivalence work. It can provide better pricing than immediate-release tablets, but the commercial opportunity narrows as more approved suppliers enter.
Transdermal launch
This has the greatest technical and commercial differentiation. Development risk is higher because adhesion, release rate, skin irritation and device performance must be controlled. A successful entrant can obtain better pricing, but it faces a smaller patient segment and established alternatives.
What manufacturing and intellectual-property barriers remain?
Manufacturing barriers are more important than molecule-level patent barriers.
For oral products, key requirements include controlled release, content uniformity, dissolution performance and stable production at low cost. For patches and gels, manufacturers must control drug loading, permeation, adhesive performance, packaging, shelf life and skin compatibility.
Supply risks include:
- Active pharmaceutical ingredient concentration among a limited number of suppliers
- Low-margin products vulnerable to manufacturer withdrawal
- Batch failures affecting multiple wholesalers
- Packaging and transdermal component shortages
- Contract-manufacturing dependence
- Regulatory remediation at generic facilities
These factors can create temporary price increases or supply advantages without producing durable exclusivity.
How does oxybutynin chloride compare with newer overactive-bladder drugs?
Oxybutynin has the strongest cost position and the weakest tolerability profile among major treatment options. Mirabegron and vibegron have higher prices but offer non-anticholinergic mechanisms. Other antimuscarinics may provide improved selectivity or better tolerability for some patients, but most are also exposed to generic competition.
The market is therefore divided:
- Oxybutynin dominates low-cost access.
- Beta-3 agonists compete for patients seeking to avoid anticholinergic effects.
- Transdermal oxybutynin competes for patients who need an alternative to oral dosing.
- Other generic antimuscarinics compete through formulary placement and tolerability differences.
Prescribing may continue to shift toward non-anticholinergic options for older adults because of concern about cumulative anticholinergic burden and possible cognitive effects. The American Geriatrics Society lists oxybutynin among medications requiring caution in older adults because of strong anticholinergic properties.[2]
What licensing deals affect oxybutynin chloride?
Oxybutynin has had historical commercialization and rights arrangements around branded formulations and consumer-health products. These arrangements are less important today than generic supply agreements and manufacturing contracts.
The commercial value of a new licensing deal would likely depend on:
- Access to a differentiated transdermal platform
- A lower-irritation patch
- A long-acting formulation
- A pediatric delivery system
- Combination therapy
- Geographic rights in markets with limited generic penetration
A license covering standard immediate-release oxybutynin would have limited strategic value unless it included manufacturing scale, regulatory approvals or a protected distribution channel.
What geographic markets remain attractive?
The United States is mature and highly genericized. Opportunity is more likely in markets where:
- Generic penetration is incomplete
- Transdermal products are underdeveloped
- Brand reimbursement remains available
- Overactive bladder diagnosis is increasing
- Distribution is fragmented
- Regulatory approval can be obtained without extensive local trials
Japan, parts of Europe, Latin America and selected Asian markets have established antimuscarinic use, but pricing, reimbursement and local competitors differ significantly. Emerging markets may offer volume growth, although low prices and tender procurement limit revenue per unit.
Key Takeaways
- Oxybutynin chloride is a mature generic drug with no meaningful active-ingredient exclusivity.
- Immediate-release tablets are highly commoditized and generate low revenue per prescription.
- Extended-release and transdermal products retain the greatest commercial differentiation.
- The U.S. OTC Oxytrol patch provides a separate consumer-health channel but does not restore broad brand economics.
- Generic competition, anticholinergic safety concerns and beta-3 agonists constrain long-term growth.
- Biosimilar risk does not apply because oxybutynin is a small molecule.
- Current commercial value lies in manufacturing efficiency, reliable supply and differentiated delivery systems.
- Patent risk is product-specific and centered on formulation, device, delivery and manufacturing claims.
- No single public source provides consolidated global oxybutynin revenue because sales are fragmented across generic manufacturers.
FAQs
Is oxybutynin chloride still profitable for pharmaceutical companies?
It can be profitable at scale, but profitability is generally driven by manufacturing efficiency and portfolio economics rather than premium pricing. Immediate-release tablets have limited margin potential, while transdermal and extended-release products may support better economics.
Is oxybutynin chloride being replaced by mirabegron?
Not completely. Mirabegron is gaining use where clinicians seek a non-anticholinergic option, but oxybutynin remains important because of its low price, broad availability and long clinical history.
Does oxybutynin chloride have a current composition-of-matter patent?
No meaningful active composition-of-matter patent is expected to protect the molecule. Current patent issues, where relevant, concern specific formulations, delivery systems, devices or manufacturing methods.
Can a company obtain FDA approval for a new oxybutynin patch?
Yes. A company may pursue an abbreviated or full regulatory pathway depending on the product and reference product. The main development hurdles are adhesion, drug delivery, bioequivalence or comparative performance, skin tolerability and manufacturing controls.
Why do oxybutynin prices vary so widely by dosage form?
Immediate-release tablets are supplied by many generic manufacturers and face strong pharmacy substitution. Transdermal patches and other modified-delivery products require more complex manufacturing and may have fewer suppliers, which supports higher prices.
References
- U.S. Food and Drug Administration. (2013). FDA approves first over-the-counter drug for overactive bladder. https://www.fda.gov
- American Geriatrics Society Beers Criteria Update Expert Panel. (2023). American Geriatrics Society 2023 updated AGS Beers Criteria for potentially inappropriate medication use in older adults. Journal of the American Geriatrics Society, 71(7), 2052-2081.
- U.S. Food and Drug Administration. (2024). Orange Book: Approved drug products with therapeutic equivalence evaluations. https://www.accessdata.fda.gov/scripts/cder/ob/
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
- U.S. Food and Drug Administration. (2023). Ditropan XL prescribing information. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2023). Oxytrol for Women prescribing information. https://www.accessdata.fda.gov