Last updated: September 1, 2026
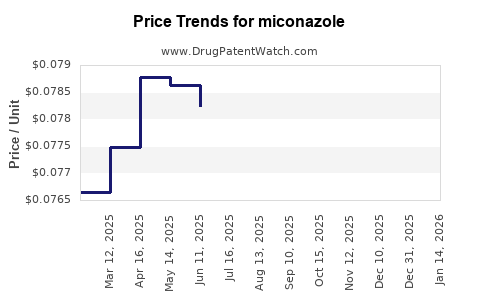
Miconazole is a mature, largely generic antifungal with limited patent protection, broad over-the-counter availability, and modest long-term growth prospects. Revenue is concentrated in topical and vaginal products, while oral buccal use remains a niche prescription segment. The commercial market is fragmented across branded products, private-label retailers, pharmacy generics, and regional brands. Pricing pressure, retailer substitution, and low manufacturing barriers constrain margins, but recurring infection demand and seasonal use support durable cash generation.
Miconazole Market Dynamics, Financial Trajectory, Patents, and Competitive Outlook
What is miconazole and how is it used?
Miconazole is an imidazole antifungal active ingredient used against Candida species and dermatophytes. It inhibits fungal ergosterol synthesis by interfering with lanosterol 14-alpha-demethylase and related membrane processes.
The principal dosage forms are:
| Dosage form |
Common indication |
Regulatory position |
Commercial importance |
| Vaginal cream, suppository, ovule |
Vulvovaginal candidiasis |
Primarily OTC in the U.S. |
High |
| Topical cream, spray, powder, lotion |
Athlete's foot, jock itch, ringworm, cutaneous candidiasis |
OTC in the U.S. |
High |
| Oral buccal tablet |
Oropharyngeal candidiasis |
Prescription product in the U.S. |
Low |
| Dermatologic combinations |
Fungal infections with corticosteroids or other agents |
Country-specific |
Moderate outside the U.S. |
| Veterinary and hospital formulations |
Local or systemic fungal infections |
Country-specific |
Limited |
The ingredient is marketed under names including Monistat, Daktarin, Micatin, and numerous generic and private-label products. Brand ownership differs by country and has changed through acquisitions and licensing arrangements.
How large is the miconazole market?
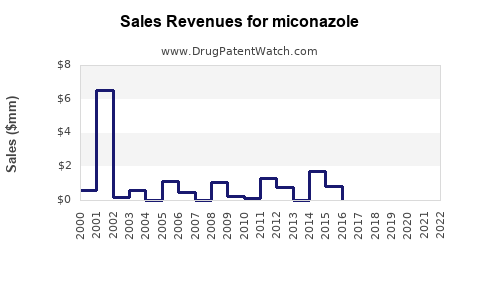
No public company reports a globally consolidated miconazole revenue figure. Market-research estimates also vary because some reports include only vaginal products, while others combine topical antifungals, oral formulations, combination products, and veterinary use.
The commercial market has four characteristics:
- Topical and vaginal products account for most human-use volume.
- U.S. sales are largely OTC and therefore excluded from traditional prescription claims datasets.
- Unit volume is relatively stable, while revenue depends heavily on brand mix, channel, and pack size.
- Miconazole competes in a broad antifungal category rather than operating as a distinct high-growth pharmaceutical franchise.
The relevant economic market is therefore better understood as a mature OTC antifungal segment. Miconazole participates in the same consumer categories as clotrimazole, terbinafine, butenafine, tolnaftate, and nystatin.
What drives miconazole demand?
Demand is supported by recurring, self-diagnosed fungal conditions and continued pharmacy availability. Key demand drivers include:
- Vulvovaginal candidiasis episodes
- Tinea pedis and other superficial dermatophyte infections
- Consumer preference for nonprescription treatment
- Seasonal increases in dermatologic fungal infections
- Pharmacy and supermarket private-label programs
- Use in markets where miconazole is an established first-line topical antifungal
Demand is constrained by substitution to newer or shorter-course products, diagnostic uncertainty in vaginal infections, and competition from oral fluconazole where prescription treatment is available.
What is the financial trajectory for miconazole?
Miconazole has a mature financial profile rather than a conventional pharmaceutical growth profile.
Revenue trajectory
The most likely long-term pattern is:
| Period |
Revenue pattern |
Main commercial explanation |
| Early branded period |
Expansion |
Product launches, physician adoption, and geographic rollout |
| Patent and exclusivity maturity |
Peak branded value |
Established brand recognition and broad distribution |
| Generic and OTC transition |
Revenue compression |
Entry of low-cost competitors and private labels |
| Current mature period |
Stable to low-single-digit nominal growth |
Population, inflation, channel expansion, and price increases |
| Long-term outlook |
Flat to modest growth |
Volume resilience offset by price erosion |
Miconazole revenue is likely to be more resilient in consumer health than in prescription markets because the leading products have high retail recognition and repeat demand. The branded premium remains strongest for vaginal products, where consumers may value established names, applicator design, treatment duration, and perceived reliability.
Topical dermatology is more price-sensitive. Retailers can substitute among miconazole, clotrimazole, terbinafine, and store-brand equivalents with limited switching friction.
Margin profile
Manufacturing economics are generally favorable because miconazole is a small-molecule active pharmaceutical ingredient with established synthetic routes and numerous suppliers. Gross margins depend on:
- API procurement cost
- Tube, ovule, suppository, and applicator packaging
- Retailer trade spending
- Promotional intensity
- Contract manufacturing terms
- Regulatory testing and batch-release requirements
- Brand versus private-label mix
Branded OTC products can preserve higher gross margins than generic prescription products, but retailer bargaining power limits the ability to sustain premium pricing. Private-label suppliers often compete primarily on cost, supply reliability, and regulatory execution.
Public-company financial statements generally aggregate miconazole within broader consumer-health or self-care categories. Kenvue, Bayer, Perrigo, and other companies do not consistently disclose product-level miconazole revenue in their annual reports. Product-level revenue estimates should therefore be treated as market estimates rather than audited financial data.[1-3]
Which companies market miconazole products?
The competitive landscape is fragmented by geography and dosage form.
| Company or group |
Relevant commercial role |
| Kenvue and legacy Johnson & Johnson consumer-health businesses |
Monistat-related vaginal antifungal products in certain markets |
| Bayer and regional licensees |
Daktarin and related miconazole products in multiple countries |
| Perrigo |
OTC and store-brand consumer-health manufacturing and distribution |
| Haleon and local consumer-health companies |
Antifungal products and regional brands, depending on market |
| Generic manufacturers |
Topical, vaginal, and prescription formulations |
| Retailers |
Private-label creams, suppositories, and combination products |
| Contract manufacturers |
Supply products for branded and private-label owners |
Brand ownership is not uniform worldwide. A brand may be owned by one company, manufactured by another, and distributed by a third. Licensing and divestiture transactions are more commercially important than new patent licensing because the underlying active ingredient is long off patent.
What patents protect miconazole?
The original miconazole composition and basic pharmaceutical use patents are expired in major markets. Miconazole was developed and commercialized decades ago, leaving no meaningful remaining exclusivity around the active ingredient itself.
Current intellectual-property value is more likely to arise from:
- Specific dosage forms
- Applicator systems
- Drug-delivery vehicles
- Combination products
- Manufacturing processes
- Packaging and device claims
- Brand trademarks
- Regulatory data and market authorization rights
These rights generally do not prevent broad generic competition. A formulation patent may protect one product configuration without blocking creams, suppositories, powders, or alternative concentrations.
How many patents cover miconazole?
There is no commercially relevant global count of active blocking patents for miconazole. Patent databases contain historical and jurisdiction-specific documents, but most core patents have expired. A meaningful freedom-to-operate review must screen each product’s formulation, concentration, excipients, device, manufacturing process, and country of sale.
For standard miconazole nitrate cream, powder, and vaginal products, the primary barriers are regulatory compliance, quality manufacturing, and distribution rather than the active ingredient patent estate.
What is the Orange Book status of miconazole?
The U.S. Orange Book lists approved prescription drug products and their patent and exclusivity information. Most OTC miconazole products are marketed under the FDA nonprescription monograph system and do not rely on an Orange Book-listed product patent in the same way as an NDA-based prescription medicine.[4]
The FDA’s OTC antifungal framework covers active ingredients and conditions of use for products such as miconazole nitrate. Products marketed under the monograph pathway generally face no branded prescription-style market exclusivity. Manufacturers must comply with the applicable monograph, labeling requirements, quality standards, and other FDA rules.[5]
The oral buccal product Oravig, containing miconazole, was approved as an NDA product for oropharyngeal candidiasis. Its commercial significance is limited relative to the OTC market. The approval history, current marketing status, and any listed patents should be confirmed through Drugs@FDA and the current Orange Book before relying on a specific exclusivity date.[6]
When does miconazole lose exclusivity?
Miconazole’s core patent exclusivity expired long ago. There is no anticipated loss-of-exclusivity event comparable to a major branded prescription product because the principal commercial products are already generic or OTC.
The practical exclusivity timeline is:
| Milestone |
Status |
| Core active-ingredient protection |
Expired |
| Basic topical and vaginal formulations |
Expired or nonblocking in major markets |
| OTC monograph pathway |
Available, subject to FDA requirements |
| Brand trademarks |
Potentially active and renewable |
| Formulation or device patents |
Product- and jurisdiction-specific |
| Prescription buccal product exclusivity |
Must be checked against current FDA records |
| Biosimilar exclusivity |
Not applicable |
Trademarks, packaging, consumer advertising, and retail placement provide more commercial differentiation than patent protection.
Are there Paragraph IV challenges for miconazole?
Paragraph IV litigation is unlikely to be a major current issue for standard OTC miconazole products. Paragraph IV certifications apply to abbreviated new drug applications referencing listed prescription products with relevant Orange Book patents. Many miconazole products are not marketed through that pathway.
Potential Paragraph IV activity would be limited to a specific prescription formulation, such as an oral buccal product, if an applicant filed an ANDA against an NDA with unexpired listed patents. That analysis requires a current Orange Book listing and FDA ANDA litigation record.
For ordinary miconazole cream, powder, and vaginal products, competition generally arises through OTC monograph compliance, private-label sourcing, and abbreviated regulatory routes rather than high-profile patent litigation.
What formulation patents protect miconazole?
Formulation claims can cover:
- Miconazole nitrate concentration
- Cream or gel composition
- Mucoadhesive buccal delivery
- Vaginal suppository or ovule structure
- Controlled release
- Particle size or suspension characteristics
- Preservative systems
- Applicator design
- Combination therapy
The strongest formulation position historically involved delivery systems designed to prolong mucosal residence or improve local exposure. Those claims are narrower than a composition-of-matter patent and can often be avoided by changing excipients, release characteristics, dosage form, or device configuration.
Formulation patents may still matter for a branded product’s litigation posture, but they generally do not create durable category-wide exclusivity.
What patent litigation affects miconazole?
Miconazole has no widely recognized current patent litigation comparable to disputes involving major oncology, immunology, or diabetes drugs. Litigation risk is more likely to involve:
- Trademark infringement
- False advertising
- OTC labeling
- Product liability
- Manufacturing defects
- Retail exclusivity or distribution contracts
- Combination-product patents
- Device or applicator claims
The absence of major patent litigation reflects the age of the molecule and the availability of alternative dosage forms.
Is biosimilar risk relevant to miconazole?
No. Biosimilar competition is not relevant because miconazole is a chemically synthesized small molecule, not a biologic. Competitive risk comes from generic, OTC, private-label, and therapeutic substitution.
How does miconazole compare with competing antifungals?
| Product |
Main advantage |
Main weakness |
| Miconazole |
Long consumer history, broad dosage-form availability, strong vaginal and topical recognition |
Mature pricing and substitution pressure |
| Clotrimazole |
Broad global availability and low cost |
Similar generic commoditization |
| Terbinafine |
Strong positioning for dermatophyte infections and short treatment courses |
Less interchangeable with candidiasis-focused products |
| Butenafine |
Topical efficacy and differentiated branding in some markets |
Smaller global commercial footprint |
| Tolnaftate |
Established OTC presence |
Narrower perceived use and older product positioning |
| Nystatin |
Familiarity in Candida treatment |
Different spectrum and formulation profile |
| Fluconazole |
Convenient systemic treatment in prescription markets |
Prescription controls, interactions, and systemic exposure |
Miconazole is strongest where local treatment, OTC access, and vaginal or cutaneous use drive purchasing decisions. It is weaker where consumers prioritize the shortest course or where physicians favor systemic therapy.
What generic entry risks exist for miconazole?
Generic-entry risk is already realized rather than prospective. Standard products face continuous substitution from:
- Store brands
- Pharmacy generics
- Regional OTC brands
- Contract-manufactured products
- Imported products where permitted
- Alternative antifungal ingredients
The remaining commercial risks are price deflation, retailer delisting, manufacturing shortages, and loss of shelf space. A branded product can defend share through consumer awareness, packaging, treatment-format innovation, and distribution, but those defenses do not prevent low-cost competition.
What regulatory status does miconazole have?
Miconazole is an established FDA-recognized antifungal active ingredient for specified OTC uses, including topical and vaginal applications, subject to applicable monograph conditions and labeling requirements.[5] Prescription formulations require separate approval and may be subject to NDA-specific requirements.
Regulatory issues that can affect the market include:
- Claims outside permitted OTC indications
- Labeling for pregnancy and age groups
- Applicator and dose uniformity requirements
- Microbiological quality
- Preservative effectiveness
- Stability of creams, gels, and suppositories
- Combination-product review
- Country-specific classification as OTC or prescription
Regulatory compliance is a meaningful manufacturing barrier, but it does not provide durable market exclusivity.
What manufacturing and intellectual-property barriers exist?
Manufacturing barriers are moderate. The API is established, but finished products require validated processes and dosage-form expertise.
Key barriers include:
- Reliable pharmaceutical-grade miconazole nitrate supply
- Control of particle size and uniformity
- Emulsion and suspension stability
- Suppository melting and release characteristics
- Vaginal-product applicator quality
- Microbial limits and preservative control
- Packaging compatibility
- Stability testing across climatic zones
- OTC labeling and regulatory submissions
These requirements favor experienced contract manufacturers, especially for vaginal products and complex semi-solid formulations. They do not create the high technical barrier associated with sterile biologics or complex injectables.
What licensing deals affect miconazole?
Licensing is primarily relevant to brand ownership, regional distribution, and contract manufacturing. The underlying molecule does not present a major new-innovation licensing opportunity.
Commercial agreements may involve:
- Regional rights to Monistat or Daktarin brands
- Private-label supply contracts
- OTC product divestitures
- Distribution rights
- Co-manufacturing arrangements
- Trademark licenses
Deal economics are generally driven by brand equity, retail access, manufacturing capacity, and geographic reach rather than patent exclusivity.
What is the outlook for miconazole revenue?
Miconazole should be modeled as a defensive, mature consumer-health product rather than a growth pharmaceutical asset.
The base case is:
- Stable or slowly declining unit volume in developed markets
- Nominal revenue support from inflation and pack-price increases
- Continued shift from branded products to private label
- Stronger growth in emerging markets where OTC access expands
- Ongoing substitution by terbinafine, clotrimazole, and systemic therapies
- Limited potential for material patent-driven price protection
The most attractive opportunities are likely to involve low-cost supply, regional brand acquisition, private-label manufacturing, and improved delivery formats. A conventional patent-led launch would have limited value unless it materially improves treatment duration, adherence, tolerability, or diagnostic targeting.
Key Takeaways
- Miconazole is a mature small-molecule antifungal with expired core patent protection.
- Most commercial value comes from OTC vaginal and topical products.
- The U.S. market is shaped by OTC monograph rules rather than traditional prescription exclusivity.
- Paragraph IV litigation and biosimilar risk are limited or inapplicable for the main products.
- Brand recognition and retail distribution matter more than patent strength.
- Generic and private-label competition has already compressed pricing.
- Public companies generally do not disclose miconazole revenue separately.
- Long-term financial performance is likely to be stable to modestly declining in developed markets, with selective growth in emerging markets.
- Manufacturing capability, regulatory compliance, and channel access are the principal barriers to entry.
- Miconazole is more suitable for a consumer-health, supply, or brand-acquisition strategy than for a patent-driven pharmaceutical investment.
FAQs
Is miconazole still commercially attractive for pharmaceutical companies?
Yes, but mainly through private-label supply, established OTC brands, regional distribution, and manufacturing scale. The molecule itself offers little patent-led upside.
Which miconazole dosage form has the strongest commercial position?
Vaginal products have the strongest branded consumer position, while topical creams and powders have broader volume but greater price competition.
Can a company obtain new exclusivity for a miconazole product?
Potentially, through a novel formulation, device, combination, or approved prescription indication. Such protection would be narrow and would not restore exclusivity for the active ingredient.
Does miconazole have supply-chain risk?
Yes. Risk can arise from API concentration, manufacturing-site disruptions, packaging shortages, and quality failures. Finished-dose supply is more complex for semi-solid and vaginal products than for simple tablets.
Is miconazole a high-growth antifungal market?
No. It is a mature market with recurring demand, low technical novelty, and limited pricing power. Growth is more likely to come from geographic expansion, channel development, and product-format changes than from increased penetration in established markets.
References
- Kenvue Inc. (2024). 2023 annual report. https://investors.kenvue.com
- Bayer AG. (2024). Annual report 2023. https://www.bayer.com/en/investors/annual-reports
- Perrigo Company plc. (2024). Annual report 2023. https://investor.perrigo.com
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
- U.S. Food and Drug Administration. (2024). Over-the-counter monograph M005: Topical antifungal products. https://www.accessdata.fda.gov
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/