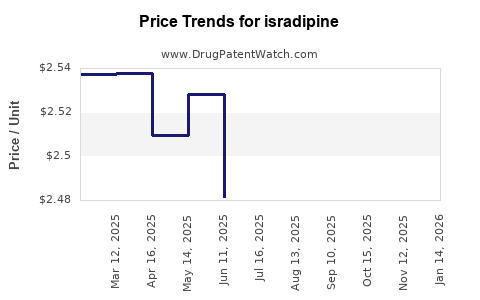
Last updated: September 2, 2026
Isradipine is a mature dihydropyridine calcium-channel blocker with limited commercial importance. The U.S. product has moved from branded sales under Dynacirc to a small generic market dominated by low-cost suppliers. Isradipine remains FDA-approved for hypertension, but it has lost meaningful market exclusivity, has no biosimilar pathway, and faces limited investment in new formulations or clinical development. Public sources do not disclose reliable standalone revenue for isradipine, so its financial trajectory is best assessed through regulatory status, generic availability, prescription volume, pricing, and the broader decline of legacy antihypertensive brands.
What is isradipine and how is it used?
Isradipine is an orally administered dihydropyridine calcium-channel blocker. It reduces peripheral vascular resistance by inhibiting calcium influx into vascular smooth muscle. The FDA-approved indication is treatment of hypertension, either alone or with other antihypertensive agents.[1]
Isradipine dosage forms and strengths
The principal immediate-release dosage forms are capsules containing:
| Product |
Strengths |
Regulatory status |
| Isradipine capsules |
2.5 mg and 5 mg |
FDA-approved generic product |
| Dynacirc capsules |
2.5 mg and 5 mg |
Historical branded product |
| Dynacirc CR |
Extended-release formulation |
Historical product; commercial availability has been limited |
The usual adult starting dose is 2.5 mg twice daily. The label permits titration based on blood-pressure response and tolerability.[1]
Isradipine is less widely prescribed than amlodipine, felodipine, nifedipine, or nicardipine. It is generally positioned as an alternative calcium-channel blocker rather than a first-choice growth product.
What is the FDA regulatory status of isradipine?
Isradipine was approved in the United States in the early 1990s under the Dynacirc brand. Generic immediate-release capsules subsequently entered the market after expiration of the relevant pioneering and regulatory protections.
The product is regulated as a conventional small-molecule prescription drug. It is not a biologic, and biosimilar approval is not relevant. Generic applicants use the abbreviated new drug application, or ANDA, pathway and must demonstrate pharmaceutical equivalence and bioequivalence rather than repeat the original efficacy trials.[2]
FDA exclusivity timeline
| Regulatory milestone |
Commercial implication |
| Original FDA approval |
Established branded market for Dynacirc |
| Expiration of original patent and regulatory protections |
Opened the market to ANDA-based generic competition |
| Generic approvals |
Shifted pricing power from the originator to manufacturers and wholesalers |
| Current mature-market status |
Low differentiation and limited incentive for new clinical investment |
The original approval-related exclusivity period has expired. Isradipine is no longer protected by new chemical entity exclusivity.
What patents protect isradipine?
The commercially relevant composition-of-matter and early formulation protections for isradipine are expired or no longer material to market access. Current competition is therefore based on manufacturing economics, supply reliability, product listing, and distribution rather than on a live exclusivity moat.
What is the Orange Book status of isradipine?
The FDA Orange Book is the primary source for patents and exclusivity associated with approved drug products. Isradipine has no commercially meaningful current Orange Book patent barrier comparable to the patent estates surrounding newer branded drugs.[3]
The relevant intellectual-property conclusions are:
| IP category |
Current commercial position |
| Compound patent |
Expired |
| Original formulation patents |
Expired or commercially nonblocking |
| New chemical entity exclusivity |
Expired |
| Pediatric exclusivity |
No current commercial significance identified |
| Method-of-use patents |
No widely recognized active U.S. barrier to generic hypertension use |
| Orange Book-listed blocking patents |
No material current barrier identified |
| Trade secrets |
May protect manufacturing know-how but do not prevent ANDA competition |
Patent expiration dates for legacy isradipine patents are less important than the current absence of an enforceable, product-blocking estate. A generic manufacturer can generally enter through the ANDA pathway without relying on a branded patent license.
When did isradipine lose exclusivity?
Isradipine lost meaningful U.S. market exclusivity years ago, before the current generic-dominated period. The exact commercial transition varied by product and dosage form, particularly between immediate-release capsules and extended-release Dynacirc CR.
The economic effect was typical for a mature oral antihypertensive:
- The branded product lost pricing power.
- Generic suppliers entered with substantially lower prices.
- Prescribing shifted toward higher-volume calcium-channel blockers.
- Pharmacy substitution reduced the originator's recurring revenue.
- Manufacturers retained the product only where production and distribution costs were low enough to support acceptable margins.
How many patents cover isradipine today?
No current patent estate appears to provide meaningful U.S. market exclusivity for standard isradipine capsules. The number of patents that matter commercially is therefore effectively zero for ordinary generic entry.
This does not mean that every historical patent has expired in every country or that no process patent exists. Patent rights can differ by jurisdiction, dosage form, manufacturing process, and filing date. Those rights do not appear to create a significant U.S. barrier for the approved immediate-release product.
Are formulation patents protecting isradipine?
The historical extended-release product created a potential formulation distinction from immediate-release capsules. That distinction has limited current value because:
- Immediate-release isradipine is already generic.
- The market is small relative to major calcium-channel blockers.
- Prescribers have many alternative agents.
- Extended-release development would require additional formulation, bioequivalence, manufacturing, and commercialization investment.
- The price ceiling for a legacy antihypertensive is low.
A new formulation could obtain patent protection if it met the requirements for novelty, nonobviousness, written description, and enablement. That possibility does not establish a current enforceable patent position.
Which companies are challenging isradipine patents?
No major active U.S. Paragraph IV litigation campaign is associated with isradipine in the public record. Paragraph IV certifications are most commercially important when a branded product has an active Orange Book patent and substantial sales exposure. Isradipine does not fit that profile.
What is the litigation status of isradipine?
The commercial market does not appear to be shaped by current high-value patent litigation involving isradipine. There is no widely reported settlement structure that controls generic launch timing for the mature immediate-release product.
Any isolated ANDA disputes, manufacturing disputes, or historical patent proceedings would have limited impact on the present market unless they affected the only remaining supplier. The main current risks are operational:
- product discontinuation;
- active-pharmaceutical-ingredient shortages;
- low-volume manufacturing;
- wholesaler delisting;
- quality-control actions; and
- supplier consolidation.
How large is the isradipine market?
Isradipine is a niche product within the global antihypertensive market. It competes against much larger drug classes and brands, including amlodipine, nifedipine, felodipine, diltiazem, angiotensin-converting enzyme inhibitors, angiotensin receptor blockers, and thiazide diuretics.
Public company reports generally do not break out isradipine revenue. Its sales are usually embedded within broader generic portfolios. The absence of standalone disclosure indicates that isradipine is not a material revenue contributor for major diversified generic manufacturers.
Market-position comparison
| Drug |
Market maturity |
Prescription scale |
Generic competition |
Commercial outlook |
| Isradipine |
Mature |
Low |
High |
Stable to declining |
| Amlodipine |
Mature |
Very high |
High |
Large-volume commodity |
| Nifedipine ER |
Mature |
High |
High |
Established chronic-use market |
| Felodipine |
Mature |
Moderate to low |
High |
Niche, similar pressure |
| Nicardipine |
Mature |
Lower outpatient volume; hospital relevance |
High |
More differentiated by acute-care use |
Isradipine lacks the volume of amlodipine and the institutional relevance of injectable nicardipine. It is more exposed to discontinuation risk because a small number of suppliers can serve the remaining demand.
What is isradipine's financial trajectory?
Isradipine's financial trajectory follows a mature-generic pattern rather than an innovative-drug pattern.
Branded phase
During the Dynacirc period, revenue depended on brand pricing, physician familiarity, and the absence of therapeutically interchangeable low-cost competitors. The product had commercial value as part of a cardiovascular portfolio, but it did not become a dominant global antihypertensive.
Generic-entry phase
Generic entry caused the expected reduction in branded revenue and average selling price. Pharmacy substitution redirected demand toward ANDA holders. The product became a volume-and-supply business rather than a brand-premium business.
Current phase
Current revenue is likely fragmented across generic manufacturers and wholesalers. The economic profile is characterized by:
| Metric |
Current direction |
| Unit price |
Low and under generic pressure |
| Prescription growth |
Limited |
| Gross margin |
Sensitive to manufacturing scale |
| Marketing expenditure |
Minimal |
| Clinical-development spending |
Minimal |
| Brand value |
Low |
| Supply-chain value |
More important than brand recognition |
| Revenue visibility |
Poor because companies do not report it separately |
The product may generate recurring revenue for manufacturers with efficient production and established distribution, but it is unlikely to support significant standalone investment.
What generic entry risks exist for isradipine?
Generic entry risk is already realized rather than prospective. The principal competitive risk is not a future Paragraph IV launch. It is further price erosion and supplier rationalization.
A new generic entrant could reduce prices, but the effect would depend on current supplier count and procurement contracts. In a small market, additional entry can produce disproportionate margin pressure while adding little total demand.
Generic launch scenarios
| Scenario |
Likely effect |
| Existing suppliers remain active |
Stable low-price niche market |
| One supplier exits |
Temporary supply constraints and possible price recovery |
| New supplier enters |
Lower prices and reduced incumbent margins |
| Extended-release product returns |
Limited substitution unless reimbursement and clinical demand support it |
| Shortage or quality event |
Volatile availability; potential temporary wholesaler repricing |
Is biosimilar risk relevant to isradipine?
No. Isradipine is a chemically synthesized small molecule, not a biologic. The relevant competitive pathway is generic substitution under the Hatch-Waxman framework, not biosimilar competition under the Biologics Price Competition and Innovation Act.[2]
How strong is the patent estate for isradipine?
The patent estate is weak from a commercial-protection perspective. Its strengths are historical rather than current.
| Patent-estate factor |
Assessment |
| Composition-of-matter protection |
Expired |
| Current exclusivity |
None of material commercial value |
| Formulation differentiation |
Limited and historically focused |
| Method-of-use protection |
No material barrier identified |
| Generic blocking power |
Low |
| Litigation leverage |
Low |
| Manufacturing barriers |
Moderate only if supplier scale or API access is constrained |
| Geographic consistency |
Uneven; rights and approvals vary by country |
Manufacturing capability is more important than patent protection. Isradipine requires controlled production, validated analytical methods, regulatory compliance, and stable API sourcing. These requirements create operating barriers, but they do not create durable exclusivity.
Which companies compete in the isradipine market?
Competition is likely distributed among generic manufacturers, contract manufacturers, specialty suppliers, and regional distributors. Public product databases and package labels identify market participants by country and dosage form, but manufacturers can change over time as products are transferred, discontinued, or relabeled.[4]
The competitive landscape has four layers:
- ANDA holders supplying U.S. pharmacies.
- Contract manufacturers producing for private-label or distributor products.
- API manufacturers supplying regional finished-dose companies.
- National marketing authorization holders outside the United States.
No single manufacturer appears to possess a dominant global isradipine franchise comparable to the leading companies in high-volume antihypertensive drugs.
What geographic markets remain commercially relevant?
The United States remains important for regulatory precedent and generic substitution, but it is not necessarily the largest market by unit volume. Isradipine availability varies significantly by country.
European and other international markets may have different:
- brand histories;
- reimbursement rules;
- patent outcomes;
- approved strengths;
- extended-release availability;
- substitution policies; and
- national supplier bases.
A product can remain available in one jurisdiction after discontinuation in another. Geographic fragmentation increases the value of local registrations and distribution relationships, but it does not materially improve the product's global growth profile.
What licensing deals affect isradipine?
No major current licensing transaction is publicly associated with isradipine. Historical commercialization involved originator and regional marketing arrangements, but the product's current economics are generally managed through generic supply, contract manufacturing, and distribution agreements rather than high-value intellectual-property licenses.
A licensing transaction involving isradipine would more likely concern:
- an established local registration;
- a manufacturing transfer;
- a regional distribution right;
- a private-label supply agreement; or
- access to an extended-release formulation.
The absence of a visible current licensing market is consistent with low product differentiation and limited revenue potential.
What is the investment outlook for isradipine?
Isradipine has limited upside as a standalone pharmaceutical asset. Its value is primarily defensive or operational.
Potentially attractive characteristics include:
- established FDA approval;
- known safety and pharmacology;
- low clinical-development requirements for ordinary generic supply;
- possible niche demand from prescribers who continue using the product;
- modest working-capital requirements relative to new-drug development.
The principal drawbacks are stronger:
- low pricing;
- small market size;
- high substitution risk;
- limited brand loyalty;
- weak patent protection;
- low potential for meaningful prescription growth;
- exposure to manufacturing and API disruptions; and
- limited strategic fit for large pharmaceutical companies.
The most defensible commercial thesis is a low-cost, reliable-supply strategy. A growth thesis based on premium pricing, new indications, or patent-backed market protection is weak.
Key Takeaways
- Isradipine is a mature FDA-approved calcium-channel blocker with limited current commercial scale.
- Dynacirc's branded economics have been replaced by a low-price generic market.
- Original patent and exclusivity protections are no longer material to U.S. market access.
- No active Orange Book patent estate appears to block ordinary generic entry.
- No meaningful current Paragraph IV litigation or settlement structure shapes the market.
- Biosimilar competition is irrelevant because isradipine is a small-molecule drug.
- Public companies generally do not disclose standalone isradipine revenue.
- Future value depends on manufacturing efficiency, API supply, registration coverage, and distributor access.
- Isradipine is more likely to remain a niche maintenance product than become a growth asset.
FAQs About Isradipine Market and Patent Risk
Is isradipine still available in the United States?
Generic isradipine capsules have historically remained available through approved suppliers, although availability can vary by manufacturer, wholesaler, and dosage strength. The former Dynacirc brand is not the primary commercial source.
Can a company obtain new patents on isradipine?
A new patent could cover a genuinely novel formulation, manufacturing process, combination, or delivery system. A basic patent on the known active ingredient would not provide a viable new exclusivity position.
Is isradipine a good candidate for 505(b)(2) development?
The opportunity is limited. A 505(b)(2) strategy could theoretically support a differentiated formulation or delivery system, but the small market and low price ceiling make the return profile difficult unless the product addresses a clear clinical or adherence need.
What would cause isradipine prices to increase?
The most likely cause would be supplier withdrawal, API disruption, manufacturing failure, or a quality-related shortage. Demand growth alone is unlikely to produce sustained pricing power in a highly substitutable antihypertensive market.
Does isradipine have meaningful licensing value?
Standalone licensing value is low. The strongest potential value would come from a regional registration, reliable manufacturing capability, or a differentiated extended-release product rather than from the active ingredient's historical patents.
References
- U.S. Food and Drug Administration. (2010). Dynacirc (isradipine) capsules prescribing information. FDA.
- U.S. Food and Drug Administration. (2024). Small business assistance: Frequently asked questions for the generic drug industry. FDA.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
- U.S. National Library of Medicine. (2024). DailyMed: Isradipine drug labels. National Library of Medicine.