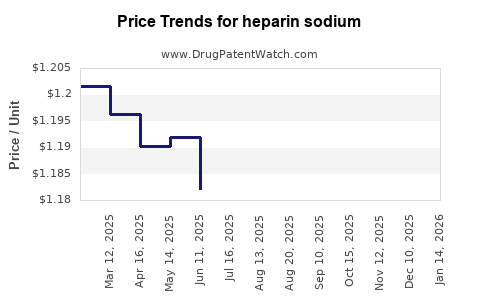
Last updated: October 11, 2026
Heparin sodium is a mature, largely generic anticoagulant with low regulatory exclusivity and limited patent protection. Its commercial value comes from high hospital utilization, critical-care demand, and manufacturing complexity rather than from proprietary pricing. The market is fragmented among injectable manufacturers, distributors, and hospital suppliers. Financial performance is shaped by supply reliability, raw-material access, procurement contracts, and periodic shortages.
Unfractionated heparin remains clinically important for surgery, dialysis, extracorporeal circuits, acute coronary syndromes, venous thromboembolism treatment, and intensive-care use. Low-molecular-weight heparins and direct oral anticoagulants have displaced some use, but they have not eliminated demand for injectable heparin sodium.
What is the current market position of heparin sodium?
Heparin sodium is a hospital-administered anticoagulant sold primarily as an injectable solution or concentrate. The main commercial presentations include:
| Product characteristic |
Commercial relevance |
| Active ingredient |
Unfractionated heparin sodium |
| Main dosage forms |
Intravenous and subcutaneous injection |
| Common strengths |
1,000, 5,000, 10,000, and 20,000 units/mL; institutional presentations vary |
| Primary customers |
Hospitals, dialysis centers, surgery centers, emergency departments, wholesalers |
| Regulatory category |
Prescription drug; largely generic market |
| Market structure |
Multiple suppliers with limited product differentiation |
| Principal cost drivers |
Porcine mucosal raw material, quality testing, sterile manufacturing, labor, freight, and procurement pricing |
| Main substitutes |
Low-molecular-weight heparin, fondaparinux, direct oral anticoagulants, and selected parenteral anticoagulants |
Demand is relatively inelastic in acute-care settings. Hospitals can reduce discretionary use or switch to alternative anticoagulants, but they cannot remove unfractionated heparin from many surgical, dialysis, and extracorporeal protocols.
Heparin is also used in medical devices and procedures, including catheter flushes and extracorporeal blood circuits. Device-related demand creates an adjacent market that is separate from standard therapeutic injection sales.
How large is the heparin sodium market?
No single public source reports a clean, audited global revenue total for unfractionated heparin sodium alone. Commercial market reports often combine unfractionated heparin with low-molecular-weight heparins, hospital products, and sometimes heparin-coated devices. Those aggregated estimates overstate the addressable market for heparin sodium injection.
The commercially relevant conclusions are clearer than the headline market estimates:
- Unfractionated heparin is a large-volume hospital generic.
- Revenue growth is limited by mature pricing and substitution.
- Shortages can produce temporary price increases and supplier share gains.
- Stable long-term growth depends more on procedure volumes and hospital utilization than on new indications.
- The largest economic risk is supply interruption, not patent expiry.
In the United States, heparin sodium is purchased mainly through group purchasing organizations, hospital systems, distributors, and government contracts. Contract pricing suppresses unit revenue, while shortage conditions can shift purchasing toward secondary suppliers and higher-priced presentations.
Which companies compete in heparin sodium?
The competitive field includes multinational pharmaceutical companies, injectable-specialty manufacturers, and generic suppliers. Market participation varies by strength, vial size, preservative status, and institutional contract.
| Company or supplier group |
Typical market role |
| Pfizer/Hospira |
Hospital injectable portfolio and branded legacy supply |
| Fresenius Kabi |
Injectable hospital products, including anticoagulation products in selected markets |
| Hikma Pharmaceuticals |
Generic injectable hospital supplier |
| Sagent Pharmaceuticals |
Hospital injectable portfolio and generic supply |
| B. Braun |
Hospital and procedural products, including anticoagulation-related products in certain markets |
| Regional generic manufacturers |
Supplemental supply and tender-based competition |
| Contract manufacturers and distributors |
Fill-finish, packaging, and institutional distribution |
Supplier participation changes by jurisdiction. A company may have regulatory approval but limited commercial availability, while another may supply through a distributor or institutional contract without significant retail visibility.
Public companies generally do not disclose heparin sodium revenue as a separate reporting segment. Heparin sales are usually included within generic injectables, hospital products, or specialty pharmaceutical revenue. Product-level revenue exposure therefore cannot be inferred reliably from total company sales.
When does heparin sodium lose exclusivity?
Heparin sodium has no meaningful remaining composition-of-matter exclusivity. The active ingredient has been used clinically for decades, and the foundational patents associated with heparin chemistry, extraction, and therapeutic use expired long ago.
| Exclusivity category |
Current position |
| New chemical entity exclusivity |
Not applicable |
| Orphan-drug exclusivity |
Not applicable for standard heparin sodium injection |
| Pediatric exclusivity |
No material current exclusivity identified for the core product |
| Composition-of-matter patent |
Expired |
| Core method-of-use patent |
Expired |
| Formulation patent protection |
Limited and generally product-specific |
| Generic competition |
Established |
| Biosimilar exclusivity |
Not applicable |
The commercial question is not whether the active ingredient remains protected. It does not. The question is whether an individual supplier can maintain availability, satisfy quality requirements, and win institutional contracts.
What patents protect heparin sodium?
No active foundational patent estate protects heparin sodium as a therapeutic molecule. Heparin is a naturally derived, structurally heterogeneous polysaccharide rather than a single small-molecule chemical entity.
Potentially relevant intellectual-property categories include:
- Manufacturing processes for extraction from porcine intestinal mucosa.
- Purification and viral or adventitious-agent control.
- Fractionation and molecular-weight control.
- Depolymerization processes used to produce low-molecular-weight heparin.
- Analytical methods for potency, impurities, and structural characterization.
- Device coatings and heparin-bonded surfaces.
- Combination products and specialized delivery systems.
- Packaging and preservative systems.
These categories do not recreate exclusivity over standard heparin sodium injection. They may protect a particular manufacturing process or device, but competitors can often use alternative processes if they meet pharmacopeial and FDA requirements.
How strong is the patent estate for heparin sodium?
The patent estate is weak for conventional unfractionated heparin and stronger for selected adjacent products.
| Asset type |
Patent strength |
Commercial effect |
| Standard heparin sodium injection |
Low |
Commodity generic competition |
| Specialized prefilled syringes |
Low to moderate |
Packaging and device differentiation |
| Heparin-coated devices |
Moderate in selected products |
Device-specific protection |
| Low-molecular-weight heparin manufacturing |
Moderate |
Process and product complexity |
| Novel anticoagulant combinations |
Product-dependent |
May carry formulation or method claims |
| Purification and analytical processes |
Moderate |
Can raise entry costs without blocking all entry |
The primary barrier is technical execution. Heparin production requires consistent sourcing, purification, potency control, and impurity testing. The absence of a broad patent does not make entry operationally easy.
What is the FDA regulatory status of heparin sodium?
FDA-approved heparin sodium products are prescription anticoagulants regulated as drugs. Conventional heparin sodium injection is not treated like a modern recombinant biologic or a biosimilar reference product.
The regulatory pathway is generally an NDA or ANDA-based drug pathway, depending on the product and approval history. Generic applicants must demonstrate pharmaceutical equivalence and satisfy manufacturing, quality, sterility, potency, labeling, and stability requirements.
FDA scrutiny of heparin intensified after the 2007-2008 contamination crisis involving oversulfated chondroitin sulfate. The event caused severe adverse reactions and deaths and led to stronger testing and supply-chain controls. FDA subsequently emphasized source-material controls, identity testing, impurity detection, and manufacturer oversight.[1]
Heparin products may be listed in FDA’s Drugs@FDA database and the Orange Book, but Orange Book status must be reviewed at the individual product and strength level. Standard heparin sodium listings generally do not create a meaningful patent barrier for generic entrants.
What is the Orange Book status of heparin sodium?
The relevant Orange Book position is generally characterized by:
- Multiple approved drug products.
- Established generic competition.
- Limited or no current patent listings that block standard entry.
- Product-specific differences in vial size, concentration, preservative status, and labeling.
- Potential differences between approved products and products commercially available at a given time.
Orange Book review is important for a specific ANDA or NDA because a product may have different listed strengths, dosage forms, or certifications. The absence of a blocking patent does not guarantee immediate launch. FDA approval, commercial manufacturing capacity, supply contracts, and product availability remain separate issues.[2]
Are there Paragraph IV challenges to heparin sodium?
Paragraph IV litigation is not a central market feature for conventional heparin sodium. The product is old, heavily genericized, and lacks the high-value patent estate that usually motivates aggressive Hatch-Waxman litigation.
Generic applicants could theoretically challenge a listed patent under Paragraph IV certification. In practice, the more important entry risks are:
- FDA approval delays.
- Deficiency letters related to chemistry, manufacturing, and controls.
- Sterility or particulate findings.
- Raw-material shortages.
- Supplier qualification failures.
- Inability to obtain hospital contracts.
- Product recalls or manufacturing interruptions.
This differs from newer anticoagulants, where composition, formulation, or method-of-use patents can support substantial litigation and settlements.
What formulation patents protect heparin sodium?
Standard multidose and single-dose injectable formulations have limited differentiation. Formulation-related intellectual property may concern:
- Preservative-free presentations.
- Low-volume high-concentration products.
- Prefilled syringes.
- Ready-to-use infusion bags.
- Container closure systems.
- Stability improvements.
- Compatibility with infusion pumps.
- Heparin-containing catheter-lock products.
These rights are generally narrower than a patent on the active ingredient. They can protect a particular presentation but usually do not prevent competitors from selling heparin sodium in a different vial, concentration, or delivery format.
The commercial value of a formulation patent depends on whether hospitals have adopted the presentation into medication-safety protocols. A prefilled syringe can command a premium if it reduces preparation errors and labor, even when the underlying heparin is commoditized.
What manufacturing and supply-chain barriers affect heparin sodium?
Manufacturing complexity is the strongest durable barrier to supply.
Raw-material dependence
Commercial heparin is predominantly derived from porcine intestinal mucosa. Production depends on slaughterhouse collection, regional animal-health controls, transportation, and traceability. A disruption in pork-processing capacity can affect pharmaceutical heparin supply.
China has historically been a major source of heparin raw material and intermediates. Geographic concentration creates exposure to export controls, inspection restrictions, transportation disruptions, and local supply shocks.[3]
Quality-control requirements
Manufacturers must control:
- Potency and anticoagulant activity.
- Identity and molecular characteristics.
- Oversulfated or non-native contaminants.
- Microbial and endotoxin burden.
- Residual process impurities.
- Sterility and particulate matter.
- Batch-to-batch consistency.
The 2008 contamination event demonstrated that supply-chain opacity can create systemic product risk. FDA and international regulators consequently increased attention to traceability and testing.[1]
Sterile injectable capacity
Heparin sodium is subject to the same capacity constraints affecting other sterile injectables. Plants with constrained fill-finish capacity may prioritize products based on contract economics, clinical need, and supply commitments. A company with an approved product but no dependable manufacturing slot may have little practical market share.
What caused heparin sodium shortages and price volatility?
Heparin shortages have been linked to raw-material constraints, manufacturing interruptions, increased demand, and supplier exits. FDA’s Drug Shortages database has repeatedly identified heparin and related anticoagulant products as products requiring supply monitoring.[4]
Shortage dynamics can produce temporary financial benefits for remaining suppliers, but those gains are unstable. Hospitals may accept higher prices to secure supply, while distributors ration inventory and shift orders between manufacturers. Once supply normalizes, pricing usually moves toward contract levels.
COVID-19 increased clinical attention to anticoagulation and created demand volatility for hospital anticoagulants. It also disrupted elective procedures, global logistics, and manufacturing operations. The effect on heparin demand was mixed: intensive-care and extracorporeal uses rose, while some elective procedures declined.
How does heparin sodium compare with competing anticoagulants?
| Product class |
Main advantage |
Main limitation |
Effect on heparin sodium |
| Unfractionated heparin |
Rapid onset, short half-life, reversibility with protamine, low cost |
Monitoring burden and variable response |
Retains hospital and procedural demand |
| Low-molecular-weight heparin |
More predictable dosing and outpatient convenience |
Renal dosing and reversal limitations |
Replaces some routine heparin use |
| Direct oral anticoagulants |
Oral administration and reduced monitoring |
Not suitable for all acute or procedural settings |
Reduces long-term injectable demand |
| Fondaparinux |
Predictable factor Xa inhibition |
Limited reversal and renal restrictions |
Niche alternative |
| Bivalirudin and argatroban |
Useful in selected procedural or HIT settings |
Higher cost |
Specialty substitutes rather than broad replacements |
Heparin retains advantages in cardiac surgery, dialysis, extracorporeal support, severe renal impairment, and settings requiring rapid titration or reversal. Low-molecular-weight heparin and direct oral anticoagulants exert the strongest substitution pressure in routine thromboembolism management.
What is the financial trajectory for heparin sodium?
The financial trajectory is mature, volume-sensitive, and operationally driven.
Base case
Revenue remains broadly stable or grows slowly with hospital procedure volumes, dialysis activity, aging populations, and continued use in critical care. Unit prices remain constrained by generic competition and group purchasing contracts.
Upside case
Supplier revenue can increase when:
- A competitor exits the market.
- A shortage shifts contracts to the supplier.
- A manufacturer launches a differentiated prefilled or ready-to-use presentation.
- Hospital systems prioritize supply resilience over lowest unit price.
- Sterile injectable capacity becomes scarce.
Downside case
Revenue can decline when:
- Hospitals substitute low-molecular-weight heparin or direct oral anticoagulants.
- Elective procedures decrease.
- Contract pricing resets downward.
- Raw-material costs rise faster than reimbursement.
- A manufacturer experiences a warning letter, recall, or sterile-production interruption.
The product is therefore financially defensive but not structurally high-growth. Its value is strongest for manufacturers with reliable sterile injectable operations, diversified sourcing, and established hospital distribution.
What generic launch risks exist for heparin sodium?
A new entrant faces low patent risk but meaningful execution risk.
| Risk |
Assessment |
| Patent blocking |
Low |
| FDA approval complexity |
Moderate |
| Raw-material sourcing |
Moderate to high |
| Sterile manufacturing |
High |
| Hospital contract access |
High |
| Pricing pressure |
High |
| Product differentiation |
Low unless delivery format is specialized |
| Recall exposure |
Material |
| Long-term margin expansion |
Limited |
A generic launch can succeed if it secures reliable heparin raw material, qualifies a compliant sterile facility, and wins institutional contracts. FDA approval alone is insufficient to generate substantial revenue.
Which companies are most exposed to heparin sodium economics?
Exposure is greatest for manufacturers whose injectable portfolios contain a high proportion of mature hospital generics. The impact is smaller for diversified pharmaceutical companies, where heparin revenue is embedded in a broader hospital or generic business.
Public disclosure typically does not isolate heparin sodium sales. Investors should evaluate:
- Injectable segment growth.
- Hospital-product gross margins.
- Number of active sterile facilities.
- FDA inspection history.
- Supply agreements and tender wins.
- Product discontinuations.
- Shortage-related sales commentary.
- Raw-material and freight costs.
- Concentration in U.S. institutional customers.
A supplier with modest heparin sales can still experience disproportionate operational effects if the product is important to hospital contracts or production-line utilization.
What is the litigation and settlement outlook for heparin sodium?
Patent litigation and settlement activity are limited compared with newer anticoagulants. The principal legal risks relate to:
- Product liability.
- Contamination.
- Manufacturing defects.
- False or misleading labeling.
- Procurement and contract disputes.
- Antitrust claims involving supply or distribution.
- Regulatory enforcement following quality failures.
Hatch-Waxman settlement risk is low because there is little economic value in delaying generic entry to a standard heparin sodium injection. Litigation risk increases for specialized delivery systems, combination products, device coatings, and novel heparin-derived products.
Key Takeaways
- Heparin sodium is a mature generic anticoagulant with no meaningful foundational exclusivity.
- The market is driven by hospital demand, dialysis, surgery, intensive care, and extracorporeal procedures.
- Patent and Paragraph IV risks are low for conventional injection products.
- Manufacturing, sterile capacity, raw-material sourcing, and quality control are the principal barriers to entry.
- Low-molecular-weight heparins and direct oral anticoagulants limit growth but do not eliminate unfractionated heparin demand.
- Public companies rarely disclose heparin-specific revenue, making supplier-level financial exposure difficult to isolate.
- Shortages can create temporary pricing power and market-share gains, but the long-term business remains volume-sensitive and margin constrained.
- The strongest commercial opportunity is in reliable supply, prefilled or ready-to-use formats, and hospital-contract execution rather than in new composition patents.
FAQs About Heparin Sodium Market and Patent Risk
Is heparin sodium still under patent protection?
The core active ingredient and foundational therapeutic uses are not protected by active patents. Narrow patents may cover formulations, devices, manufacturing processes, or specialized delivery systems.
Can a generic manufacturer launch heparin sodium without a Paragraph IV challenge?
Usually, yes. Conventional heparin sodium products generally do not present the type of blocking patent estate that requires a major Paragraph IV litigation strategy.
Is heparin sodium a biologic or a biosimilar?
Standard heparin sodium is regulated as a drug, not as a conventional biologic reference product subject to the biosimilar pathway. Its natural-source complexity creates quality and manufacturing challenges but does not make it a biosimilar product.
Why can heparin prices rise if the drug is generic?
Generic status does not guarantee abundant supply. Raw-material shortages, sterile manufacturing interruptions, supplier exits, recalls, and hospital inventory requirements can temporarily raise prices.
Does direct oral anticoagulant adoption threaten heparin sodium revenue?
Yes, primarily in long-term outpatient anticoagulation. The effect is smaller in surgery, dialysis, intensive care, extracorporeal circuits, and other settings requiring rapid titration or reversibility.
References
-
U.S. Food and Drug Administration. (2008). Heparin contamination: Questions and answers. https://www.fda.gov/drugs/postmarket-drug-safety-information-patients-and-providers/heparin-contamination-questions-and-answers
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
-
World Health Organization. (2010). WHO guidelines on drawing blood: Best practices in phlebotomy. https://www.who.int/publications/i/item/9789241599221
-
U.S. Food and Drug Administration. (2024). Drug shortages. https://www.fda.gov/drugs/drug-safety-and-availability/drug-shortages-reports
-
U.S. Pharmacopeial Convention. (2024). Heparin sodium monograph. In United States Pharmacopeia and National Formulary. USP-NF.