Last updated: September 1, 2026
Granisetron is a mature 5-HT3 receptor antagonist used to prevent chemotherapy-induced nausea and vomiting, postoperative nausea and vomiting, and, in selected markets, radiation-induced nausea. Its core market is generic, price-competitive, and fragmented across oral tablets, injectable products, and transdermal systems. The original Kytril franchise has lost meaningful exclusivity, while Sancuso remains differentiated by its transdermal delivery system rather than by a new active ingredient.
Granisetron’s financial trajectory is therefore driven by volume stability, hospital contracting, oncology utilization, supply reliability, and formulation differentiation. Public manufacturers generally do not disclose granisetron revenue separately. The market has limited blockbuster potential but can support durable specialty-generic revenue where suppliers maintain regulatory approvals, sterile-manufacturing capacity, or differentiated delivery technology.
What is granisetron and how is it used?
Granisetron hydrochloride selectively blocks 5-HT3 serotonin receptors. The FDA-approved product categories include:
| Product type |
Primary use |
Commercial position |
| Oral tablets |
Prevention of nausea and vomiting associated with emetogenic chemotherapy and radiation |
Generic, low-cost |
| Intravenous injection |
Chemotherapy-induced nausea and vomiting; postoperative nausea and vomiting |
Hospital and oncology use |
| Transdermal patch |
Prevention of chemotherapy-induced nausea and vomiting |
Differentiated branded or specialty product |
| Oral solution or other presentations |
Limited market availability by country |
Secondary or niche |
Kytril, developed by Roche, was approved in the United States in 1993. Sancuso, a granisetron transdermal system, was approved by the FDA in 2008 and was developed to provide continuous delivery during multi-day chemotherapy regimens.[1][2]
Granisetron competes with ondansetron, palonosetron, dolasetron where available, and newer antiemetic combinations that pair a 5-HT3 antagonist with an NK1 antagonist and dexamethasone.
When did granisetron lose exclusivity?
The original granisetron active-ingredient and core product exclusivity periods have expired. U.S. granisetron tablets and injections are supplied primarily through abbreviated new drug applications, or ANDAs, rather than through an innovator-protected market.
The commercial exclusivity timeline is:
| Milestone |
Approximate timing |
Market effect |
| Kytril FDA approval |
1993 |
Originator launch |
| Core small-molecule exclusivity period |
Expired |
Generic development became possible |
| First broad generic competition |
2000s |
Price compression in oral and injectable products |
| Sancuso FDA approval |
2008 |
New transdermal formulation category |
| Current market |
2020s |
Mature generic base with niche formulation competition |
The exact date on which each competitor entered the market depends on dosage form, strength, ANDA approval, manufacturing site, and regulatory status. Granisetron does not have a meaningful remaining composition-of-matter exclusivity position in the United States.
What patents protect granisetron products?
The core granisetron molecule is no longer the primary source of U.S. patent protection. Patent value, where present, is concentrated in delivery systems, transdermal formulations, manufacturing processes, and selected method-of-use claims.
Sancuso and transdermal formulation protection
Sancuso uses a transdermal delivery system designed to maintain granisetron exposure over several days. Its commercial differentiation depends on:
- Adhesive and backing-layer design
- Drug-release control
- Skin permeation characteristics
- Patch adhesion during chemotherapy
- Dose delivery over the labeled wear period
- Manufacturing consistency
The principal commercial barrier is the complexity of proving pharmaceutical equivalence and comparable transdermal performance, rather than the existence of an active-ingredient patent.
The FDA Orange Book is the controlling source for current U.S. patents and regulatory exclusivities listed against approved products. Patent listings can change through expiration, delisting, administrative correction, or product-specific regulatory actions.[3]
Method-of-use patents
Granisetron method-of-use protection is weaker than it was during the originator period. Broad antiemetic uses are difficult to maintain as enforceable exclusivity after extensive clinical use and publication. Narrower claims may involve:
- Specific chemotherapy regimens
- Dosing schedules
- Combination therapy
- Patient subgroups
- Transdermal administration
Generic injectable and oral products can generally enter once applicable listed patents and regulatory exclusivities no longer block approval, subject to ANDA certification requirements.
What is the FDA regulatory status of granisetron?
Granisetron has established FDA regulatory status across multiple dosage forms. FDA-approved products include generic tablets and injections, along with the Sancuso transdermal system.[1][4]
The regulatory profile is favorable because:
- The active ingredient has extensive clinical history.
- Safety and pharmacology are well characterized.
- Generic approval pathways are established.
- Demand is linked to recurring oncology and surgical procedures.
- The product does not require biologic comparability testing.
The main regulatory barriers differ by formulation. Oral tablets usually face conventional bioequivalence requirements. Injectable products face sterile manufacturing, particulate, container-closure, stability, and supply-chain requirements. Transdermal products face more complex equivalence standards involving adhesion, drug release, skin permeation, and residual drug content.
How many patents cover granisetron?
There is no single commercially meaningful patent count for granisetron. The answer depends on whether the analysis includes expired patents, foreign patents, formulation patents, manufacturing patents, and patents owned by companies with no current market relevance.
A practical U.S. classification is:
| Patent category |
Current strategic importance |
| Composition-of-matter patents |
Expired or commercially exhausted |
| Oral formulation patents |
Low |
| Injectable formulation patents |
Low to moderate where manufacturing claims remain relevant |
| Transdermal delivery patents |
Highest remaining formulation relevance |
| Method-of-use patents |
Limited and indication-specific |
| Process and manufacturing patents |
Relevant to cost and supply, usually not a broad market barrier |
The remaining patent estate is therefore better described as formulation- and process-oriented than molecule-oriented. A complete current patent count requires a live review of the USPTO, FDA Orange Book, WIPO, and national registers.
Which companies compete in the granisetron market?
The market includes originator, specialty, hospital-generic, and contract-manufacturing participants. Companies associated with granisetron products in U.S. or international markets have included Roche, Kyowa Kirin, Cumberland Pharmaceuticals, Sandoz, Teva, Hikma, Fresenius Kabi, Dr. Reddy's Laboratories, and other regional generic manufacturers. Product availability varies by country and by dosage form.
Competitive positioning
| Segment |
Main competitors |
Competitive factor |
| Oral granisetron |
Generic manufacturers |
Price, wholesaler access, supply continuity |
| Injectable granisetron |
Hospital suppliers and generic injectables companies |
Sterile capacity, contracts, shortage avoidance |
| Transdermal granisetron |
Sancuso and potential specialty competitors |
Delivery convenience, reimbursement, formulation equivalence |
| Broad antiemetic category |
Ondansetron, palonosetron, NK1 combinations |
Guideline position, duration, regimen efficacy |
Ondansetron is the principal volume competitor because of broad availability and low pricing. Palonosetron competes through longer receptor activity and widespread use in chemotherapy protocols. Net pricing, institutional formularies, and antiemetic guidelines usually matter more than molecular differentiation for generic granisetron.
What are the main market dynamics for granisetron?
Granisetron demand is relatively stable but commercially constrained. The most important drivers are oncology treatment volumes, surgical activity, chemotherapy regimen intensity, hospital purchasing, and drug shortages.
Demand drivers
Chemotherapy remains the most important demand base. Use is supported by:
- Persistent cancer incidence
- Outpatient chemotherapy growth
- Multi-day chemotherapy regimens
- Hospital antiemetic protocols
- Perioperative nausea prevention
The transdermal patch has a narrower but more defensible position because it can reduce repeated oral or intravenous dosing during multi-day chemotherapy. Its commercial performance depends heavily on payer coverage and oncologist preference.
Pricing pressure
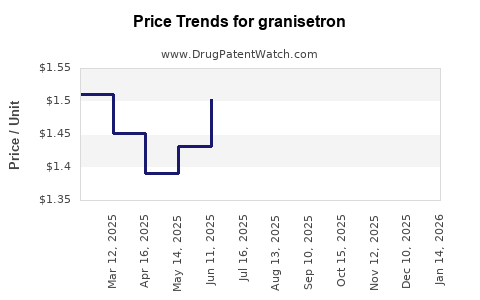
Generic oral granisetron faces substantial price erosion because multiple suppliers can offer therapeutically substitutable products. Injectable pricing is also competitive, but sterile manufacturing failures can produce temporary price increases and allocation opportunities.
The product is not typically a high-growth revenue asset. Supplier economics depend on manufacturing efficiency, contract scale, procurement relationships, and the ability to remain listed and available during shortages.
Supply-chain risk
Injectable granisetron is more exposed to supply disruption than tablets. Risks include:
- Sterile-fill capacity constraints
- Active pharmaceutical ingredient concentration
- Hospital contract losses
- Manufacturing observations
- Container and component shortages
- Low-margin production exits
A supplier with redundant manufacturing and reliable regulatory compliance can preserve share even without patent protection.
What is the financial trajectory for granisetron?
Granisetron revenue has moved from branded originator economics to mature generic economics. The likely trajectory is:
| Period |
Financial profile |
| 1990s |
High-margin branded product with limited competition |
| 2000s |
Generic entry and rapid price compression |
| 2010s |
Stable clinical demand; lower unit economics |
| 2020s |
Mature generic market with episodic shortage-driven pricing |
| Forward outlook |
Low structural growth, with niche upside in transdermal and reliable injectable supply |
No major public company generally reports granisetron as a standalone revenue line. Financial analysis must therefore use product-level prescription data, hospital procurement data, distributor records, or company filings that identify individual product sales.
The strongest revenue opportunities are not based on broad market expansion. They are based on:
- Capturing hospital tenders.
- Maintaining injectable supply during competitor disruptions.
- Selling higher-value transdermal products.
- Expanding into underpenetrated international markets.
- Reducing manufacturing cost through scale.
- Retaining reimbursement for differentiated delivery.
Sancuso has a higher potential net price than generic tablets or injections, but its addressable market is narrower. Its financial performance is sensitive to oncology practice patterns, patch reimbursement, competing oral antiemetics, and the availability of lower-cost substitutes.
What generic entry risks exist for granisetron?
Generic entry risk is high for standard oral and injectable granisetron because the core product has long been off patent. Remaining risks are primarily commercial and regulatory:
- Additional ANDA approvals can reduce pricing.
- Hospital tenders can replace incumbent suppliers quickly.
- Buyers can shift to ondansetron or palonosetron.
- Manufacturing interruptions can remove a supplier from formularies.
- Transdermal competitors may require more complex equivalence studies but can still pressure Sancuso if approved.
Paragraph IV litigation risk is limited for the legacy oral and injectable products because the main exclusivity period has expired. The more relevant litigation scenario would involve a challenger to a listed transdermal formulation patent or a dispute over Orange Book listing scope.
What patent litigation and settlement agreements affect granisetron?
Granisetron does not have a widely recognized current U.S. patent litigation profile comparable with protected oncology drugs or biologics. Historical disputes have been more relevant to generic entry and formulation rights than to an active composition patent.
For current diligence, the critical questions are:
- Whether Sancuso has active Orange Book-listed patents.
- Whether any approved generic transdermal product has been filed.
- Whether an ANDA contains a Paragraph IV certification.
- Whether the reference sponsor has sued within the statutory period.
- Whether a settlement restricts launch timing.
- Whether a licensed manufacturer controls supply rights.
Without an active listed patent, a Paragraph IV challenge does not create the same commercial leverage. Generic companies can rely on Paragraph III certifications, patent expiration, or non-infringement and invalidity positions depending on the listed claims.
How does granisetron compare with ondansetron and palonosetron?
| Attribute |
Granisetron |
Ondansetron |
Palonosetron |
| Drug class |
5-HT3 antagonist |
5-HT3 antagonist |
Second-generation 5-HT3 antagonist |
| Core market status |
Generic |
Generic |
Generic and branded history |
| Main dosage forms |
Oral, injectable, transdermal |
Oral, injectable, other formulations |
Injectable, oral in some markets |
| Differentiation |
Transdermal delivery |
Broad availability and low cost |
Longer duration |
| Pricing power |
Low, except patch |
Very low |
Higher in selected settings |
| Patent leverage |
Mainly formulation-based |
Limited for core products |
Product and formulation-specific |
| Main commercial risk |
Substitution and supply |
Extreme price competition |
Protocol and reimbursement substitution |
Granisetron’s best competitive position is not its pharmacology alone. It is dependable supply in standard formulations and convenience in the transdermal segment.
What is the geographic coverage of granisetron?
Granisetron is marketed across the United States, Europe, Japan, and other developed and emerging markets, but product forms differ materially by jurisdiction. The transdermal patch has a narrower geographic footprint than oral and injectable generics.
Geographic commercial performance depends on:
- Local generic registration
- Hospital procurement systems
- National reimbursement
- Oncology treatment volumes
- Patent status by country
- Local manufacturing requirements
- Import and serialization rules
The United States offers the deepest commercial infrastructure but has intense generic pricing pressure. Japan and certain European markets may provide more stable branded or specialty-generic pricing for selected formulations. Emerging markets offer volume potential but carry greater reimbursement, registration, and distribution risk.
Key Takeaways
- Granisetron is a mature generic antiemetic with long-expired core exclusivity.
- Oral and injectable products face high substitution and price pressure.
- Sancuso’s commercial differentiation comes from transdermal delivery, not a new active ingredient.
- Remaining intellectual-property value is concentrated in formulation, delivery, process, and narrow method-of-use claims.
- Paragraph IV risk is limited for legacy products but remains relevant if active transdermal patents are listed.
- Financial growth is likely to be modest and volume-driven.
- The most defensible commercial positions involve sterile supply reliability, hospital contracts, manufacturing scale, and differentiated transdermal delivery.
- Granisetron revenue is generally not disclosed separately by public companies.
- Ondansetron is the main low-cost competitor; palonosetron competes through longer duration and protocol positioning.
FAQs about granisetron market and patent exposure
Is granisetron still under patent in the United States?
The core granisetron molecule and legacy oral and injectable products are no longer protected by meaningful composition-of-matter exclusivity. Current patent analysis should focus on transdermal products, formulation claims, manufacturing processes, and the FDA Orange Book.
Can a generic company launch oral granisetron without a Paragraph IV challenge?
Yes. Depending on the listed patent status and certification basis, a company may rely on patent expiration, a Paragraph III certification, or another applicable ANDA pathway. A Paragraph IV filing is not required where no blocking patent remains.
Why is the granisetron patch more valuable than generic tablets?
The patch provides differentiated delivery over a multi-day chemotherapy period. That convenience can support higher pricing, although reimbursement, clinical preference, and transdermal equivalence requirements constrain the addressable market.
Does granisetron have biosimilar competition?
No. Granisetron is a chemically synthesized small molecule, not a biologic. Competition comes through generic drug applications rather than biosimilar applications.
What could increase granisetron revenue in the future?
The most credible opportunities are injectable supply disruptions, hospital contract wins, transdermal market expansion, international registration, and manufacturing-cost advantages. Broad market growth is likely to remain limited.
References
- U.S. Food and Drug Administration. (1993). Kytril (granisetron hydrochloride) prescribing information.
- U.S. Food and Drug Administration. (2008). Sancuso (granisetron transdermal system) prescribing information.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database.
- National Comprehensive Cancer Network. (2024). NCCN clinical practice guidelines in oncology: Antiemesis.