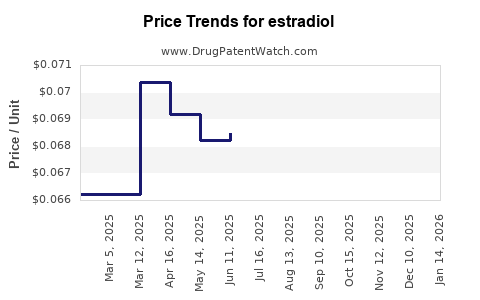
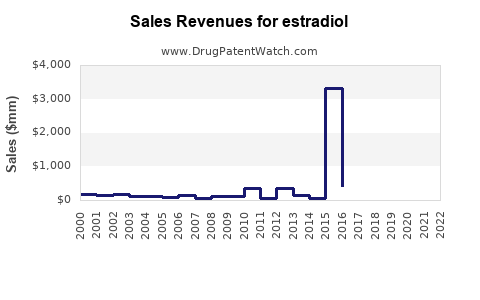
Last updated: August 17, 2026
Estradiol is a mature, multisource pharmaceutical market with low-cost generic tablets and creams competing against branded transdermal, vaginal, and combination products. Market growth is driven by menopause treatment, expanded use of local vaginal estrogen, fertility treatment, gender-affirming care, and rising clinician acceptance of individualized menopausal hormone therapy. Financial performance is shifting from legacy oral products toward differentiated delivery systems, lower-dose vaginal products, combination therapies, and direct-to-consumer channels.
What is the current estradiol market structure?
Estradiol is sold in several therapeutic and delivery categories:
| Segment |
Principal products |
Competitive position |
Pricing profile |
| Oral estradiol |
Estrace tablets and generics |
Highly commoditized |
Low |
| Transdermal patches |
Climara, Vivelle-Dot, generic patches |
Generic competition with device and adhesion differentiation |
Low to moderate |
| Gels and sprays |
EstroGel, Divigel, Evamist |
Fewer suppliers and higher differentiation |
Moderate to high |
| Vaginal creams |
Estrace cream and generics |
Mature generic market |
Low to moderate |
| Vaginal tablets and inserts |
Vagifem, Yuvafem, Imvexxy |
Branded and generic competition |
Moderate to high |
| Vaginal rings |
Estring |
Limited competition and device complexity |
High |
| Estradiol/progestin combinations |
Bijuva, CombiPatch, Climara Pro |
Combination and convenience positioning |
Moderate to high |
| Injectable estradiol |
Estradiol valerate and cypionate |
Specialty and clinic channels |
Variable |
| Compounded products |
Custom creams, capsules, injections |
Price and customization competition |
Variable |
The active pharmaceutical ingredient is generally estradiol, estradiol hemihydrate, or an ester such as estradiol valerate or estradiol cypionate. Product economics depend less on the molecule than on formulation, delivery technology, manufacturing controls, packaging, and regulatory status.
What are the main demand drivers for estradiol?
Menopause treatment is the largest commercial driver for prescription estradiol in the United States and other developed markets. The market has recovered from the post-2002 decline associated with the Women's Health Initiative, although treatment remains below historical utilization levels.
Key demand drivers include:
- An aging population entering perimenopause and menopause.
- Greater use of low-dose vaginal estrogen for genitourinary syndrome of menopause.
- Increased prescribing of transdermal products to reduce concerns about oral estrogen exposure.
- Expanded telehealth and direct-to-consumer menopause services.
- Estradiol use in fertility protocols.
- Gender-affirming hormone therapy.
- Continued use in hypogonadism and selected endocrine indications outside the principal menopause market.
The shift toward lower-dose and local products favors vaginal tablets, inserts, creams, and rings. Transdermal products benefit from physician preference for nonoral delivery, but patch adhesion, skin irritation, supply continuity, and device manufacturing remain commercial constraints.
How large is the estradiol market and what is its financial trajectory?
There is no single audited global revenue figure for estradiol because sales are distributed across generic APIs, prescription products, branded combinations, hospital products, compounding pharmacies, and international markets. Commercial market-research estimates vary materially depending on whether they include compounded products, fertility use, gender-affirming care, and all estrogen-containing combination products.
The financial trajectory has four stages:
| Period |
Market condition |
Financial effect |
| Before 2002 |
Broad use of oral hormone therapy |
High branded revenue and substantial physician adoption |
| 2002-2010 |
Sharp decline after Women's Health Initiative findings |
Lower utilization and reduced valuation of estrogen franchises |
| 2010-2020 |
Growth of transdermal and local vaginal products |
Recovery in differentiated formulations |
| 2020 onward |
Menopause awareness, telehealth, and generic pressure |
Volume growth with uneven pricing and margin performance |
Generic oral tablets and creams exert persistent price pressure. Branded companies generate better economics from products with one or more of the following characteristics:
- A proprietary applicator or insert.
- A low-dose local delivery profile.
- A combination with a progestin.
- A transdermal device or gel with differentiated administration.
- A channel strategy linked to telehealth or specialty distribution.
Standalone estradiol revenue is not separately reported by most diversified pharmaceutical companies. Financial exposure is usually embedded in women's-health or generic portfolios. Mayne Pharma disclosed commercial activity around products acquired from TherapeuticsMD, including Bijuva and Imvexxy, but public reporting does not consistently provide a complete global estradiol revenue line. Perrigo, Teva, Viatris, Amneal, Padagis, and other generic companies also aggregate estradiol sales within broader portfolios.
Which estradiol products have the strongest commercial positions?
Vaginal estradiol products
Vaginal products have the strongest opportunity for branded differentiation. Imvexxy uses a softgel insert designed for vaginal administration, while Vagifem and Yuvafem use vaginal tablets. Estring uses a vaginal ring that releases estradiol over an extended period.
Commercial advantages include low systemic exposure positioning, patient convenience, and physician familiarity. The principal risks are generic entry, reimbursement restrictions, and substitution by lower-cost creams.
Transdermal patches, gels, and sprays
Transdermal products compete on pharmacokinetics, ease of use, skin tolerability, adhesion, and dose flexibility. Generic patches have reduced prices, but product quality can vary by adhesive performance and supply reliability.
Gels and sprays remain less commoditized than oral tablets and creams. Their pricing is more defensible when the product has a distinct applicator, a stable manufacturing process, or a well-developed prescriber base.
Combination products
Bijuva combines estradiol and progesterone in a single oral product. Combination products can reduce pill burden and address endometrial protection requirements for women with an intact uterus. Their commercial value depends on whether payers view the convenience benefit as sufficient to justify a premium over separate generic components.
What patents protect estradiol products?
The estradiol molecule is long off patent. Commercial protection now depends on formulation, dosage form, delivery device, manufacturing process, and method-of-use claims.
| Product or category |
Principal protection type |
General patent position |
| Oral estradiol tablets |
Composition and formulation historically |
Generic and highly exposed |
| Estradiol vaginal cream |
Formulation and manufacturing |
Mature market with generic competition |
| Vagifem/Yuvafem |
Vaginal tablet formulation and use |
Legacy patents with generic competition |
| Estring |
Sustained-release vaginal ring and device |
Older core patents; regulatory and manufacturing barriers remain |
| Transdermal patches |
Adhesive matrix, reservoir, release profile |
Multiple legacy patents; generic entry established |
| Imvexxy |
Softgel insert, formulation, dosing and use |
Later-generation formulation patents provide longer potential protection |
| Bijuva |
Fixed-dose estradiol/progesterone combination |
Combination and formulation claims provide product-specific protection |
| Estradiol gels and sprays |
Formulation, metering, delivery and use |
Protection varies by product and jurisdiction |
Orange Book protection is product-specific. A patent covering a formulation or method of use does not necessarily prevent approval of a generic product that uses a different formulation, label, or delivery system. Conversely, a generic applicant can face regulatory or litigation risk even where the active ingredient itself is unpatented.
When does estradiol lose exclusivity in the United States?
Most legacy estradiol products have already lost market exclusivity. The relevant question is not whether estradiol is off patent, but whether a particular branded dosage form has remaining listed patents or regulatory exclusivity.
| Product |
FDA status |
Exclusivity position |
| Estradiol tablets |
Approved NDA and multiple ANDAs |
No meaningful molecule-level exclusivity |
| Estradiol vaginal cream |
Approved NDA and generic competition |
Mature, multisource market |
| Vagifem |
Approved NDA with generic products |
Product-level protection materially eroded |
| Estring |
Approved NDA |
Older ring technology with more limited direct competition |
| EstroGel and Divigel |
Approved NDAs with generic or competitive exposure |
Formulation protection varies |
| Imvexxy |
Approved NDA |
Later-generation branded product with formulation and use claims |
| Bijuva |
Approved NDA |
Combination-product protection and commercial differentiation |
The FDA Orange Book should be reviewed for the current patent list, pediatric exclusivity, and any approved generic applicants. Listed expiration dates can differ from effective commercial protection because of patent-term adjustment, patent-term extension, pediatric exclusivity, litigation settlements, and generic product design-arounds. The FDA's Drugs@FDA database and Orange Book remain the controlling sources for U.S. regulatory status.[1][2]
What Paragraph IV challenges affect estradiol?
Estradiol has experienced repeated Paragraph IV activity because generic applicants can target high-value branded formulations after the active ingredient has long been genericized.
The most relevant challenge categories are:
- Generic vaginal tablets against Vagifem.
- Generic vaginal inserts against newer softgel products.
- Generic combination products against fixed-dose estradiol/progesterone products.
- Generic transdermal systems against branded patches.
- Formulation challenges involving release rate, particle size, excipients, applicators, and dosage uniformity.
Paragraph IV litigation risk is highest where the branded product has substantial reimbursement and where a generic applicant can obtain approval without reproducing the branded device or formulation exactly. An ANDA applicant may certify that a patent is invalid, unenforceable, or not infringed, then litigate before launch. A successful first filer may obtain 180 days of generic exclusivity, although the practical value depends on competing approvals and litigation outcomes.
What patent litigation and settlements affect estradiol?
Estradiol litigation has generally centered on branded vaginal and combination products rather than the basic active ingredient. Common disputes involve:
- Invalidity and noninfringement of formulation patents.
- Whether a generic label induces infringement of a method-of-use patent.
- The scope of claims covering sustained release or vaginal delivery.
- Patent-term calculations.
- Settlement dates and authorized-generic rights.
Settlement agreements can delay generic launch while avoiding a final court judgment. The financial effect is substantial when the branded product has high unit pricing and limited competition. The effect is smaller for oral tablets and creams, where multiple generic suppliers already constrain net prices.
Company-specific litigation status changes as patents expire, cases settle, or ANDAs receive tentative or final approval. A current Orange Book review must be paired with PACER, district-court dockets, and SEC disclosures. Historical litigation should not be treated as evidence that a patent remains commercially enforceable.
How strong is the estradiol patent estate?
The patent estate is weak for the molecule and mature oral products, moderate for transdermal delivery, and stronger for newer vaginal and fixed-dose combination products.
A practical strength assessment is:
| Patent estate |
Strength |
Main reason |
| Estradiol active ingredient |
Very low |
Long-established generic API |
| Oral tablets |
Very low |
Multiple approved ANDAs and limited formulation differentiation |
| Vaginal cream |
Low |
Long commercial history and generic substitution |
| Transdermal patches |
Moderate |
Device and release-control complexity |
| Vaginal ring |
Moderate |
Device manufacturing and sustained-release requirements |
| Softgel vaginal insert |
Moderate to high |
Product-specific formulation and delivery claims |
| Estradiol/progesterone combination |
Moderate |
Fixed-dose formulation and clinical-use claims |
| Manufacturing process |
Variable |
Can create supply barriers but may be difficult to enforce against competitors |
Manufacturing IP can matter more than nominal patent expiry. Transdermal patches, vaginal rings, softgel inserts, and low-dose products require tight control of content uniformity, release kinetics, packaging, and stability. A supplier with validated manufacturing capacity may retain an advantage even after patents expire.
What is the FDA regulatory status of estradiol?
Estradiol is an FDA-approved prescription estrogen used in oral, transdermal, topical, vaginal, and injectable products. Approval pathways include:
- New drug applications for branded formulations.
- Abbreviated new drug applications for generics.
- Supplemental NDAs for new strengths, dosage forms, or labeling.
- Compounding under sections 503A and 503B, subject to statutory conditions and restrictions.
FDA labeling distinguishes systemic hormone therapy from local vaginal therapy. Product-specific warnings, contraindications, route of administration, and endometrial protection requirements remain important. A product's approval does not establish interchangeability with every other estradiol dosage form. Pharmacy substitution depends on the approved product, dosage form, strength, and state law.
The FDA has also taken steps to modernize labeling for certain low-dose vaginal estrogen products. Label changes can affect physician acceptance and patient demand, but they do not remove the need for product-specific review of systemic exposure and safety information.
Which companies are competing in estradiol?
The competitive field includes originators, generic manufacturers, specialty women's-health companies, and compounders.
Originator and specialty companies
- Bayer: transdermal and women's-health products in selected markets.
- Novo Nordisk: historical women's-health presence, including hormone products in certain jurisdictions.
- Mayne Pharma: commercial rights and products associated with women's health, including Bijuva and Imvexxy.
- TherapeuticsMD: former developer and marketer of Bijuva and Imvexxy before asset transactions.
- Pfizer and legacy Wyeth: historical estrogen and hormone-therapy franchises.
- Besins Healthcare: estradiol gels and other hormone products in international markets.
Generic manufacturers
Teva, Viatris, Amneal, Padagis, Perrigo, Prasco, and other manufacturers participate in different estradiol dosage forms. Participation varies by product and time because of discontinuations, supply constraints, tentative approvals, and commercial decisions.
Compounding pharmacies
Compounded estradiol competes mainly on customization, route, strength, and price. It does not have the same FDA approval framework as an approved commercial product. Compounded products can gain share where patients seek tailored doses or formulations, but quality control and payer coverage can limit adoption.
What generic launch scenarios exist for estradiol?
The likely launch scenarios differ by dosage form:
- Oral tablets and standard creams: Continued price erosion with several suppliers and limited branded retention.
- Transdermal patches: Gradual share transfer because manufacturing and device validation limit the number of reliable suppliers.
- Vaginal tablets: Generic substitution expands as approvals accumulate and payer formularies move toward lower-cost options.
- Vaginal softgel inserts: Slower erosion if formulation patents, applicator differences, or manufacturing complexity delay approval.
- Vaginal rings: Limited direct competition can preserve pricing longer, but a successful generic or alternative device could cause a rapid volume shift.
- Fixed-dose combinations: Generic entry may be delayed by formulation patents and the technical requirements for matching release and bioequivalence.
The most important commercial variable is net price after rebates, not list price. A product can retain a branded label while losing formulary access and prescription volume to a generic or lower-cost alternative.
How does estradiol compare with conjugated estrogens and testosterone products?
Estradiol competes with conjugated estrogens, selective estrogen therapies, progesterone combinations, and testosterone products.
| Product class |
Competitive advantage |
Main limitation |
| Estradiol |
Broad dosage-form range and low-cost generics |
Strong price pressure |
| Conjugated estrogens |
Established clinical brand and differentiated composition |
Higher cost and mature patent position |
| Estradiol/progestin combinations |
Convenience and simplified treatment |
Combination-specific patent and safety considerations |
| Nonhormonal menopause therapies |
Avoid estrogen exposure |
May have lower efficacy for vasomotor or genitourinary symptoms |
| Testosterone products |
Different hormonal target |
Separate safety, regulatory, and prescribing dynamics |
Estradiol has the broadest delivery-system competition. That breadth supports volume but reduces the probability that one company can control the entire category.
What geographic markets are most attractive for estradiol?
The United States remains the most commercially significant market for branded prescription estradiol because of its higher pricing and fragmented delivery-system competition. Europe has substantial demand but more aggressive price regulation and national reimbursement controls. Canada, Australia, Japan, and major Latin American markets provide additional volume, but local registration, reimbursement, and distribution requirements vary.
International patent protection is uneven. A U.S. patent expiration does not establish freedom to operate in Europe, China, Japan, or emerging markets. Companies must review national patent registers, supplementary protection certificates, regulatory data exclusivity, and local substitution rules.
What revenue exposure and investment risks exist?
Estradiol exposure is attractive as a defensive, recurring-volume business but less attractive as a pure high-growth pharmaceutical opportunity.
Primary upside factors include:
- Increased menopause diagnosis and treatment.
- Greater use of low-dose vaginal products.
- Expansion of telehealth prescribing.
- Improved labeling and physician confidence.
- Growth in international and specialty channels.
Primary risks include:
- Generic price erosion.
- Reimbursement restrictions.
- Product recalls or supply interruptions.
- Patent invalidation or early Paragraph IV launch.
- Competing nonhormonal therapies.
- Safety-related changes in labeling.
- Dependence on a small number of API or device manufacturers.
Investors should value estradiol assets by dosage form, market share, net price, remaining patent life, generic pipeline, and manufacturing complexity. Applying a single market multiple to all estradiol products obscures the difference between a commodity tablet and a protected vaginal delivery system.
Key Takeaways
- Estradiol is a mature, multisource pharmaceutical category, not a single commercial product.
- Oral tablets and standard creams are heavily commoditized.
- Vaginal inserts, rings, gels, sprays, patches, and fixed-dose combinations retain greater commercial differentiation.
- The molecule has no meaningful remaining U.S. exclusivity; product-level patents determine launch risk.
- Paragraph IV activity is concentrated in branded delivery systems and combination products.
- Generic entry is likely to produce rapid price erosion in tablets and creams, but slower erosion in technically complex vaginal and transdermal products.
- Financial growth depends on formulation mix, channel expansion, and branded local-delivery products rather than on the estradiol API.
- No major pharmaceutical company reports a complete standalone global estradiol revenue line, limiting precise category-level financial attribution.
FAQs About Estradiol Market and Patent Risk
Is estradiol still a profitable pharmaceutical product?
Yes, but profitability varies sharply by formulation. Generic tablets generate volume with thin margins, while branded vaginal inserts, rings, gels, sprays, and combination products can support higher net prices.
Does estradiol have biosimilar risk?
No. Estradiol is a chemically synthesized small molecule, so the relevant competitors are generic drugs approved through ANDAs, not biosimilars approved through the biologics pathway.
Can a generic estradiol product be automatically substituted for every branded product?
No. Substitution depends on dosage form, strength, FDA equivalence rating, state pharmacy law, and payer policy. A generic tablet is not interchangeable with a patch, ring, gel, or vaginal insert solely because all contain estradiol.
Are compounded estradiol products FDA-approved?
Most compounded estradiol products are not FDA-approved finished drugs. They are prepared under applicable compounding provisions and compete with approved products on customization and price.
What is the largest long-term commercial threat to branded estradiol?
Generic entry is the immediate threat. Over a longer period, payer restrictions, low-cost compounded alternatives, nonhormonal menopause treatments, and competing delivery systems may reduce branded prescription volume.
References
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: The Orange Book. https://www.fda.gov/drugs/drug-approvals-and-databases/approved-drug-products-therapeutic-equivalence-evaluations-orange-book
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2003). Menopause and postmenopausal hormone therapy. https://www.fda.gov
-
Women's Health Initiative Investigators. (2002). Risks and benefits of estrogen plus progestin in healthy postmenopausal women. JAMA, 288(3), 321-333.
-
Mayne Pharma Group Limited. (2024). Annual report 2024. https://www.maynepharma.com/investors/
-
U.S. Food and Drug Administration. (2024). Estrogen and estrogen with progestin therapies: Labeling and safety information. https://www.fda.gov/drugs/postmarket-drug-safety-information-patients-and-providers/estrogen-and-estrogen-progestin-therapies-labeling-changes-concerning-postmenopausal-women-risks/