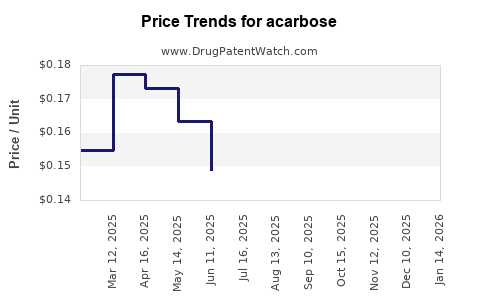
Last updated: September 17, 2026
Acarbose is a mature, low-cost alpha-glucosidase inhibitor used primarily for type 2 diabetes and impaired glucose tolerance. Its branded U.S. lifecycle ended years ago, and the commercial market is now dominated by generic manufacturers, particularly in China and other Asian markets. Revenue growth is limited by low pricing, generic substitution, and competition from metformin, DPP-4 inhibitors, SGLT2 inhibitors, and GLP-1 therapies. Demand remains durable where postprandial glucose control, affordability, and oral administration are priorities.
What is the current global market position of acarbose?
Acarbose occupies a mature segment of the oral antidiabetic market. It is prescribed alone or with other glucose-lowering drugs, especially when post-meal glucose excursions are clinically important.
| Market factor |
Current assessment |
| Primary indication |
Type 2 diabetes; impaired glucose tolerance in some markets |
| Drug class |
Alpha-glucosidase inhibitor |
| Administration |
Oral tablets, generally taken with the first bite of a meal |
| Original innovator |
Bayer |
| Former U.S. brand |
Precose |
| U.S. regulatory status |
Generic drug; original brand lifecycle completed |
| Patent position |
No material active U.S. patent barrier is generally associated with commercial acarbose supply |
| Biosimilar exposure |
None; acarbose is a small-molecule drug |
| Pricing power |
Low |
| Main growth markets |
China, India, Southeast Asia, and selected emerging markets |
| Main competitive threat |
Low-cost metformin and newer agents with stronger cardiovascular, renal, or weight-loss benefits |
Acarbose inhibits intestinal alpha-glucosidases, delaying carbohydrate breakdown and reducing postprandial glucose absorption. The mechanism differentiates it from insulin secretagogues and drugs that act through incretin, renal glucose-excretion, or insulin-sensitization pathways.
Clinical use is constrained by gastrointestinal adverse events, including flatulence, abdominal discomfort, and diarrhea. These effects are related to undigested carbohydrates reaching the colon and frequently affect persistence. The drug also has limited value for patients requiring substantial HbA1c reductions.
When did acarbose lose exclusivity and what is its patent status?
Acarbose has lost U.S. market exclusivity. The product was approved by the FDA as Precose in the 1990s, and generic acarbose tablets subsequently entered the U.S. market after the relevant brand, regulatory, and patent barriers expired.
The original U.S. acarbose estate was tied to the compound, pharmaceutical compositions, and manufacturing technology developed before commercial launch. Those protections are now expired or commercially immaterial in the United States. Current suppliers generally compete through abbreviated new drug applications, manufacturing scale, regulatory compliance, and distribution rather than through differentiated patent portfolios.
What is the Orange Book status of acarbose?
Acarbose has no commercially meaningful active Orange Book patent protection comparable to the late-stage patent estates of newer diabetes products. The former Precose listing is not a current exclusivity barrier to generic entry.
The principal U.S. regulatory route is an abbreviated new drug application demonstrating pharmaceutical equivalence and bioequivalence to the reference product. Because acarbose is an immediate-release oral small molecule, it does not face the clinical-development burden associated with biologics or complex injectables.
What formulation patents protect acarbose?
The core commercial dosage form is an immediate-release oral tablet. Formulation differentiation is limited because:
- The active ingredient is administered locally in the gastrointestinal tract.
- The dose is taken with meals.
- The product does not require an injectable delivery system.
- There is limited commercial rationale for premium extended-release or device-based versions.
- Generic tablets can be manufactured using conventional solid-dose processes.
Any legacy formulation or process patents would generally have expired by the current market period. New patents could theoretically cover modified-release systems, combination products, or manufacturing improvements, but no such protection has created a material barrier to ordinary generic acarbose tablets.
How many patents cover acarbose today?
The number of historical patents associated with acarbose is greater than the number of patents that currently block market entry. Patent families may cover:
- The acarbose compound and related oligosaccharide structures.
- Fermentation or microbial production methods.
- Purification and crystallization processes.
- Tablet compositions.
- Combination use with other antidiabetic agents.
- Methods for treating postprandial hyperglycemia or impaired glucose tolerance.
For commercial analysis, the relevant conclusion is that the U.S. market has no known active core-patent barrier that supports premium pricing for standard acarbose tablets. Geographic conclusions differ because patent term, registration, and enforcement rules vary by country.
Which companies manufacture or compete with acarbose?
The market is fragmented. Bayer is historically associated with Precose and continues to have brand recognition, but generic manufacturers supply most current volume.
Generic manufacturers and regional suppliers
Commercial supply is concentrated among manufacturers with established oral-solid-dose operations. In China, acarbose has had broad use and is supplied by domestic pharmaceutical companies, including producers such as Huadong Medicine and other local generic manufacturers. Availability and market share can vary by provincial procurement lists and hospital tender results.
In the United States, acarbose has been supplied through generic-label pharmaceutical companies and contract manufacturing channels. The U.S. market is smaller than China’s because acarbose is not a preferred first-line therapy and has faced competition from newer diabetes drugs.
Competing drug classes
| Drug class |
Competitive advantage over acarbose |
Limitation relative to acarbose |
| Metformin |
Low cost, guideline position, broad use |
Gastrointestinal intolerance; less targeted postprandial effect |
| Sulfonylureas |
Low price and strong glucose reduction |
Hypoglycemia and weight gain |
| DPP-4 inhibitors |
Better tolerability and simple dosing |
Higher price; less glucose reduction than some alternatives |
| SGLT2 inhibitors |
Cardiovascular, renal, and heart-failure benefits for selected patients |
Cost, genitourinary adverse events, renal restrictions |
| GLP-1 receptor agonists |
Strong glucose reduction and weight loss |
Injection burden for many products and high cost |
| Insulin |
High efficacy |
Hypoglycemia, weight gain, administration burden |
| Acarbose |
Low acquisition cost and postprandial glucose targeting |
Gastrointestinal adverse events and modest HbA1c reduction |
What is the financial trajectory for acarbose?
Acarbose has a mature-product financial profile: stable underlying disease demand, low unit pricing, limited pricing power, and declining value per prescription in developed markets.
There is no consistently reported public financial line for global acarbose sales across all manufacturers. Market-research estimates vary because they may include only branded sales, selected geographies, hospital procurement, retail prescriptions, or active pharmaceutical ingredient revenue. The more reliable commercial indicators are volume, tender pricing, reimbursement status, and manufacturer concentration.
Revenue trajectory by market
| Period |
Financial profile |
| 1990s |
Branded growth following regulatory approvals, led by Precose and Glucobay |
| 2000s |
Expansion in diabetes treatment, followed by generic entry and price erosion |
| 2010s |
Mature generic demand; stronger relevance in China and emerging markets |
| 2020-2024 |
Stable or growing volume in selected Asian markets, with lower prices and rising competition from newer therapies |
| Forward outlook |
Low-single-digit volume growth in some emerging markets, offset by price erosion and substitution in developed markets |
Acarbose can generate meaningful aggregate revenue through high prescription volume, but individual products usually have limited margins unless a manufacturer has scale, low production costs, favorable procurement access, or a strong regional position.
What drives acarbose demand in China and other Asian markets?
China is the most commercially important market for acarbose. Several factors support demand:
- High prevalence of type 2 diabetes.
- Large numbers of patients with postprandial hyperglycemia.
- Broad use of oral therapies.
- Lower affordability than branded GLP-1 or SGLT2 products.
- Physician familiarity with acarbose.
- Use in hospital and retail channels.
- Reimbursement and centralized procurement access.
Acarbose has been included in Chinese public-health and reimbursement environments, although centralized procurement can reduce manufacturer prices materially. Volume may rise while revenue per tablet declines. This creates a scale-driven market in which manufacturing efficiency and tender participation matter more than brand promotion.
India and Southeast Asia offer additional volume opportunities, but competition from metformin and low-cost sulfonylureas is intense. Local registration, physician preference, and distribution coverage affect commercial performance more than patent protection.
What FDA regulatory status does acarbose have?
The FDA approved Precose tablets for the treatment of type 2 diabetes. Acarbose is now available through generic approvals in the United States. The product is an oral small molecule and does not require a biologics license application or biosimilar pathway.
The main regulatory risks are standard generic-drug risks:
- Manufacturing deviations.
- Dissolution or assay failures.
- Contamination and data-integrity findings.
- Supply interruptions.
- Labeling or facility-compliance action.
- Withdrawal from a low-margin market.
Because many generic companies may have limited U.S. commercial incentives, a manufacturer exit can reduce supplier diversity even where the drug remains clinically available.
Which companies are challenging acarbose patents through Paragraph IV filings?
No active, commercially significant Paragraph IV dispute is generally associated with the current acarbose market. Paragraph IV litigation was relevant to the historical generic-entry process, but the product is now a mature generic drug with no known patent dispute that materially delays U.S. entry.
The more relevant competition is post-entry price competition among approved suppliers. This differs from newer diabetes products, where Paragraph IV litigation can determine the launch date of multiple generic entrants and affect billions of dollars in branded revenue.
What patent litigation and settlement agreements affect acarbose?
Acarbose does not have a material current U.S. patent-litigation profile. There is no widely reported settlement structure that controls near-term generic launch timing for standard acarbose tablets.
Any historic litigation would have had greater relevance during the transition from Precose exclusivity to generic availability. At present, commercial outcomes depend primarily on:
- Generic approval status.
- Product availability.
- Manufacturing cost.
- Reimbursement.
- Tender awards.
- Regional demand.
- Quality compliance.
How strong is the acarbose patent estate?
The current patent estate is weak as a commercial defense. The compound is old, the principal tablet dosage form is conventional, and generic substitution is established.
| Patent-estate factor |
Assessment |
| Core compound protection |
Expired |
| Standard tablet protection |
Expired or commercially ineffective |
| Method-of-use protection |
No material barrier for ordinary diabetes treatment |
| Manufacturing-process protection |
Potentially relevant to individual suppliers, but unlikely to block all competitors |
| Combination-product protection |
Limited commercial significance unless tied to a differentiated approved product |
| Geographic exclusivity |
Varies by country, with no broad global barrier |
| Litigation leverage |
Low |
| Ability to support premium pricing |
Low |
The strongest residual intellectual-property opportunities would be process improvements, impurity control, differentiated combinations, or delivery systems. Those opportunities are unlikely to transform the economics of conventional acarbose tablets unless they produce a clinically meaningful benefit and secure reimbursement.
What generic launch scenarios exist for acarbose?
The U.S. generic market is already established, so the principal launch scenarios concern supply changes rather than first entry.
Base case
Multiple suppliers remain active, prices stay low, and volume follows diabetes prevalence without significant revenue growth. Manufacturers earn modest returns through efficient production and distribution.
Consolidation case
Low prices and limited demand cause smaller suppliers to exit. Remaining manufacturers gain volume but face greater supply responsibility and regulatory concentration risk.
Emerging-market growth case
Acarbose volume expands in China, India, and Southeast Asia as diabetes prevalence rises. Revenue growth remains below volume growth because procurement systems and generic competition reduce prices.
Substitution case
SGLT2 inhibitors, GLP-1 therapies, DPP-4 inhibitors, and fixed-dose combinations replace acarbose in patients who can access newer therapies. Acarbose remains concentrated in cost-sensitive populations and in patients for whom postprandial control is the primary treatment objective.
What manufacturing and intellectual-property barriers affect acarbose?
Acarbose is produced through complex microbial fermentation and downstream purification rather than simple chemical synthesis. That creates technical barriers even though the patent barriers have largely disappeared.
Manufacturing risks include:
- Fermentation yield variability.
- Impurity and related-substance control.
- Batch consistency.
- Purification efficiency.
- Stability of the finished tablet.
- Dependence on qualified active-ingredient suppliers.
- Facility compliance and quality-system requirements.
These barriers can protect an efficient incumbent operationally, but they do not normally prevent a capable generic manufacturer from entering. The commercial advantage is manufacturing know-how and cost control, not exclusionary patent rights.
How does acarbose compare with newer diabetes drugs?
Acarbose is disadvantaged on clinical breadth but retains an affordability position.
| Attribute |
Acarbose |
GLP-1 receptor agonists |
SGLT2 inhibitors |
Metformin |
| Oral option |
Yes |
Some products |
Yes |
Yes |
| Weight loss |
Limited or neutral |
Stronger |
Modest |
Neutral or modest loss |
| Cardiovascular benefit |
Not a principal differentiator |
Established for selected agents |
Established for selected agents |
Longstanding clinical use |
| Renal benefit |
Not a principal differentiator |
Selected agents |
Important for selected patients |
Use limited by renal function |
| Cost |
Low |
High |
Moderate to high |
Very low |
| Main tolerability issue |
Gastrointestinal effects |
Gastrointestinal effects and other class effects |
Genitourinary effects |
Gastrointestinal effects |
| Best commercial segment |
Cost-sensitive, postprandial-control patients |
Weight and cardiometabolic management |
Cardiorenal risk reduction |
Broad first-line therapy |
Acarbose is unlikely to regain branded pricing power without a new formulation, combination product, or clinical positioning that produces a reimbursed benefit beyond glucose lowering.
What is the commercial outlook and revenue exposure for acarbose?
The outlook is stable-to-declining in high-income markets and stable-to-growing in selected emerging markets. Aggregate industry revenue should remain constrained by generic pricing.
For manufacturers, acarbose is most attractive when it provides:
- High manufacturing utilization.
- Access to large hospital or retail channels.
- A strong position in Chinese or regional procurement.
- Low-cost active-ingredient sourcing.
- A broader diabetes portfolio that reduces selling expenses.
- Reliable supply during competitor shortages.
For investors and licensors, acarbose is a volume and execution opportunity rather than a patent-driven growth asset. It has low litigation risk, low exclusivity value, and limited potential for rapid revenue expansion. The main upside comes from geographic expansion, procurement wins, combination products, and manufacturing consolidation.
Key Takeaways
- Acarbose is a mature generic diabetes drug with no material current U.S. patent barrier.
- The former Precose franchise has lost commercial exclusivity.
- China is the most important growth and volume market.
- Generic pricing, centralized procurement, and newer diabetes therapies limit revenue growth.
- The drug has no biosimilar risk because it is a small molecule.
- Manufacturing know-how in fermentation and purification is more important than patent protection.
- Standard acarbose tablets have low pricing power and limited licensing value.
- Future commercial performance depends on volume growth in emerging markets, supplier consolidation, and production efficiency.
- No material current Paragraph IV litigation or settlement structure controls generic entry.
- Acarbose remains commercially viable as a low-cost postprandial glucose therapy but is unlikely to become a high-growth pharmaceutical asset.
Frequently Asked Questions
Is acarbose still patented in the United States?
The core acarbose compound and conventional tablet protections are expired or commercially ineffective in the United States. Generic manufacturers can supply standard acarbose tablets.
Is acarbose a biologic or biosimilar product?
No. Acarbose is a small-molecule oral drug approved through the conventional drug pathway. Biosimilar regulation does not apply.
Does acarbose have exclusivity in China?
China’s commercial protection depends on local patents, registration status, procurement rules, and reimbursement policy. The market is primarily generic and competitive, with pricing heavily influenced by public procurement.
Can a new acarbose formulation obtain patent protection?
A genuinely differentiated formulation, combination, or delivery system could receive patent protection if it satisfies novelty, inventive-step, and other statutory requirements. A conventional tablet reformulation would face a higher risk of weak patent value.
Is acarbose an attractive licensing opportunity?
Acarbose is generally more attractive as part of a broader generic or diabetes portfolio than as a standalone licensing asset. Its value lies in manufacturing scale, regional distribution, and procurement access rather than exclusivity.
References
-
Bayer AG. (1995). Precose (acarbose) tablets prescribing information. U.S. Food and Drug Administration.
-
U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. https://www.accessdata.fda.gov/scripts/cder/daf/
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations. https://www.fda.gov/drugs/drug-approvals-and-databases/orange-book
-
Chiasson, J. L., Josse, R. G., Gomis, R., Hanefeld, M., Karasik, A., & Laakso, M. (2002). Acarbose for prevention of type 2 diabetes mellitus: The STOP-NIDDM randomised trial. The Lancet, 359(9323), 2072-2077.
-
Hanefeld, M., Josse, R. G., Chiasson, J. L., et al. (2004). Acarbose treatment and the risk of cardiovascular disease and hypertension in patients with impaired glucose tolerance. Diabetes Research and Clinical Practice, 65(1), 75-83.
-
American Diabetes Association Professional Practice Committee. (2024). 9. Pharmacologic approaches to glycemic treatment: Standards of care in diabetes-2024. Diabetes Care, 47(Supplement 1), S158-S178.
-
National Medical Products Administration. (2024). Drug registration and regulatory information. https://www.nmpa.gov.cn/