Share This Page
Drug Sales Trends for PROMETHAZINE
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for PROMETHAZINE (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
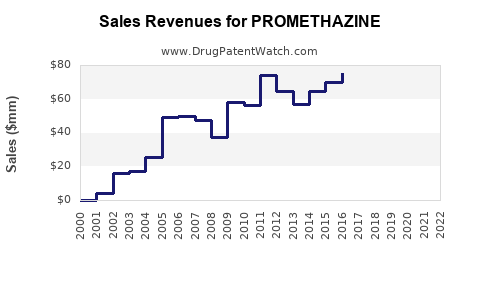
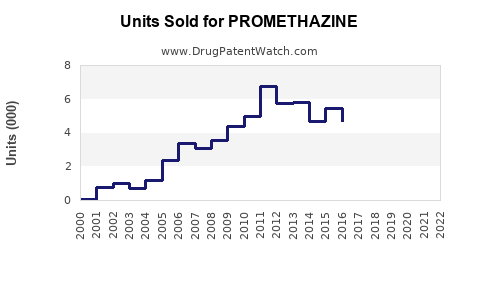
Annual Sales Revenues and Units Sold for PROMETHAZINE
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| PROMETHAZINE | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| PROMETHAZINE | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| PROMETHAZINE | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| PROMETHAZINE | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| PROMETHAZINE | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| PROMETHAZINE | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Promethazine Market Analysis, Patent Status, Competitive Landscape, and Sales Projections
Promethazine is a mature, multisource generic drug with limited pricing power, no meaningful U.S. patent exclusivity, and low barriers to entry for oral and rectal dosage forms. Its market is driven by prescription volume in allergy, nausea, vomiting, motion sickness, and sedation, with additional demand from combination cough products and injectable hospital use. Revenue growth is likely to remain modest and volume-dependent.
A reasonable base-case outlook is flat to low-single-digit annual growth through 2029 in nominal manufacturer revenue, with price erosion offsetting prescription growth. Injectable supply disruptions, product discontinuations, and regulatory restrictions can create temporary price increases in specific channels.
What is promethazine and how is it used?
Promethazine is a first-generation antihistamine and phenothiazine derivative. It has antihistaminic, antiemetic, sedative, and anticholinergic activity.
Common FDA-recognized uses include:
- Allergic conditions and seasonal rhinitis
- Motion sickness
- Nausea and vomiting
- Preoperative and postoperative sedation
- Adjunctive treatment of pain
- Cough and upper-respiratory symptoms when used in combination products
Promethazine is marketed primarily as promethazine hydrochloride. Available dosage forms include tablets, oral solutions, suppositories, and injectable products. Promethazine with codeine oral solution is a separate combination product with additional controlled-substance and abuse-liability considerations.
The FDA label carries a boxed warning against administration to children younger than two years because of the risk of fatal respiratory depression. The label also includes warnings concerning respiratory depression, tissue injury from injection, central nervous system depression, and use with other sedatives.[1]
What is the FDA regulatory status of promethazine?
Promethazine is an established generic drug rather than a newly developed branded therapy. FDA-approved products are marketed under abbreviated new drug applications and legacy new drug applications.
| Regulatory item | Current market position |
|---|---|
| Active ingredient | Promethazine hydrochloride |
| Therapeutic class | Antihistamine; phenothiazine derivative |
| Primary FDA pathways | ANDA products and legacy NDA products |
| Common dosage forms | Tablets, oral solution, suppositories, injection |
| Prescription status | Primarily prescription |
| Controlled-substance status | Promethazine alone is not a federally scheduled controlled substance |
| Combination products | Promethazine with codeine is subject to opioid controls |
| Pediatric restriction | Contraindicated in children under two years |
| Biosimilar pathway | Not applicable |
| Regulatory exclusivity | No commercially relevant current exclusivity identified |
The FDA’s Drugs@FDA and Orange Book databases identify promethazine products and approved generic equivalents. The product is not dependent on a current New Chemical Entity exclusivity period, orphan-drug period, or pediatric exclusivity period.[2][3]
When does promethazine lose patent exclusivity?
Promethazine lost meaningful composition-of-matter and branded-product exclusivity decades ago. Its commercial market is now based on generic competition.
No current U.S. patent estate is known to provide broad exclusivity over promethazine hydrochloride as an active ingredient. Any remaining patents, if listed for a particular product, would be product-specific and could relate to formulation, device, manufacturing, or a combination product rather than the underlying molecule.
Orange Book status
The commercial implications are:
- No material active-ingredient patent barrier
- No meaningful data-exclusivity barrier
- Multiple generic suppliers
- Limited ability to enforce premium pricing
- Product-specific patent risk only for specialized formulations or combinations
Orange Book listings should be reviewed at the individual product level because approval status and manufacturer participation can change. The principal generic opportunity is not a patent-clearance opportunity. It is a manufacturing, supply, channel, and cost-positioning opportunity.[3]
How many patents cover promethazine?
Promethazine has a broad historical patent footprint but little current exclusionary value.
| Patent category | Commercial relevance |
|---|---|
| Original compound patents | Expired |
| Early branded-product patents | Expired |
| Oral dosage-form patents | Generally expired or non-blocking |
| Injectable formulation patents | Potentially relevant only if active and product-specific |
| Combination-product patents | May affect selected cough or analgesic products |
| Manufacturing patents | Could affect a specific supplier, process, or route |
| Device patents | Relevant only to a particular delivery system |
Patent risk is materially higher for a new delivery system than for a standard tablet, oral solution, suppository, or conventional injection. Examples could include controlled-release formulations, abuse-deterrent combinations, ready-to-use injection systems, or proprietary delivery devices. Such products would need separate Orange Book and patent-file review.
What formulations are protected by promethazine patents?
Standard promethazine formulations have low patent protection. The commercial market includes:
- 12.5 mg, 25 mg, and 50 mg tablets
- Oral solutions
- Rectal suppositories
- Promethazine hydrochloride injection
- Promethazine-codeine oral solutions
- Other combination products
Formulation differentiation is more likely to arise from manufacturing economics, stability, preservative systems, packaging, and supply reliability than from enforceable patent rights.
Injection has the highest technical and regulatory barrier. FDA labeling warns of severe tissue injury from improper administration and requires careful handling. Suppliers must manage sterile manufacturing, particulate control, container closure integrity, and hospital procurement requirements.[1]
How strong is the promethazine patent estate?
The patent estate is weak for standard generic products and stronger only at the margins.
| Factor | Assessment | Commercial effect |
|---|---|---|
| Composition-of-matter protection | Very weak | No molecule-level exclusivity |
| Standard oral formulations | Weak | Broad generic competition |
| Suppositories | Weak to moderate | Fewer suppliers may support pricing |
| Injectable product | Moderate operational barrier | Sterile manufacturing limits entry |
| Combination products | Product-specific | Codeine and other actives add regulatory risk |
| Manufacturing processes | Narrow | Usually supplier-specific |
| Pediatric positioning | Regulatory constraint | Limits certain uses rather than protecting revenue |
| Litigation exposure | Low for mature products | Greater risk in shortage or combination markets |
The economic moat is operational rather than intellectual property-based.
Which companies compete in the promethazine market?
Competition varies by dosage form and country. Generic suppliers and contract manufacturers can enter or exit the market based on profitability, FDA inspection outcomes, raw-material availability, and manufacturing capacity.
Relevant competitive groups include:
- Large generic manufacturers with tablet and oral-liquid portfolios
- Specialty manufacturers focused on suppositories
- Sterile injectable manufacturers
- Hospital-focused generic suppliers
- Contract manufacturers supplying private-label products
- Branded or legacy-label suppliers retaining limited channel presence
Akorn historically marketed promethazine products, including injectable products, but its 2023 bankruptcy and asset-sale process changed the competitive environment.[4] Hikma Pharmaceuticals and other hospital-generic suppliers have participated in the broader injectable and generic market, although product availability must be confirmed by current FDA listings and commercial catalogs.[5]
The market is fragmented. No single supplier is likely to control all promethazine dosage forms across retail, hospital, long-term-care, and institutional channels.
What is the market size for promethazine?
A single authoritative public market-size figure is not available because promethazine revenue is split across manufacturers, dosage forms, branded labels, private-label products, wholesalers, hospital contracts, and combination products. Public company filings generally do not report promethazine revenue separately.
Market analysis should separate four revenue pools:
- Retail oral tablets and oral solutions
- Institutional and hospital injection
- Suppositories and specialty dosage forms
- Promethazine-containing combinations
The retail oral segment is the largest by prescription breadth but has the lowest unit economics. Injectable promethazine has a smaller volume base and higher production costs. It can generate disproportionate revenue during shortages or when competitors discontinue sterile products.
The market is mature. Prescription demand is influenced by:
- Allergy and seasonal respiratory disease
- Emergency-department and outpatient antiemetic use
- Motion-sickness demand
- Hospital procedural sedation
- Availability of alternative antiemetics, especially ondansetron
- Pediatric prescribing restrictions
- Declining use of codeine combinations
- Generic price competition
How does promethazine compare with ondansetron?
Ondansetron is the principal competitive alternative in many nausea and vomiting indications.
| Attribute | Promethazine | Ondansetron |
|---|---|---|
| Drug class | First-generation antihistamine/phenothiazine | 5-HT3 antagonist |
| Main demand base | Allergy, nausea, motion sickness, sedation | Nausea and vomiting |
| Sedation | Common | Generally lower |
| Pediatric restriction | Strong warning under age two | Different pediatric labeling profile |
| Generic competition | Extensive | Extensive |
| Hospital use | Injection and oral products | Oral, orally disintegrating, and injectable products |
| Market perception | Low-cost, broad utility | More targeted antiemetic |
| Main risk | Respiratory depression, tissue injury, CNS effects | QT prolongation and other label-specific risks |
Promethazine retains a role where sedation, antihistaminic activity, motion-sickness treatment, or low acquisition cost is important. Ondansetron is often preferred when sedation is undesirable or when antiemetic specificity is prioritized.
What are promethazine sales projections through 2029?
The following projection uses an indexed 2024 manufacturer-revenue baseline of 100. It is designed for strategic planning rather than as reported company guidance. The model assumes stable clinical demand, continuing generic price pressure, no broad withdrawal, and periodic volatility in injectable supply.
| Year | Bear case | Base case | Bull case |
|---|---|---|---|
| 2024 | 100 | 100 | 100 |
| 2025 | 94 | 101 | 106 |
| 2026 | 88 | 102 | 112 |
| 2027 | 83 | 104 | 118 |
| 2028 | 79 | 106 | 124 |
| 2029 | 75 | 108 | 130 |
| Implied CAGR, 2024-2029 | -5.6% | 1.6% | 5.4% |
Base-case assumptions
The base case assumes:
- Oral unit demand grows approximately 1% to 2% annually
- Net pricing declines approximately 1% to 3% annually
- Injectable revenue remains volatile but broadly stable
- No new high-value patented formulation gains meaningful share
- Generic suppliers maintain adequate supply
- Promethazine-codeine demand declines because of opioid controls and prescribing restrictions
- Alternative antiemetics limit growth in nausea and vomiting
The bull case requires supply constraints among competitors, higher hospital utilization, or a supplier gaining share through reliable sterile production. The bear case would follow accelerated substitution by ondansetron and other alternatives, further price erosion, product discontinuations, or regulatory restrictions affecting selected dosage forms.
What revenue exposure does promethazine create for manufacturers?
Promethazine is usually immaterial to the consolidated revenue of diversified pharmaceutical companies. Exposure is more significant for small generic manufacturers with concentrated portfolios.
Commercial exposure depends on:
- Number of dosage forms approved
- Hospital contract concentration
- Injectable production capacity
- Reliance on one manufacturing site
- Raw-material sourcing
- Wholesaler inventory levels
- Participation in shortage-driven tenders
- Ability to maintain FDA compliance
A company with only tablets and oral solution faces high substitution risk and low margins. A company with reliable sterile injection capacity may capture higher revenue per unit but also faces greater quality and regulatory costs.
What generic entry risks exist for promethazine?
Generic entry risk is high because the core products are mature and technically familiar.
The principal barriers are operational:
- FDA approval and bioequivalence requirements
- Sterile manufacturing for injection
- Product-specific stability data
- Supply-chain qualification
- Controlled distribution for codeine combinations
- Hospital contracting
- Pharmacist and wholesaler substitution
- Commercially viable pricing
For standard tablets, entry can be relatively straightforward for an established generic manufacturer. For injection and suppositories, fewer approved suppliers can make entry slower and more capital-intensive.
What litigation and settlement agreements affect promethazine?
No major active patent litigation or market-shaping settlement involving the core promethazine molecule is generally associated with the current U.S. market. Historical litigation, if any, is unlikely to affect standard generic entry because the original exclusivity period has expired.
Combination products containing codeine or other active ingredients can generate separate regulatory, labeling, controlled-substance, or patent issues. Those issues should not be attributed automatically to promethazine alone.
What is the international and geographic market outlook?
The United States is a mature generic market with strong substitution and low pricing. Europe and other developed markets also have extensive generic competition, but product availability and prescription status vary by country.
Emerging markets may offer higher volume growth but lower realized prices. Key geographic variables include:
- Local registration requirements
- National reimbursement policies
- Availability of domestic manufacturers
- Hospital procurement systems
- Rules governing sedating antihistamines
- Restrictions on codeine combinations
- Local pharmacovigilance requirements
A manufacturer pursuing international growth is more likely to gain through registration breadth and low-cost production than through patent exclusivity.
Key Takeaways
- Promethazine is a mature, multisource generic drug with no meaningful current molecule-level exclusivity.
- Standard tablets, oral solutions, and suppositories face high generic competition.
- Injectable promethazine has greater operational barriers because of sterile manufacturing and tissue-injury warnings.
- The market is driven by prescription volume, hospital supply, and product availability rather than patent protection.
- Ondansetron is the main competitive alternative in nausea and vomiting.
- Base-case manufacturer revenue is likely to grow at approximately 1% to 2% annually through 2029.
- Downside risk comes from price erosion, substitution, supplier exits, and reduced use of combination opioid products.
- Upside depends mainly on supply shortages, hospital contracts, and reliable injectable capacity.
- Biosimilar risk is not relevant because promethazine is a small-molecule drug.
- No major active patent litigation or settlement is expected to alter standard generic entry.
FAQs
Does promethazine have an active U.S. patent?
No broad active U.S. patent is known to protect promethazine hydrochloride as a molecule. Product-specific patents must be assessed by dosage form and approved product.
Is promethazine still a profitable generic drug?
It can be profitable for efficient manufacturers, especially in shortage-prone injectable or specialty dosage forms. Standard tablets and oral solutions typically have lower margins because of extensive competition.
Can a new company launch generic promethazine?
Yes. A new entrant would need FDA approval, commercial manufacturing capacity, and reliable distribution. Sterile injection requires substantially greater technical investment than oral tablets.
Is promethazine subject to biosimilar competition?
No. Promethazine is a chemically synthesized small molecule. Competition occurs through generic-drug pathways, not biosimilar approval.
What could cause promethazine prices to rise?
The main triggers are competitor discontinuations, injectable manufacturing problems, FDA enforcement actions, raw-material shortages, hospital tenders, and temporary supply-chain disruptions.
References
- U.S. Food and Drug Administration. (2023). Promethazine hydrochloride injection prescribing information. FDA.
- U.S. Food and Drug Administration. (2024). Drugs@FDA: FDA-approved drugs database. FDA.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations, 44th edition. FDA.
- Akorn Operating Company LLC. (2023). Voluntary petition for relief under Chapter 11 of the U.S. Bankruptcy Code. U.S. Bankruptcy Court.
- Hikma Pharmaceuticals PLC. (2024). Annual report and accounts 2023. Hikma Pharmaceuticals.
More… ↓
