Share This Page
Drug Sales Trends for JANUMET
✉ Email this page to a colleague
Payment Methods and Pharmacy Types for JANUMET (2022)
Revenues by Pharmacy Type
Units Sold by Pharmacy Type
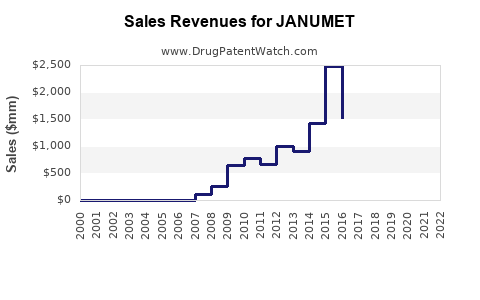
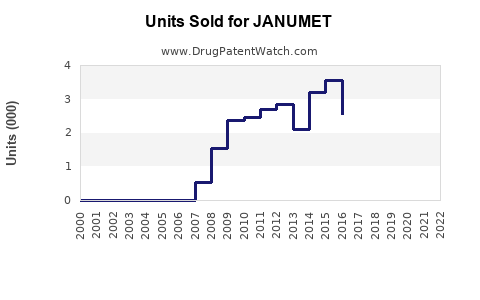
Annual Sales Revenues and Units Sold for JANUMET
| Drug Name | Revenues (USD) | Units | Year |
|---|---|---|---|
| JANUMET | ⤷ Start Trial | ⤷ Start Trial | 2022 |
| JANUMET | ⤷ Start Trial | ⤷ Start Trial | 2021 |
| JANUMET | ⤷ Start Trial | ⤷ Start Trial | 2020 |
| JANUMET | ⤷ Start Trial | ⤷ Start Trial | 2019 |
| JANUMET | ⤷ Start Trial | ⤷ Start Trial | 2018 |
| JANUMET | ⤷ Start Trial | ⤷ Start Trial | 2017 |
| >Drug Name | >Revenues (USD) | >Units | >Year |
Janumet Market Analysis, Sales Projections, Patent Risk, and Generic Entry Outlook
Janumet, Merck’s fixed-dose combination of sitagliptin and metformin, remains a large but declining diabetes franchise. The product benefits from broad physician familiarity, low hypoglycemia risk, and generic metformin economics. Its main commercial weakness is the displacement of DPP-4 inhibitors by GLP-1 receptor agonists and SGLT2 inhibitors, combined with loss-of-exclusivity pressure on sitagliptin.
Merck reported approximately $1.1 billion in Janumet and Janumet XR sales in 2023, down from approximately $1.13 billion in 2022. The base-case model projects global sales declining to approximately $650 million by 2026 and $250 million by 2030 as generic competition expands and treatment shifts toward newer diabetes classes.[1]
What is Janumet and which products are included in the market analysis?
Janumet combines sitagliptin, a DPP-4 inhibitor, with metformin. Janumet XR uses extended-release metformin and is administered once daily in selected strengths.
| Product | Active ingredients | Primary use | Commercial owner |
|---|---|---|---|
| Janumet | Sitagliptin plus immediate-release metformin | Type 2 diabetes | Merck |
| Janumet XR | Sitagliptin plus extended-release metformin | Type 2 diabetes | Merck |
| Januvia | Sitagliptin alone | Type 2 diabetes | Merck |
| Generic sitagliptin/metformin | Sitagliptin plus metformin | Type 2 diabetes | Multiple generic manufacturers |
The FDA-approved indication is treatment of adults with type 2 diabetes as an adjunct to diet and exercise. Janumet is not indicated for type 1 diabetes or diabetic ketoacidosis.[2]
Sitagliptin inhibits DPP-4, increasing endogenous incretin activity. Metformin reduces hepatic glucose production and improves insulin sensitivity. The combination is positioned as an oral, weight-neutral treatment with a relatively low hypoglycemia risk when used without insulin or a sulfonylurea.
How much revenue does Janumet generate?
Merck reports Janumet and Janumet XR sales separately from Januvia. Public company filings indicate the following historical trajectory:
| Year | Reported or estimated Janumet sales | Year-over-year trend |
|---|---|---|
| 2021 | Approximately $1.2 billion | Declining |
| 2022 | Approximately $1.13 billion | Down |
| 2023 | Approximately $1.07 billion | Down |
| 2024 | Approximately $0.9 billion to $1.0 billion estimate | Down |
| 2025E | $0.75 billion to $0.85 billion | Down |
| 2026E | $0.58 billion to $0.68 billion | Down |
| 2027E | $0.45 billion to $0.55 billion | Down |
| 2030E | $0.20 billion to $0.35 billion | Down |
The 2025-2030 figures are market-model estimates rather than Merck guidance. They assume continued erosion in the United States, lower prices in international markets, increasing generic availability, and continuing migration toward GLP-1 and SGLT2 therapies.
Janumet’s revenue profile is more resilient than a single-agent DPP-4 product in some markets because the combination reduces pill burden and provides an inexpensive alternative to newer injectable or branded oral treatments. The combination also benefits from patients who require metformin but need additional glycemic control.
What are the Janumet sales projections through 2030?
Base-case projection
| Year | Estimated global sales | Key assumption |
|---|---|---|
| 2024 | $0.90B-$1.00B | Early price pressure and class substitution |
| 2025 | $0.75B-$0.85B | Greater generic and tender pressure |
| 2026 | $0.58B-$0.68B | Wider generic sitagliptin exposure |
| 2027 | $0.45B-$0.55B | Mature generic erosion |
| 2028 | $0.36B-$0.45B | Stable residual branded demand |
| 2029 | $0.28B-$0.38B | Continued class migration |
| 2030 | $0.20B-$0.35B | Commodity-like pricing in many markets |
Scenario analysis
| Scenario | 2030 sales | Market outcome |
|---|---|---|
| Downside | $100M-$200M | Rapid generic substitution and strong GLP-1 uptake |
| Base case | $200M-$350M | Gradual erosion with durable emerging-market demand |
| Upside | $400M-$600M | Slower generic penetration, stronger oral-treatment demand, and sustained international volume |
The downside case is more likely in the United States and Western Europe. The upside case depends primarily on volume in markets where injectable therapies remain less accessible and out-of-pocket affordability is a major treatment constraint.
Which market segments support Janumet demand?
Primary care and general endocrinology
Janumet is widely used by primary-care physicians because it is familiar, orally administered, and available in multiple dose combinations. Prescribers often use it when metformin alone does not achieve adequate glycemic control and the patient does not require the weight loss associated with GLP-1 therapy.
Older adults
Older patients may favor an oral, weight-neutral regimen over injectable treatment. However, renal function restrictions and the need to adjust or discontinue metformin can limit use in patients with declining kidney function.[2]
International and emerging markets
Emerging markets represent the most durable volume opportunity. Branded Janumet faces price competition, but the underlying combination remains clinically familiar. Merck’s revenue exposure is greatest in countries with large type 2 diabetes populations, established metformin use, and limited access to GLP-1 receptor agonists.
Commercially vulnerable segments
Janumet is exposed to patients who need weight loss, cardiovascular risk reduction, or renal protection. Those treatment objectives favor GLP-1 receptor agonists and SGLT2 inhibitors over DPP-4 inhibitors. Sitagliptin does not have the same weight-loss, heart-failure, or chronic-kidney-disease positioning associated with leading drugs in those classes.[3][4]
How does Janumet compare with GLP-1 and SGLT2 products?
| Attribute | Janumet | GLP-1 receptor agonists | SGLT2 inhibitors |
|---|---|---|---|
| Administration | Oral | Mostly injectable, with some oral options | Oral |
| Weight effect | Generally weight neutral | Weight loss | Modest weight loss |
| Hypoglycemia risk | Low when used alone | Low when used alone | Low when used alone |
| Cardiovascular outcome positioning | Neutral to non-inferior evidence profile | Stronger for selected agents | Stronger for selected agents |
| Kidney outcome positioning | Limited compared with SGLT2 products | Increasing evidence for selected agents | Strong |
| Cost | Low to moderate after generic entry | High | Moderate to high |
| Main commercial role | Glycemic control and convenience | Weight and cardiometabolic benefit | Cardiovascular and renal protection |
Janumet is more likely to retain patients who prioritize oral convenience and affordability than patients whose treatment decisions are driven by weight loss or cardiorenal protection.
The main branded competitors are:
- Januvia, Merck’s sitagliptin monotherapy product.
- Kombiglyze XR, AstraZeneca’s saxagliptin/metformin combination.
- Tradjenta, Boehringer Ingelheim and Eli Lilly’s linagliptin.
- Glyxambi, Jardiance, and other empagliflozin products.
- Ozempic, Rybelsus, and other semaglutide products.
- Trulicity, dulaglutide.
- Mounjaro, tirzepatide.
DPP-4 inhibitors remain relevant where tolerability, oral dosing, and price outweigh the added clinical benefits of newer classes.
When does Janumet lose exclusivity?
Janumet’s exclusivity profile depends on the jurisdiction, product strength, formulation, patent family, pediatric extensions, regulatory exclusivity, and settlement agreements with generic manufacturers.
The core sitagliptin patent estate has historically included patents such as U.S. Patent No. 6,699,871 and related continuation or formulation patents. The relevant U.S. market protection period has extended beyond the original compound patent term through pediatric exclusivity, formulation protection, and litigation settlements.[5]
| Protection category | Commercial effect |
|---|---|
| Sitagliptin compound patents | Protect the active pharmaceutical ingredient |
| Sitagliptin/metformin composition patents | Protect the fixed-dose combination |
| Extended-release formulation patents | Protect Janumet XR product characteristics |
| Method-of-use patents | Cover treatment of type 2 diabetes and dosing methods |
| Regulatory exclusivity | Limits certain approvals independent of patent term |
| Generic settlements | Can establish authorized or licensed launch dates |
The practical loss-of-exclusivity date is therefore not necessarily the expiration date of the earliest listed patent. Generic launch may occur through a license, an authorized generic arrangement, a court decision, or an agreed settlement date.
What patents protect Janumet and Janumet XR?
Janumet’s patent coverage has generally been built around four layers:
- Sitagliptin chemistry and salt forms.
- Fixed-dose sitagliptin/metformin compositions.
- Extended-release metformin formulations.
- Methods for treating type 2 diabetes using the combination.
The strongest remaining commercial protection is formulation and combination protection, not the original DPP-4 mechanism. That distinction matters because generic manufacturers can challenge individual patents while seeking approval for alternative strengths, release profiles, or non-infringing formulations.
For generic applicants, the main technical barriers are:
- Matching sitagliptin strength and stability.
- Demonstrating bioequivalence across immediate-release and extended-release products.
- Controlling metformin release characteristics.
- Establishing dissolution profiles across multiple strengths.
- Avoiding infringement of formulation and combination claims.
What is the FDA and Orange Book status of Janumet?
Janumet and Janumet XR are FDA-approved prescription products. The FDA Orange Book identifies listed patents and regulatory exclusivity associated with approved products. The Orange Book is the primary source for determining which patents a generic applicant must certify against in an abbreviated new drug application.[6]
A Paragraph IV certification asserts that a listed patent is invalid, unenforceable, or will not be infringed. Such a filing can trigger patent litigation under the Hatch-Waxman Act and may create a 30-month stay of final FDA approval, subject to statutory conditions.
The commercial significance of a Paragraph IV challenge depends on:
- Whether the challenged patent is the only blocking patent.
- Whether the generic applicant seeks all strengths or only selected strengths.
- Whether the applicant has a non-infringement position for Janumet XR.
- Whether Merck settles before trial.
- Whether an authorized generic is launched.
- Whether multiple applicants create price competition at the same time.
Which companies are challenging Janumet patents?
Generic competition is likely to involve large manufacturers with established diabetes portfolios, including Teva, Sandoz, Viatris, Lupin, Dr. Reddy’s Laboratories, Sun Pharma, Zydus, and Torrent. The precise applicant and litigation status vary by product strength and jurisdiction.
A generic sitagliptin/metformin applicant may pursue one of three strategies:
| Strategy | Commercial rationale |
|---|---|
| Full-strength ANDA | Maximize substitution across the Janumet franchise |
| Selected strengths | Avoid patents covering specific strengths or formulations |
| Authorized or licensed launch | Enter earlier with lower litigation risk |
Generic entry for Janumet can produce rapid price compression because metformin is already highly commoditized. Sitagliptin provides the remaining value in the combination, but that value falls sharply once multiple suppliers enter.
What patent litigation and settlement risks affect Janumet?
The principal litigation risk is a Hatch-Waxman challenge to combination, formulation, or use patents. Settlement agreements may permit launch before the latest asserted patent expiration. They can also include restrictions on manufacturing source, authorized-generic rights, or launch timing.
The most important litigation outcomes for revenue forecasting are:
- A finding that a formulation patent is invalid.
- A finding of non-infringement for a selected strength.
- A settlement that permits an early generic launch.
- A first-filer arrangement that delays broad competition.
- A Merck authorized generic launch that limits price erosion.
A single early entrant usually causes a moderate price reduction. Multiple simultaneous entrants can reduce net sales by more than 70% within two years, particularly in pharmacy-benefit-manager channels.
What generic launch scenarios exist for Janumet?
Scenario 1: Delayed, controlled entry
Merck retains meaningful branded volume through settlements or remaining formulation patents. Sales decline gradually to approximately $500 million by 2027.
Scenario 2: One major generic entrant
One generic manufacturer launches under a license or after litigation. Janumet sales fall 35% to 55% in the first 12 to 24 months.
Scenario 3: Multiple generic entrants
Several manufacturers enter across key strengths. Branded sales decline 60% to 80%, with the remaining business concentrated in markets where reimbursement favors the originator or where generic registration is slow.
Scenario 4: Authorized-generic defense
Merck or a commercial partner launches an authorized generic. Unit volume remains high, but Merck’s reported revenue shifts from branded pricing to lower-margin generic economics.
How strong is the Janumet patent estate?
Janumet’s patent estate is moderate rather than strong.
| Patent-estate factor | Assessment |
|---|---|
| Core molecule protection | Weak after historical expiry periods |
| Combination protection | Moderate |
| Extended-release formulation protection | Moderate, depending on claim scope |
| Method-of-use protection | Limited practical blocking power after generic substitution |
| Manufacturing barriers | Moderate for XR products |
| Litigation leverage | Highest before the first licensed generic |
| Long-term durability | Low to moderate |
Formulation patents can delay entry, but they rarely preserve high branded prices after the active ingredient becomes broadly available. The most defensible asset is the commercial manufacturing process for stable, bioequivalent extended-release tablets. That barrier can slow entry without preventing it.
What is the competitive outlook for the DPP-4 inhibitor market?
The DPP-4 market is declining in value but remains large in patient volume. Generic sitagliptin, linagliptin, and other DPP-4 products will support continued use where low hypoglycemia risk and oral dosing are priorities.
The market is splitting into two segments:
- Value segment: Generic metformin, sitagliptin, and other low-cost oral regimens.
- Innovation segment: GLP-1, dual incretin, and SGLT2 products selected for weight, cardiovascular, and kidney outcomes.
Janumet is well placed in the value segment but has limited ability to regain premium growth. Product-line extensions, lower-priced versions, and emerging-market expansion can slow decline but are unlikely to offset class-level substitution.
What is Merck’s revenue exposure to Janumet?
Janumet is strategically important but no longer a primary growth driver for Merck. Combined Januvia and Janumet sales were approximately $5.6 billion in 2023, making the franchise material to Merck’s pharmaceutical revenue base.[1]
Janumet alone represents approximately one-fifth of the combined Januvia franchise. Its decline has three financial effects:
- Lower branded diabetes revenue.
- Reduced operating leverage in Merck’s commercial infrastructure.
- Greater dependence on oncology, vaccines, and newer pharmaceutical assets.
The revenue exposure is manageable at the corporate level but material for diabetes-franchise forecasts. Investors should model Janumet as a declining cash-flow product rather than a growth asset.
What licensing deals could change Janumet’s outlook?
Licensing or commercial agreements can affect the timing and severity of generic erosion. Relevant structures include:
- Authorized-generic supply agreements.
- Regional licensing to local manufacturers.
- Settlements allowing defined early entry.
- Co-marketing arrangements in emerging markets.
- Manufacturing licenses for sitagliptin/metformin tablets.
- Portfolio deals bundling Januvia, Janumet, or other mature products.
A regional partner can preserve volume but generally reduces Merck’s net price. A global authorized-generic deal can protect manufacturing scale while accelerating market access.
Key Takeaways
- Janumet sales were approximately $1.07 billion in 2023, based on Merck’s reported product revenue.
- Global sales are projected to decline to approximately $200 million to $350 million by 2030 in the base case.
- The main threats are generic sitagliptin/metformin, GLP-1 receptor agonists, and SGLT2 inhibitors.
- The remaining patent value is concentrated in fixed-dose and extended-release formulation claims.
- Janumet has a moderate patent estate but limited long-term ability to preserve premium pricing.
- A single generic entrant could reduce branded sales by 35% to 55%; multiple entrants could produce 60% to 80% erosion.
- Emerging markets and price-sensitive oral-treatment segments are the most durable sources of demand.
- Janumet is a mature cash-flow product, not a growth product, for Merck.
FAQs
Is Janumet still a commercially important diabetes drug?
Yes. It remains widely used, but its commercial value is declining as generic competition increases and physicians shift patients toward GLP-1 and SGLT2 therapies.
Will generic Janumet be cheaper than branded Janumet?
Yes. Generic sitagliptin/metformin products should receive substantial price discounts, particularly after multiple manufacturers enter and pharmacy-benefit managers shift formulary preference.
Does Janumet have stronger protection than Januvia?
Janumet has additional combination and formulation patents, but those protections do not necessarily provide a longer practical commercial life than Januvia. The outcome depends on the specific strength, formulation, and generic certification.
Is Janumet exposed to biosimilar competition?
No. Janumet is a chemically synthesized small-molecule product, so it faces generic, not biosimilar, competition.
Can Janumet sales recover through emerging markets?
Emerging markets can extend the product’s volume life, but they are unlikely to restore historic revenue because pricing is lower and local generic competition is strong.
References
-
Merck & Co., Inc. (2024). Annual report on Form 10-K for the fiscal year ended December 31, 2023. U.S. Securities and Exchange Commission.
-
U.S. Food and Drug Administration. (2023). Janumet and Janumet XR prescribing information. Merck Sharp & Dohme LLC.
-
American Diabetes Association Professional Practice Committee. (2024). 9. Pharmacologic approaches to glycemic treatment: Standards of care in diabetes-2024. Diabetes Care, 47(Supplement 1), S158-S178.
-
U.S. Food and Drug Administration. (2020). FDA revises labels of SGLT2 inhibitors for diabetes to include warnings about serious genital infections. FDA Drug Safety Communication.
-
U.S. Patent and Trademark Office. (n.d.). Patent Center and patent term information for sitagliptin and sitagliptin/metformin patent families. U.S. Department of Commerce.
-
U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book. FDA.
More… ↓
