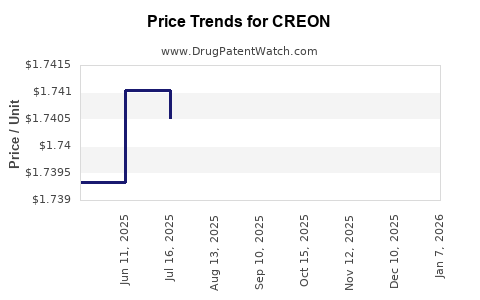
Last updated: September 21, 2026
CREON is AbbVie’s pancrelipase enzyme-replacement product for exocrine pancreatic insufficiency. It is not a biologic under the U.S. Public Health Service Act and does not receive Purple Book treatment. CREON is an orally administered, porcine-derived pancreatic enzyme product regulated through the FDA’s drug pathway.
The product has developed into a large, durable specialty pharmaceutical franchise. Its growth is supported by chronic use, rising diagnosis of exocrine pancreatic insufficiency, limited therapeutic interchangeability, and manufacturing complexity. Its principal risks are supply shortages, generic pancrelipase entry, payer pressure, and the absence of a conventional biologic exclusivity barrier.
What is CREON and how does its FDA regulatory status affect the market?
CREON contains pancrelipase, a mixture of porcine-derived lipase, amylase, and protease. It is supplied as delayed-release capsules that protect the enzymes from gastric acid and release them in the small intestine.
| Attribute |
CREON |
| Active ingredient |
Pancrelipase |
| Product type |
Pancreatic enzyme replacement therapy |
| Dosage form |
Delayed-release capsules |
| Primary indication |
Exocrine pancreatic insufficiency |
| U.S. sponsor |
AbbVie Inc. |
| FDA application |
NDA 020725 |
| Regulatory category |
Small-molecule drug and biological enzyme product, not a BLA biologic |
| Reference product |
CREON delayed-release capsules |
| Main therapeutic settings |
Cystic fibrosis, chronic pancreatitis, pancreatic surgery, pancreatic cancer, other causes of exocrine pancreatic insufficiency |
FDA approval is based on the drug product’s enzyme activity, manufacturing controls, stability, dissolution and clinical performance. The product is not eligible for a conventional biosimilar pathway because it is not licensed under a biologics license application.[1]
Pancrelipase products are also not automatically interchangeable merely because they contain the same nominal enzyme activities. Differences in lipase units, delivery systems, release characteristics and manufacturing controls can affect clinical use. Physicians typically prescribe these products by brand and dose strength.
How large is the CREON market?
CREON is one of AbbVie’s largest non-immunology and non-oncology products. AbbVie’s reported CREON revenue has expanded materially since 2020, supported by higher prescription volume, price increases and continued demand in cystic fibrosis and other chronic pancreatic disorders.
| Fiscal year |
Approximate CREON net revenue |
Direction |
| 2020 |
About $0.9 billion |
Baseline |
| 2021 |
About $1.0 billion |
Growth |
| 2022 |
About $1.2 billion |
Growth |
| 2023 |
About $1.4 billion |
Growth |
| 2024 |
Approximately $1.6 billion |
Continued growth |
The figures reflect AbbVie’s reported product-sales disclosures and rounded presentation. CREON represented roughly 2% to 3% of AbbVie’s total company revenue in 2024, but its contribution to the company’s gastroenterology portfolio was considerably higher.[2][3]
The commercial profile is attractive because treatment is usually chronic. Patients with cystic fibrosis, pancreatic resection, severe chronic pancreatitis or permanent pancreatic insufficiency may require enzyme replacement with every meal and snack. That produces recurring prescription demand rather than episodic treatment demand.
What is driving CREON’s financial growth?
Increasing recognition of exocrine pancreatic insufficiency
Exocrine pancreatic insufficiency is associated with cystic fibrosis, chronic pancreatitis, pancreatic surgery, pancreatic cancer and other gastrointestinal conditions. Diagnosis remains uneven, particularly outside cystic fibrosis centers. Greater testing for fecal elastase, wider recognition of malabsorption and improved survival after pancreatic disease increase the addressable treatment population.
CREON’s growth does not depend solely on new cystic fibrosis diagnoses. Adult patients with chronic pancreatitis and patients who undergo pancreatic surgery represent important commercial segments.
Chronic and dose-intensive use
Patients often take pancrelipase with every meal and snack. Dose titration is based primarily on lipase units and meal fat content. This creates high annual prescription utilization for patients receiving stable long-term therapy.
Product familiarity and physician inertia
CREON has substantial prescribing familiarity among gastroenterologists, pancreatic surgeons, cystic fibrosis specialists and primary-care physicians managing established pancreatic insufficiency. Switching can require dose adjustment and monitoring of gastrointestinal symptoms, which reduces casual substitution.
Limited therapeutic interchangeability
CREON competes with Zenpep, Pertzye and Pancreaze. These products use different formulations and are not identical copies of CREON. Physicians may switch products for formulary, patient-assistance or supply reasons, but the market is not equivalent to a conventional tablet market with broad automatic substitution.
Price and mix
Revenue growth has reflected both unit expansion and price or mix effects. High-dose strengths and chronic users produce meaningful annual revenue per patient. Commercial performance also benefits when patients move from lower to higher prescribed lipase strengths.
Which companies compete with CREON?
The U.S. prescription pancreatic enzyme market is concentrated among a small number of branded products.
| Product |
Company or commercial sponsor |
Competitive position |
| CREON |
AbbVie |
Leading U.S. branded product |
| Zenpep |
Nestlé Health Science |
Major branded competitor |
| Pertzye |
Chiesi USA |
Branded delayed-release pancrelipase |
| Pancreaze |
VIVUS or applicable commercial rights holder |
Smaller branded competitor |
| Generic pancrelipase products |
Multiple manufacturers |
Emerging price-based threat |
Zenpep is the most important branded competitor in many U.S. treatment settings. Pertzye competes through product differentiation, patient support and payer contracting. Pancreaze has a smaller market presence but remains relevant where physicians or payers prefer its formulation.
Competition is influenced by supply availability. During periods when CREON strengths are unavailable, prescribers and pharmacies may shift patients to Zenpep, Pertzye or another pancrelipase product. Some of those patients may remain on the substitute product if coverage, dosing and tolerability are acceptable.
When does CREON lose exclusivity?
CREON does not have a biologic exclusivity period comparable to the 12-year reference-product exclusivity framework for biologics. Its market protection depends on drug patents, formulation technology, regulatory exclusivity, manufacturing complexity and the practical difficulty of developing an equivalent pancrelipase product.
The relevant U.S. exclusivity framework includes:
| Protection |
Relevance to CREON |
| New chemical entity exclusivity |
Generally not the primary protection for a long-established enzyme product |
| Orphan-drug exclusivity |
May apply only to a specific orphan indication and approval, not necessarily the full product |
| Pediatric exclusivity |
Adds six months if granted after qualifying studies |
| Drug patents |
May cover formulation, enzyme preparation, delivery or manufacturing |
| Orange Book listings |
Determine the patent certifications available to ANDA applicants |
| Manufacturing know-how |
Important practical barrier even after patent expiry |
The key commercial question is not a single patent expiration date. It is whether an ANDA applicant can obtain approval for a product that meets FDA requirements and withstands patent litigation or settlement restrictions.
CREON is listed in the FDA Orange Book as an approved drug product rather than in the Purple Book.[4] Orange Book patent status can change through patent expiration, delisting, listing corrections, pediatric extensions and litigation outcomes. Any investment or licensing analysis should rely on the applicable current Orange Book edition and FDA approval records.
What patents protect CREON?
CREON protection has historically depended more on formulation and manufacturing control than on a conventional active-ingredient patent. Pancrelipase is a complex mixture of enzymes rather than a single newly invented small molecule.
Potential protection categories include:
- Enteric or delayed-release dosage forms.
- Capsule architecture and release behavior.
- Enzyme activity ranges and potency specifications.
- Stabilization of lipase, amylase and protease.
- Granulation and coating processes.
- Manufacturing controls for porcine pancreatic extract.
- Product-specific dissolution and stability profiles.
- Methods for treating exocrine pancreatic insufficiency.
The strongest practical barrier is product development complexity. An applicant must control enzyme activity across multiple components, maintain stability through manufacturing and storage, demonstrate appropriate release characteristics and meet FDA requirements for a complex biological-derived drug substance.
That barrier is meaningful but not permanent. It does not eliminate generic risk once an ANDA applicant has developed a reproducible product and obtained FDA approval.
What generic entry risks exist for CREON?
Generic entry risk is rising because pancrelipase has substantial revenue potential and because FDA has developed product-specific regulatory expectations for pancreatic enzyme replacement products.
The main risks are:
- ANDA approval. A generic applicant must show pharmaceutical equivalence and bioequivalence under the applicable FDA framework.
- Patent certification. The applicant may file a Paragraph IV certification against listed patents.
- Patent litigation. CREON’s sponsor can sue within the statutory window, potentially triggering a 30-month stay of approval.
- Supply substitution. Pharmacies and payers may move patients once a lower-cost product is available.
- Formulary pressure. Managed-care organizations may require generic-first treatment or impose prior authorization on CREON.
- Price erosion. Even limited generic penetration can reduce net price through rebates and contracting.
FDA has approved generic pancrelipase products in certain strengths and presentations, although availability and commercial launch timing can vary by manufacturer, strength and litigation status.[5] The most exposed CREON products are high-volume strengths with clear reimbursement demand and sufficient commercial scale to support manufacturing.
Generic entry is unlikely to produce the immediate erosion seen with a simple oral tablet. Pancrelipase products require product-specific development, and prescribers may hesitate to switch patients with stable control. The likely sequence is gradual conversion through payer formularies, specialty pharmacy substitution and new-patient prescribing.
Has CREON faced supply-chain and manufacturing constraints?
Yes. CREON and other pancreatic enzyme products have experienced supply pressure in the United States. The FDA has reported shortages and limited availability affecting particular pancrelipase strengths and presentations.[6]
Supply constraints are commercially important for three reasons:
- They can defer revenue even when prescription demand is strong.
- They give competing products an opportunity to win prescriptions.
- They increase the importance of manufacturing redundancy and inventory planning.
Pancrelipase manufacturing is more difficult than manufacturing a conventional synthetic drug. The active material is derived from porcine pancreatic tissue, and the final product requires consistent enzyme activity, controlled release and stability. Raw-material sourcing, animal-health controls, batch variability and specialized testing can limit supply flexibility.
The same manufacturing complexity that supports CREON’s competitive position can also constrain growth. AbbVie must maintain sufficient inventory across multiple lipase strengths because patients require individualized dosing.
What is the Paragraph IV and litigation risk for CREON?
Paragraph IV risk depends on the patents listed for the specific CREON reference product and the applicant’s proposed product. A generic applicant can challenge listed patents by asserting that they are invalid, unenforceable or not infringed.
The main litigation issues are likely to involve:
- Whether a proposed formulation falls within the listed patent claims.
- Whether the applicant’s enzyme activity and release profile are equivalent.
- Whether manufacturing patents cover the generic process.
- Whether the asserted claims are valid over earlier pancrelipase formulations.
- Whether a patent is properly listed for the relevant NDA.
Publicly available CREON information does not support treating the product as protected by a single, definitive patent cliff. The commercial outcome will depend on the active Orange Book listings, ANDA filing dates, Paragraph IV notices, litigation settlements and the timing of generic approval.
Settlement agreements could delay launch, permit an authorized generic, restrict launch to selected strengths or establish a future entry date. Without a confirmed settlement document, a specific generic entry date should not be treated as established.
What is the FDA and Orange Book status of CREON?
CREON is an FDA-approved prescription drug under NDA 020725. Its regulatory status is separate from the Purple Book framework used for licensed biologics and biosimilars.
The FDA regulatory issues most relevant to CREON are:
- Approved delayed-release capsule strengths.
- Product-specific labeling for dosing with meals and snacks.
- Safety monitoring for fibrosing colonopathy at excessive doses.
- Prescription substitution and generic approval standards.
- Drug-shortage reporting and supply availability.
- Orange Book patent listings and certifications.
There is no biosimilar pathway for CREON. The competitive threat comes from generic or follow-on pancrelipase products approved under the Federal Food, Drug, and Cosmetic Act, not from biosimilar applicants under the Public Health Service Act.[1][4]
How does CREON compare with Zenpep and Pertzye?
| Factor |
CREON |
Zenpep |
Pertzye |
| Market position |
Largest U.S. brand |
Major competitor |
Smaller branded competitor |
| Active ingredient |
Pancrelipase |
Pancrelipase |
Pancrelipase |
| Delivery |
Delayed-release capsules |
Delayed-release capsules |
Delayed-release capsules |
| Core advantage |
Scale, physician familiarity, broad use |
Commercial competition and formulary access |
Product differentiation and specialty focus |
| Main risk |
Generic entry and shortages |
CREON brand scale |
Smaller commercial footprint |
| Switching barrier |
Dose conversion and clinical familiarity |
Same |
Same |
CREON’s strongest advantage is commercial scale. Zenpep and Pertzye remain credible alternatives because pancreatic enzyme therapy is clinically familiar across brands and because supply or formulary changes can drive switching.
What is the long-term financial trajectory for CREON?
The base-case trajectory is continued revenue growth at a slower rate than the recent expansion. The franchise has several years of demand support from chronic treatment, underdiagnosis and specialty prescribing. Growth should moderate as the treated population matures and generic competition expands.
| Period |
Financial outlook |
| Near term |
Revenue supported by chronic demand, pricing and limited substitution |
| Medium term |
Growth moderated by generic approvals, payer pressure and supply normalization |
| Long term |
Greater price erosion risk, with revenue dependent on brand retention and manufacturing differentiation |
CREON’s revenue exposure is material for AbbVie’s gastroenterology portfolio but modest relative to Skyrizi, Rinvoq and the company’s broader immunology business. That limits company-wide concentration risk while preserving CREON’s value as a durable specialty franchise.
The most important commercial variables are generic launch timing, the number of strengths exposed, the extent of pharmacy substitution, supply reliability and payer contracting. A delayed or limited generic launch would extend CREON’s high-margin period. Broad generic availability across major strengths would accelerate net-price erosion.
Key Takeaways
- CREON is a pancrelipase drug product, not a Purple Book biologic.
- AbbVie’s CREON revenue has grown from roughly $0.9 billion in 2020 to approximately $1.6 billion in 2024.
- Chronic dosing, cystic fibrosis, pancreatic surgery and increasing diagnosis of exocrine pancreatic insufficiency support demand.
- Zenpep and Pertzye are the leading branded competitors.
- The principal long-term threat is generic pancrelipase, not biosimilar competition.
- Manufacturing complexity creates a meaningful barrier but does not prevent generic entry.
- Supply shortages have created both revenue constraints and switching opportunities for competitors.
- CREON’s exclusivity cannot be analyzed through one patent expiration date. Orange Book listings, Paragraph IV filings, litigation and settlements determine the practical entry timetable.
- Revenue growth is likely to moderate as generic availability expands and payer pressure increases.
FAQs
Is CREON a biologic drug?
No. CREON is an FDA-approved pancrelipase drug product. Although its enzymes are derived from porcine pancreatic tissue, CREON is not a biologic licensed under a BLA and is not subject to the biosimilar pathway.
Can pharmacies automatically substitute generic pancrelipase for CREON?
Substitution depends on the approved product, state pharmacy law, payer policy and the applicable FDA equivalence rating. Enzyme strength and release characteristics must match the prescribed product and dose.
Does CREON have orphan-drug protection?
Orphan-drug protection depends on the specific indication and approval history. Any orphan exclusivity would apply to the qualifying indication rather than automatically creating permanent market protection for every CREON use.
Why is generic CREON difficult to manufacture?
Pancrelipase contains multiple enzymes with different activity requirements. Manufacturers must control porcine raw materials, enzyme potency, stability, enteric release and batch consistency.
Which CREON strengths are most exposed to generic competition?
High-volume strengths with established reimbursement demand are generally the most commercially attractive targets. Exposure depends on the strength-specific approval, patent certifications, launch plans and payer adoption.
References
- U.S. Food and Drug Administration. (2024). CREON (pancrelipase) delayed-release capsules prescribing information.
- AbbVie Inc. (2024). Annual report for the year ended December 31, 2023.
- AbbVie Inc. (2025). Annual report for the year ended December 31, 2024.
- U.S. Food and Drug Administration. (2024). Approved drug products with therapeutic equivalence evaluations: Orange Book.
- U.S. Food and Drug Administration. (2024). Product-specific guidance for pancrelipase delayed-release capsules.
- U.S. Food and Drug Administration. (2024). Drug shortages: Pancrelipase delayed-release capsules.